
Macmahon Shares In Focus After New Dividend Payment
- Macmahon Holdings has paid a total dividend of A$0.01 per share, following an ex-dividend date on 18 September 2026 and continuing its bi-annual payout pattern since 2019.
- The low payout ratio, supported by strong profitability metrics, indicates that Macmahon Holdings is retaining a significant portion of its earnings to reinvest in operations and projects while still returning cash to shareholders.
- This article will now explore how Macmahon Holdings' latest A$0.01 dividend, supported by a low payout ratio, might influence its broader investment narrative.
Compare Macmahon Holdings' dividend profile with other income-focused opportunities by scanning a curated set of 3 dividend fortresses that may offer similar cash returns with different risk profiles.
Macmahon Holdings Investment Narrative Recap
To own Macmahon Holdings, you need to believe the contractor can keep winning and extending long duration mining and civil work while holding its margins together. The recent A$0.01 dividend, backed by a low payout ratio, does not fundamentally shift that thesis. The more important near term swing factor remains how effectively the group converts its order and tender pipeline into secured projects.
The biggest risk is still contract concentration and pricing pressure. Large customers can change mining models or retender work, which can hit revenue if replacement projects are slow to appear. Expansion into lower margin civil infrastructure and the use of higher risk funding sources also put more onus on disciplined project selection and cost control.
In that context, the dividend announcement is most closely tied to Macmahon Holdings maintaining profitability and cash flow quality. Earnings have grown 15.5% per year over the past 5 years, and current net profit margins of 3.9% sit above last year’s 3%. A low payout ratio suggests management wants room to keep investing in fleet, technology and contract execution while still sharing some cash with investors.
For you, the key question is whether that A$0.01 payment signals confidence in the existing book of work and the forecast 7.3% annual revenue growth, or simply reflects current earnings strength. If future tenders became more aggressive on pricing or major contracts were not renewed, the dividend could come under pressure, so the sustainability of this payout will depend on how well Macmahon Holdings manages contract renewal, capital intensity and debt funded growth from here.
Macmahon Holdings' current analyst narrative points to A$3.1b revenue and A$131.3m earnings by 2029, based on assumed 6.3% yearly revenue growth and an increase of about A$30.2m in earnings from A$101.1m today.
Uncover how Macmahon Holdings' fair value indicates a 17% potential downside to its current price, creating a pricing gap that leaves little room for error.
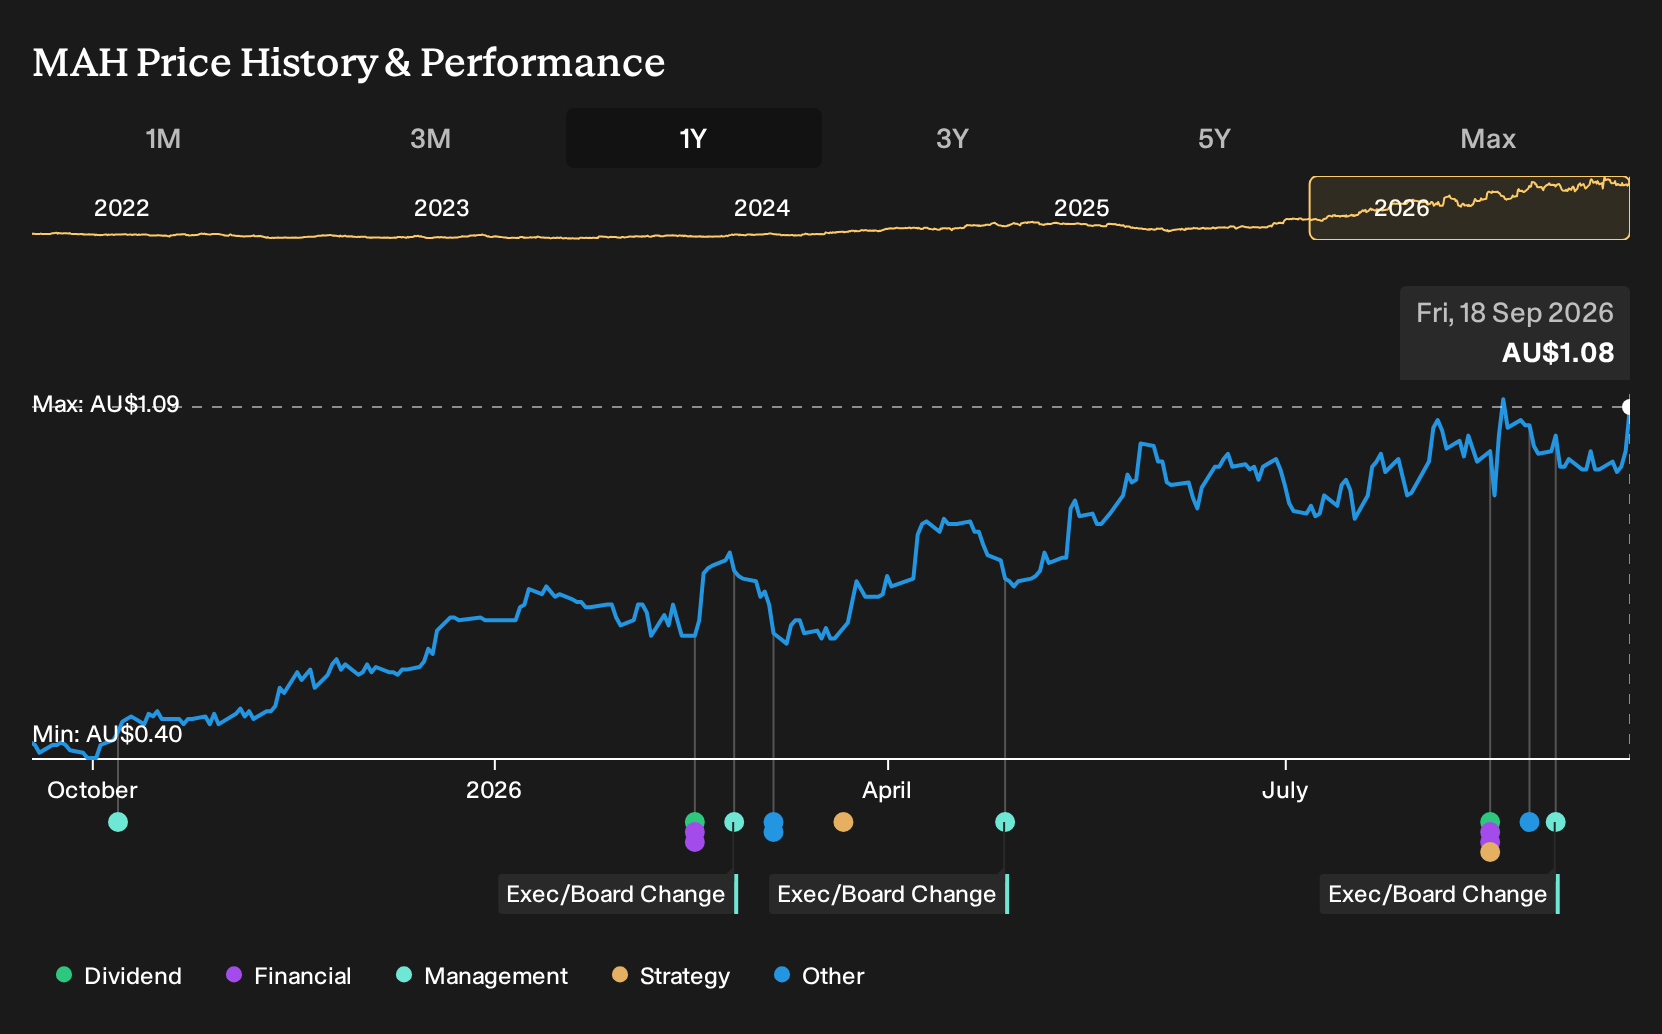
Exploring Other Perspectives
One optimistic twist on Macmahon Holdings comes from analysts who see Decmil as a far bigger earnings swing factor than the dividend. That group was already modelling A$3.2b of revenue and about A$132.4m of earnings by 2029, a touch above consensus, and the new A$0.01 payout could nudge those forecasts or challenge them. Use this dividend as a prompt to compare those bullish assumptions with your own view and explore how different forecasts might evolve from here.
Explore 5 other Macmahon Holdings fair value estimates, including one that suggests as much as 133118% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Macmahon Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Macmahon Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Macmahon Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Macmahon Holdings?
Once you have a view on Macmahon Holdings, it can help to widen the lens and line it up against other listed businesses with different income, quality and risk profiles.
- If you want potential growth with a small starting price, scan a focused set of 16 elite penny stocks with strong financials that fit tighter financial filters than the wider market.
- For investors who care most about quality at a reasonable entry point, compare Macmahon Holdings with a curated pool of 5 high quality undervalued stocks that pair stronger balance sheets with cleaner cash generation.
- When capital preservation matters more than chasing every uptick, anchor your watchlist around a carefully filtered group of 7 resilient stocks with low risk scores that score better on stability and downside resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com