
Will Trade Down Grocery Demand Change Grocery Outlet Stock Narrative
- Grocery Outlet Holding operates discount grocery stores in the US and is seeing stronger interest from shoppers looking to stretch food budgets as higher gas, food and housing costs pressure household finances.
- The business uses its value-focused model to attract budget conscious consumers who are trading down on everyday essentials. This puts its independent operator structure and opportunistic buying approach under a brighter spotlight as wallets tighten.
- We will now explore how Grocery Outlet Holding's investment narrative could be influenced by rising consumer demand for lower priced grocery options.
Scan for other discount focused retailers that could benefit from the same trade down pressure squeezing Grocery Outlet Holding by starting with our curated 35 high quality undervalued stocks.
Grocery Outlet Holding Investment Narrative Recap
For Grocery Outlet Holding, the core belief is that value focused grocery formats can keep drawing budget stretched shoppers even as conditions shift. The immediate operational swing factor is whether trade down traffic translates into healthier baskets as inventory tools, merchandising tests and private label offers get scaled. The recent macro pressure on consumers largely reinforces that near term demand story rather than changing it.
The bigger risk sits on the cost and balance sheet side. Grocery Outlet Holding is still loss making, interest is not well covered by earnings and wage and rent pressures can squeeze SG&A. If store expansion or tech investments fail to lift productivity, that could delay any improvement in margins and returns.
With no fresh announcements tied directly to this latest consumer squeeze, the most relevant reference point is still the ongoing cost reduction program and planned SG&A savings flagged for 2026. Those efforts matter more when shoppers are hunting for bargains and every basis point of expense control has extra weight.
If Grocery Outlet Holding can line up expense discipline with its independent operator model and opportunistic buying, that combination remains central to the potential catalyst story. The flip side is execution risk. Weaker than expected efficiencies or slower margin progress would leave the business more exposed to its existing leverage and to any cooling in value oriented grocery demand.
Grocery Outlet Holding's narrative projects US$5.5b revenue and US$59.5 million earnings by 2029. This projection is based on analysts assuming 5.0% yearly revenue growth and an earnings improvement of about US$441 million, from a current loss of US$381.3 million to the forecast earnings level.
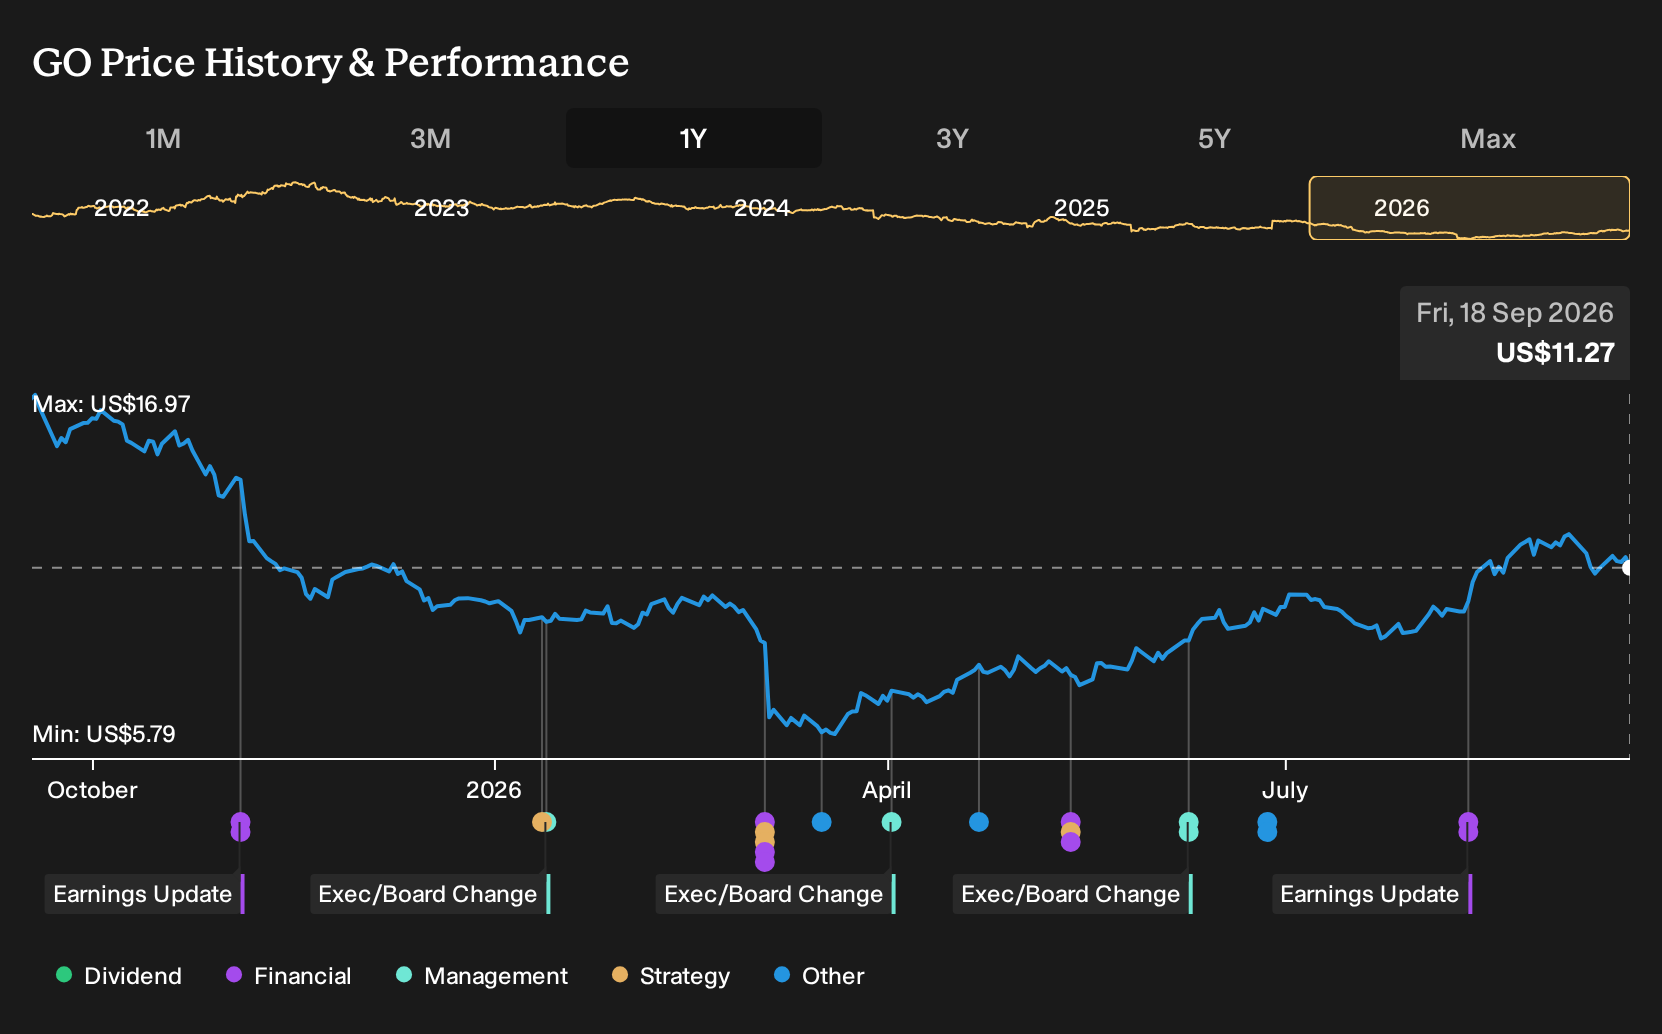
Uncover why Grocery Outlet Holding's fair value indicates a 5% potential downside to its current price that leaves little room for error.
Exploring Other Perspectives
One alternate storyline around Grocery Outlet Holding focuses less on store execution and more on digital risk. The most bearish analysts were only modeling about 2.6% yearly revenue growth and earnings of roughly US$2.5 million by 2029 before this consumer squeeze. That is far below consensus, and it shows how sharply views can differ. This fresh macro news could easily shift both camps, so it helps to compare several narratives before you decide what feels reasonable.
Explore another Grocery Outlet Holding fair value estimate, including one that suggests it could be worth just $10.73.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Grocery Outlet Holding research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Grocery Outlet Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Grocery Outlet Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond Grocery Outlet Holding?
If the Grocery Outlet Holding story has you thinking about where else trade downs, healthy balance sheets or steadier income profiles might matter, it can help to scan a wider set of stocks using the Simply Wall St Screener. Pick the angle that matches what you want from the market and let the filters do the heavy lifting.
- If you want steady cash flows and fewer surprises, start with a basket of companies that score well on resilience and financial risk by running the 30 resilient stocks with low risk scores.
- For investors who care most about balance sheet strength and fundamental quality, filter for businesses with robust assets and manageable debt using the list of solid balance sheet and fundamentals (23 results).
- If you prefer to hunt for potential mispriced opportunities before they are widely followed, look through the 16 high quality undiscovered gems and see which stories deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com