
Brewing Unit Shutdown Might Change The Case For Investing In Middleby (MIDD)
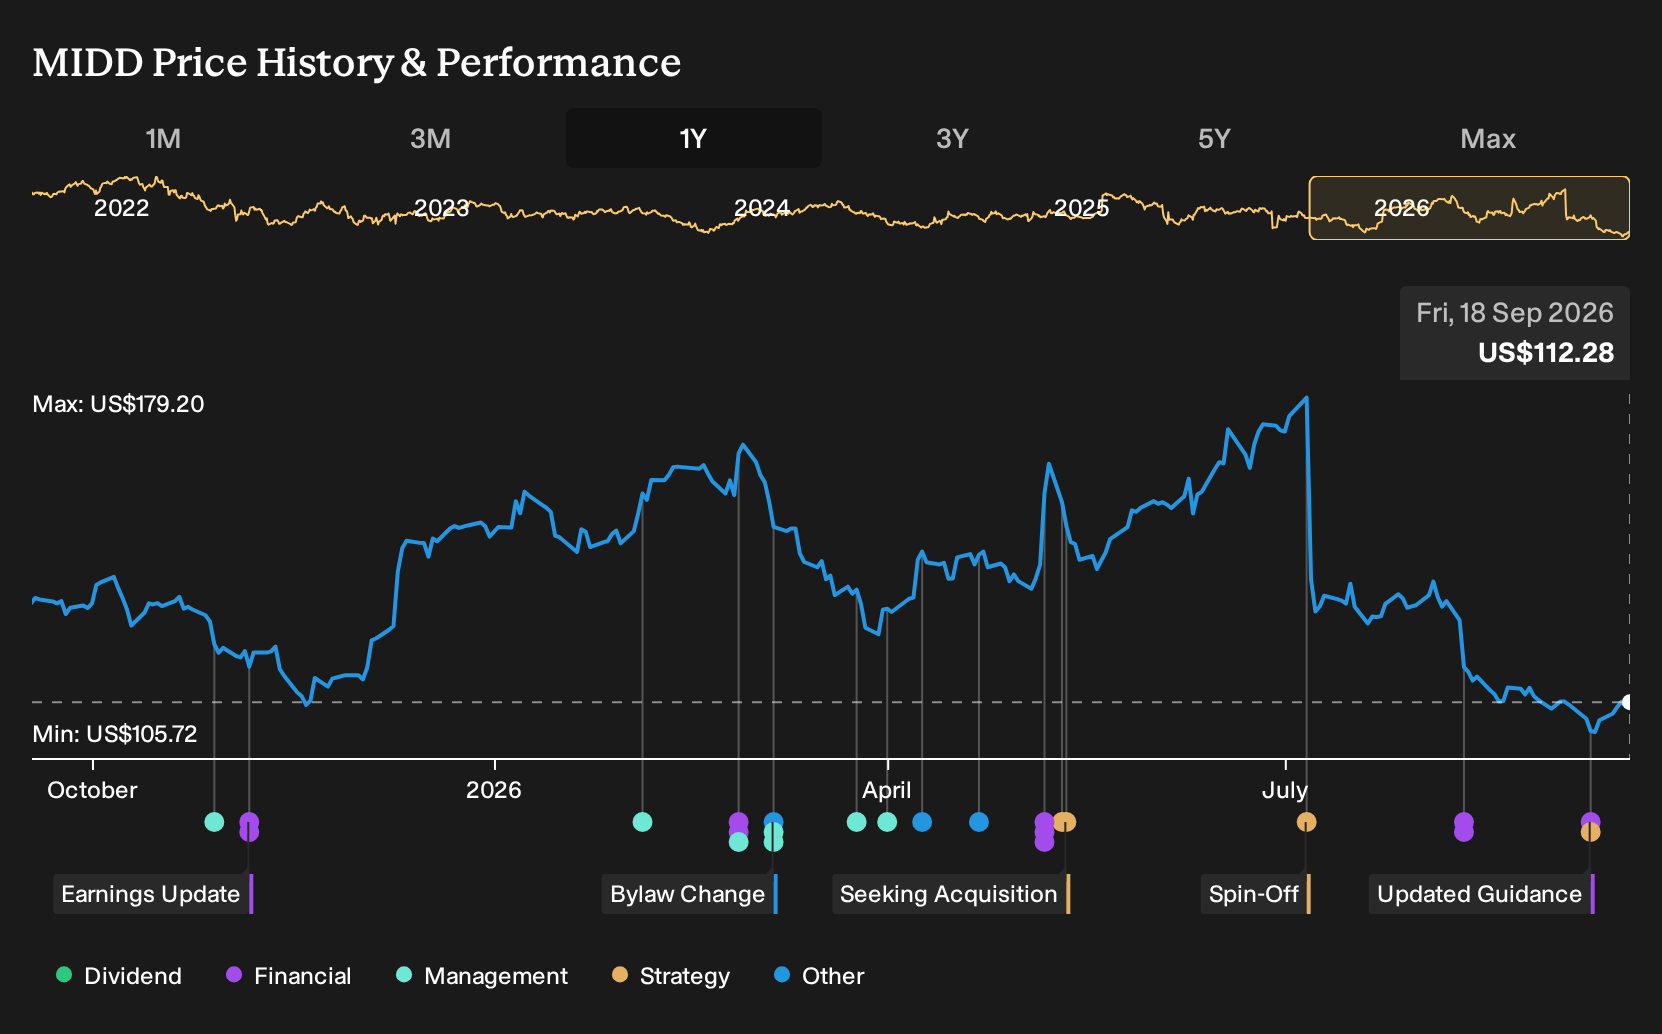
- Middleby announced in early September 2026 that it would shut down its Brewing & Distilling Solutions Group, covering Deutsche Beverage + Process, Ss Brewtech and Wild Goose Filling, and still expects Q3 net sales of US$620 million to US$640 million and full year 2026 sales of US$2.48b to US$2.53b.
- The closure of the Brewing Group signals that management is willing to exit non-core beverage equipment in order to simplify operations and concentrate capital on businesses that better fit Middleby's long term growth and margin priorities.
- We will examine how Middleby's investment narrative evolves as it reallocates capital after winding down the Brewing Group operations.
Scan how Middleby’s portfolio reshuffle compares with other equipment makers refocusing on higher margin lines by reviewing the curated list of solid balance sheet and fundamentals (23 results).
Middleby Investment Narrative Recap
To own Middleby, you need to be comfortable with a kitchen equipment group that is leaning hard into higher margin, tech enabled systems while headline revenue is expected to drift lower over the next few years. The near term story still revolves around demand from restaurant and food processing customers and how quickly deferred replacement cycles convert into actual orders.
The shutdown of the Brewing Group looks contained, given management kept Q3 and full year 2026 sales guidance intact. The key near term catalyst remains execution on automation, IoT and energy efficient platforms. The biggest current risk is that cost inflation, tariffs and delayed capex keep squeezing margins and slow that earnings trajectory.
The most relevant update for this shift is Middleby reiterating its Q3 2026 and full year 2026 net sales guidance alongside the Brewing Group closure. Management still expects US$620 million to US$640 million of net sales for Q3 and US$2.48b to US$2.53b for the year, which frames the Brewery exit as manageable in scale.
For you, that guidance matters because the main operational debate is not about one discontinued segment. It is about whether Middleby can grow earnings from roughly US$320 million today while tariffs, weaker QSR traffic and delayed upgrades weigh on volumes. Hitting or missing these 2026 ranges will shape confidence in that earnings path.
Middleby's narrative projects US$2.8b of revenue and US$360.7 million of earnings by 2029. This assumes revenue declines at 5.8% per year and implies an earnings increase of US$40.7 million from US$320.0 million today.
Uncover why Middleby's fair value indicates a 39% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on Middleby focuses on a sharper drop in demand. The most pessimistic analysts were already modeling revenue shrinking about 7.6% a year and earnings of roughly US$350.1 million by 2029. That is a much harsher story than consensus, and the Brewing Group exit could prompt those views to shift again.
Explore another Middleby fair value estimate, including one that suggests up to 6% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Middleby research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Middleby. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Middleby's overall financial health at a glance.
Looking for more Middleby style investment ideas?
If Middleby has you thinking about portfolio quality, use that same lens across the market by filtering for balance sheets, income strength and risk profiles that fit your own playbook.
- For investors who want a wider pool of potential bargains with solid fundamentals, start with a curated set of 35 high quality undervalued stocks and see which businesses line up with your return goals and risk comfort.
- If capital preservation and a smoother ride are higher on your list, focus on companies that score well on resilience by scanning the 30 resilient stocks with low risk scores that filters for sturdier financial profiles.
- When income matters as much as price, zero in on reliable cash payers by reviewing a focused group of 7 dividend fortresses that combine higher yields with more robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com