
Marriott International (MAR), Why Is It Drawing Fresh Attention?
Marriott International (MAR) has put two very different cards on the table this month. A planned Ritz-Carlton all-inclusive resort in Türkiye and a new Spotnana tech tie-up both point to targeted expansion.
Marriott International’s recent partnership news lands against a mixed tape. The 1-day share price return of 1.47% and 7-day gain of 1.26% contrast with a 30-day move that is down 4.9% and a 90-day decline of 11.78%. At the same time, the year-to-date share price return of 8.14% sits alongside a 1-year total shareholder return of 27.27% and a 5-year total shareholder return of 131.8%, suggesting longer term momentum has been stronger than the latest quarter.
Spot emerging travel and leisure plays that reflect themes similar to Marriott International's latest expansion and technology initiatives by scanning the hand-picked 16 high quality undiscovered gems.Bulls point to Marriott International's long run of shareholder returns and fresh growth bets in Türkiye and tech. Bears focus on recent share price weakness and a rich-looking market value. Which side does the current valuation lean toward?
Most Popular Narrative: 11% Undervalued
Marriott International’s most followed narrative pegs fair value at $380.83 per share, above the last close of $338.92. This frames the current pullback as a potential valuation gap rather than a clean verdict on the business.
Global expansion continues to accelerate, with net rooms growth approaching 5% and a record pipeline (over 590,000 rooms, 40% under construction). This reflects strong demand for Marriott's brands in international markets, particularly APAC and EMEA, where a rising middle class is driving double-digit RevPAR increases and providing a foundation for multi-year revenue growth.
See why 31 investors see Marriott International as 11% undervalued.
Result: Fair Value of $380.83 (UNDERVALUED)
Still, the bullish Marriott International narrative hinges on assumptions that heavy technology spending pays off and that regional RevPAR softness does not drag on earnings power.
Find out about the key risks to this Marriott International narrative.
Another Take On Marriott International’s Valuation
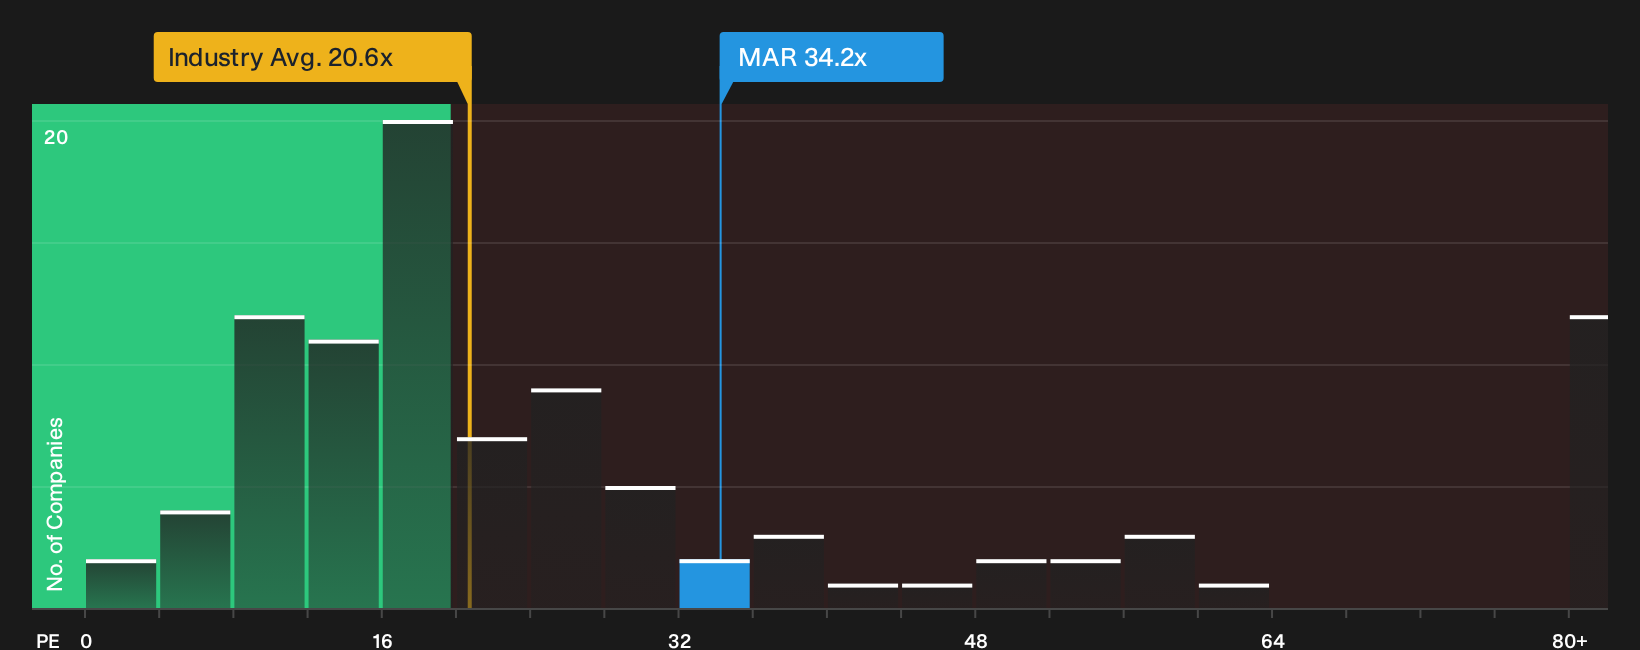
That 11% perceived discount to fair value runs into a very different story once simple P/E math is applied. Marriott International trades on a 34.2x P/E, while the fair ratio sits at 27.6x, the US Hospitality group at 20.6x, and close peers at 28.1x. That is a rich premium. Is the extra price tag justified by future execution, or is it loading more valuation risk onto recent buyers?
Before leaning on the analyst narrative alone, it is worth seeing how those P/E gaps stack up across forecasts, peers, and the fair ratio in more detail. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Marriott International's valuation and growth bets do not have to dictate your view. Act while sentiment is split and weigh both sides yourself by checking the 2 key rewards and 1 important warning sign.
Ready to find your next idea beyond Marriott International?
Do not stop at one opportunity. Broaden your watchlist with fresh angles so you are not relying on a single story to carry your portfolio.
- Target potential value opportunities by scanning a focused list of companies that screen as 35 high quality undervalued stocks.
- Build resilience into your holdings by checking out a list of solid balance sheet and fundamentals (23 results) that can help support returns through different market conditions.
- Tilt your income stream by reviewing 7 dividend fortresses that may offer higher yields without stepping too far out on the risk curve.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com