
Shanghai Electric Group (SEHK:2727) Lands Malaysia Energy Deal On Valuation Questions
Shanghai Electric Group (SEHK:2727) recently secured a full EPC turnkey contract and a 25-year service agreement for Unit 3 of the Sarawak Samalaju CCGT Project in Malaysia, highlighting its overseas high-end energy ambitions.
Recent trading reflects that mix of excitement and caution. Shanghai Electric Group’s share price has moved to HK$3.02 after a 1-day share price return of 5.23%, yet the 90-day share price return is down 20.94% while the 3-year total shareholder return of 70.39% shows a much stronger longer-term picture. This suggests that momentum has cooled recently even as longer-horizon investors have still seen meaningful gains.
Scan for other capital goods stocks pursuing large-scale energy contracts with robust balance sheets by reviewing the curated list of solid balance sheet and fundamentals (198 results) together with Shanghai Electric Group.
Shanghai Electric Group now trades at HK$3.02 while analyst targets and intrinsic estimates sit higher. The real puzzle is where fair value lies inside that spread.
Price-to-Earnings of 29.6x: Is it justified?
Shanghai Electric Group trades on a P/E of 29.6x, which places a clear premium on the HK$3.02 share price relative to peers and sector benchmarks.
The P/E ratio compares the current share price to earnings per share. For a capital goods business with exposure to large power and equipment projects, that metric often reflects what investors are willing to pay today for each unit of current profit.
For Shanghai Electric Group, high quality earnings and a return to profitability sit alongside a relatively low 3.4% Return on Equity and earnings that are expected to grow 9.3% per year, which is slower than the wider Hong Kong market. That combination indicates the market is paying a premium for profit growth that is not especially fast and for a profitability profile that remains modest.
The premium becomes clearer when comparing the 29.6x P/E to the Asian Electrical industry average of 29.3x and a peer average of 19.5x. The stock also trades well above an estimated fair P/E of 11.9x, a level the valuation work suggests the market could eventually move closer to if expectations cool.
Explore the SWS fair ratio for Shanghai Electric Group.
Result: Price-to-Earnings of 29.6x (OVERVALUED)
Still, Shanghai Electric Group faces risks if analysts cut price targets or if large EPC projects are delayed or repriced, which could pressure that valuation premium.
Find out about the key risks to this Shanghai Electric Group narrative.
Another View on Shanghai Electric Group’s Valuation
The P/E screen presents Shanghai Electric Group as expensive, yet our DCF model suggests a different perspective. At HK$3.02, the stock trades about 20.5% below an estimated future cash flow value of HK$3.80, which frames the current quote as a possible discount. Which approach do you find more convincing?
Look into how the SWS DCF model arrives at its fair value.
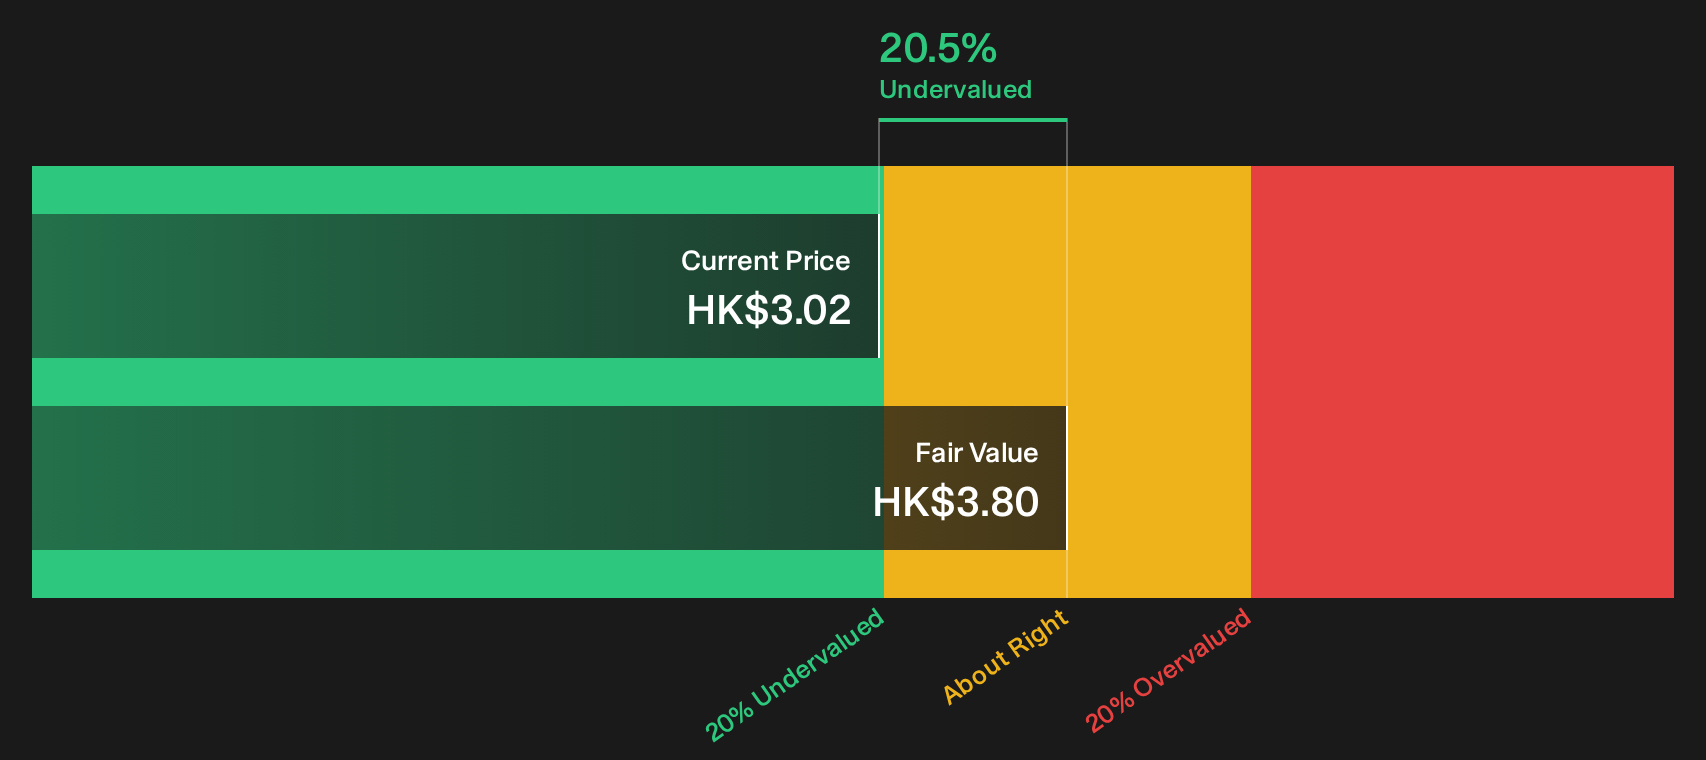
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shanghai Electric Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 180 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment across Shanghai Electric Group is mixed, so treat this as a prompt to move fast, inspect the numbers yourself, and weigh the upside. To help frame that upside in a structured way, review the 3 key rewards
Looking for more Shanghai Electric Group style investment ideas?
Shanghai Electric Group gives you one angle on the market, but you miss a lot of potential if you stop your research here. Cast the net wider and let data do the heavy lifting so you can focus on choosing which opportunities deserve your time.
- Target steadier opportunities by reviewing 226 resilient stocks with low risk scores that aim to keep volatility and balance sheet stress in check.
- Hunt for potential bargains using the 180 high quality undervalued stocks that highlights businesses with strong fundamentals trading below estimated value.
- Strengthen your income watchlist through the 158 dividend fortresses and focus on companies offering higher yields with an emphasis on resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com