
Prologis (PLD) Could Be 14% Below Fair Value As Leasing And Data Center Demand Build
Prologis stock: Q3 leasing momentum and data center push
Prologis (PLD) is leaning into data center demand while expecting third quarter lease signings near recent records of 60 million to 65 million square feet, supported by high occupancy and a substantial development pipeline.
Management also points to a 17% lease mark to market gap, roughly US$700 million of potential incremental revenue, and about 10% of new leasing tied to data center infrastructure and 5.8 gigawatts of planned power capacity.
Recent price action around Prologis has been more muted than the operational headlines. The share price is down 4.9% over the past 30 days and 6.3% over 90 days. At the same time, the year-to-date share price return is positive at 4.5%, and the 1-year total shareholder return is 22.5%. This suggests that momentum has cooled in the short term, while longer term holders have still seen solid gains as the data center and leasing story has taken shape alongside fresh institutional interest from firms such as Massachusetts Financial Services and Dimensional Fund Advisors.
Compare Prologis' leasing and data center story with other real estate plays by scanning 88 AI infrastructure stocks, which are building the backbone for high-power computing demand.
Prologis is signing near record leases, leaning into data centers, and yet the share price has cooled in recent months. Does that combination still justify the current valuation or give buyers a margin of safety from here?
Most Popular Narrative: 14% Undervalued
Prologis last closed at $134.84, while the most followed narrative puts fair value around $156.07. The current price sits below that framework and leans on leasing strength, data centers and a higher required return of 8.74%.
The continued expansion in value-added services (like renewable/distributed energy solutions and data centers) further diversifies revenue streams and leverages long-term trends toward automation and electrification in warehouse operations, which is likely to provide incremental NOI and margin expansion opportunities. As e-commerce and last-mile delivery maintain secular growth, especially in densely populated urban centers, Prologis' global scale and high-barrier market exposure allow for premium pricing and higher occupancy, positioning the company for above-average revenue growth and long-term earnings outperformance.
See why 108 investors see Prologis as 14% undervalued.
Result: Fair Value of $156.07 (UNDERVALUED)
Still, the narrative can break if leasing remains slower than normal, and if elevated market vacancy and bad debt continue to press on Prologis cash generation and pricing power.
Find out about the key risks to this Prologis narrative.
Another View on Prologis Valuation
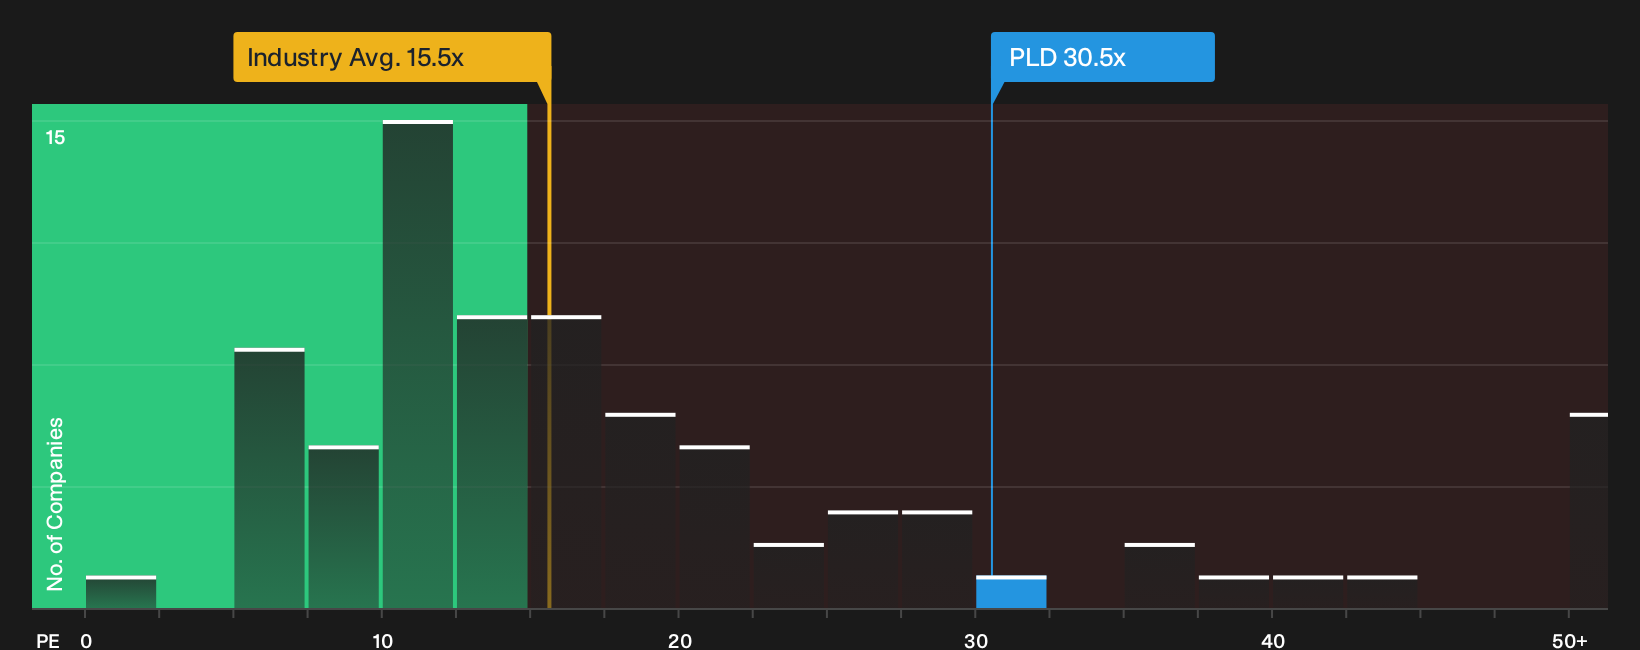
While the popular narrative frames Prologis as about 14% undervalued, its P/E of 30.5x paints a different picture. The stock trades well above the Global Industrial REITs average of 15.5x and ahead of peer levels at 26.5x, yet hovers close to its 31.4x fair ratio. Is that a premium you are comfortable paying for this earnings profile?
For a closer look at what this richer earnings multiple might imply over time, have a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Prologis can feel messy, so move quickly from headline impressions to hard facts and weigh both sides of the ledger. To pressure test the judgment call and balance what could go right against what might go wrong, start with the 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Prologis?
Do not stop at Prologis. Use this momentum to widen your opportunity set and line up the next few ideas before the crowd catches on.
- Target resilient balance sheets by scanning companies on the list of solid balance sheet and fundamentals (23 results) that may handle tough conditions better than highly leveraged peers.
- Hunt for mispriced quality and review the 35 high quality undervalued stocks to see which businesses combine stronger fundamentals with prices that sit below their implied worth.
- Spot early stage potential and filter for future contenders using the 16 high quality undiscovered gems before wider coverage and attention narrow the gap.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com