
Is MSA Safety (MSA) A Bargain As New Safety Gear Broadens Its Product Range?
MSA Safety (MSA) has been busy rolling out new gear, including advanced firefighting suits and helmets with Bristol Uniforms, a refreshed industrial hard hat, and a redesigned WinGrip A1X aircraft maintenance anchor.
These launches come after an active year for MSA Safety. A 90 day share price return of 9.58% and a year to date share price gain of 10.74% contrast with a 30 day decline of 5.16%, while the 1 year total shareholder return of 6.34% points to steadier long run compounding than recent volatility might suggest.
Scan for other safety-focused stocks with strong product pipelines by checking out our curated list of 16 high quality undiscovered gems, which could be flying under most investors radar.
Bulls point to MSA Safety's steady shareholder returns and expanding product suite. Bears focus on the recent pullback and rich rating signals. Which side does the current valuation lean toward as the next step?
Most Popular Narrative: 13% Undervalued
MSA Safety closed at $179.66, while the most followed narrative maps out a fair value of $205.71 based on a 7.11% discount rate. That gap rests on the idea that connected safety products and acquisitions can keep earnings compounding from here.
Robust growth in connected safety solutions (such as MSA+ and ALTAIR io 4) reflects increasing customer adoption of advanced, cloud-connected worker technologies, a trend driven by heightened workplace safety requirements and industrial digitization. This positions MSA for above-average revenue and margin expansion as these premium products command higher prices.
See why 4 investors see MSA Safety as 13% undervalued.
Result: Fair Value of $205.71 (UNDERVALUED)
Still, MSA Safety’s story can be knocked off course if foreign exchange and tariff costs squeeze margins, or if core Fire Service and PPE demand remains soft.
Find out about the key risks to this MSA Safety narrative.
Another Look At MSA Safety’s Valuation
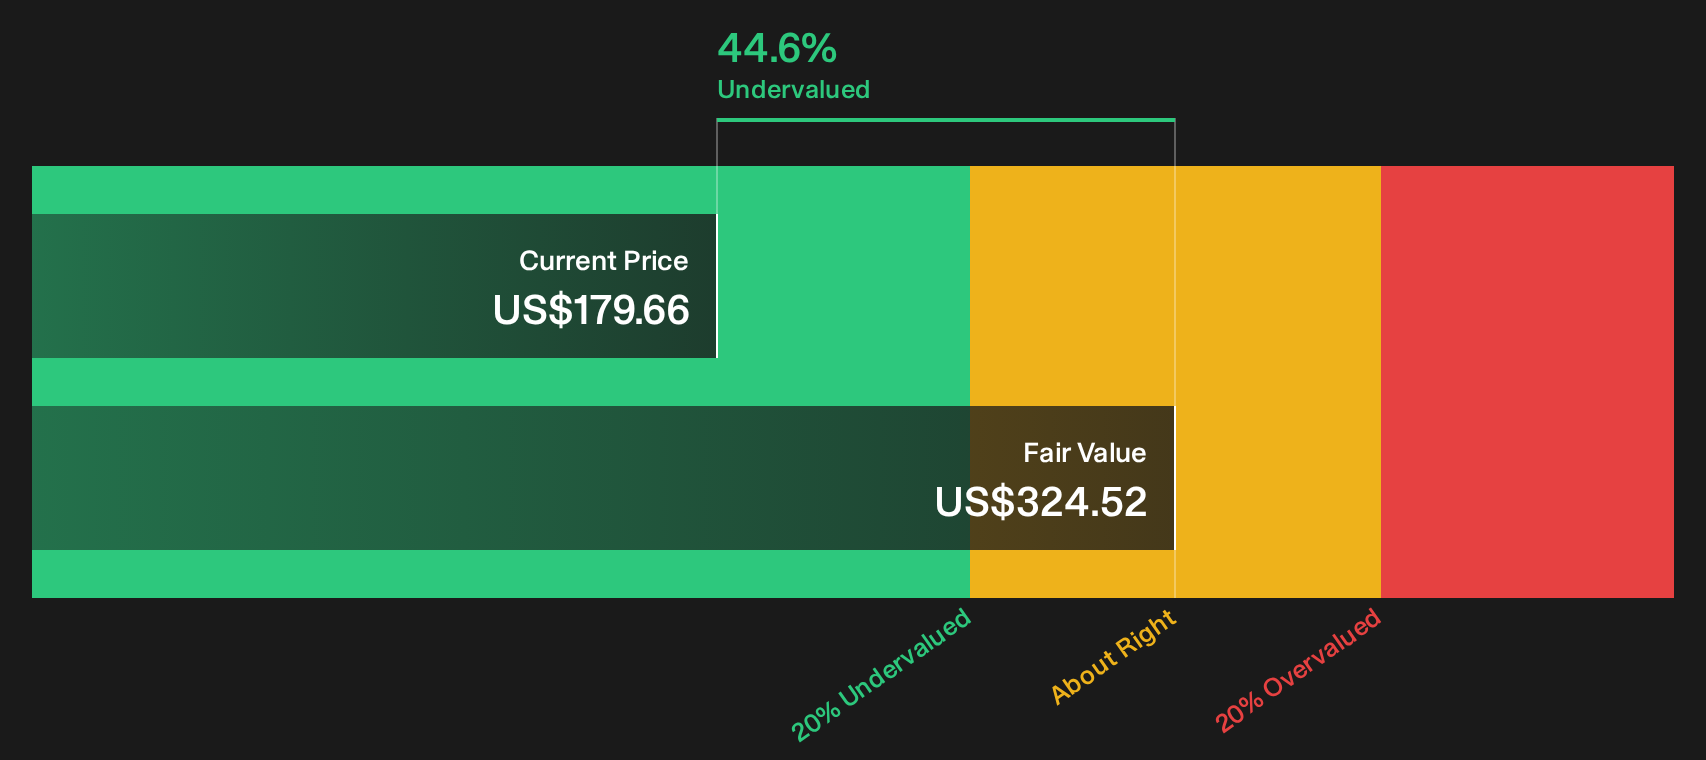
The first narrative leans on discounted cash flows and arrives at a fair value of $205.71 for MSA Safety, which implies upside from the current $179.66 share price. On simpler earnings measures, the picture is less generous. The stock trades on a P/E of 22.1x, compared with 18.3x for the wider US Commercial Services group and 15.6x across closer peers, while the fair ratio sits lower again at 18.8x. That gap suggests investors are already paying a premium for quality, so the real question is whether you see that as justified resilience or valuation risk if sentiment cools.
To pressure test that premium against a full cash flow view, it helps to see how our DCF approach tackles MSA Safety’s future assumptions in detail. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around MSA Safety's valuation and outlook make this a judgment call rather than a simple yes or no. Act quickly on your curiosity and walk through both sides of the story by reviewing the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond MSA Safety?
If you only stop at MSA Safety, you risk missing other opportunities that fit your style, your risk comfort, and the kind of returns you are aiming for.
- Target potential mispricings by scanning a curated mix of quality businesses trading below fair value through the 35 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies with robust cash payouts using the 7 dividend fortresses.
- Protect your capital by zeroing in on companies with resilient profiles through the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com