
Astroscale Holdings (TSE:186A) Wins France 2030 Contract, Is The Valuation Already Priced In?
Astroscale Holdings stock: earnings pressure meets France 2030 contract
Astroscale Holdings (TSE:186A) has been in focus after a wider quarterly loss coincided with news of a €13.2 million France 2030 deorbiting mission contract involving Exotrail and Eutelsat.
That backdrop helps explain why Astroscale Holdings has seen a sharp mood swing in recent sessions. The 1-day share price return of 7.86% and 7-day gain of 14.16% follow a 30-day share price return that declined 7.24%, while the year-to-date share price return of 66.86% and 1-year total shareholder return of 65.90% reflect strong but recently volatile momentum as investors weigh contract-driven potential against ongoing losses.
Scan beyond Astroscale Holdings and see how other space and infrastructure plays are priced today with our hand picked 75 high quality undiscovered gems for this theme.
Astroscale Holdings now trades around a 6% discount to analyst targets and an even larger gap to some fair value estimates. After the recent surge, is that a genuine margin of safety, or a warning that losses still matter more than contracts?
Preferred Price-to-Sales of 27.8x: Is it justified for Astroscale Holdings?
On headline valuation, Astroscale Holdings looks expensive compared with both its own fair ratio and the wider Aerospace & Defense peer group. The shares last closed at ¥1,153, while the stock is described as trading at a 13.0% discount to an internal fair value estimate. However, the P/S multiple of 27.8x points to a very rich top line valuation relative to revenue.
The preferred gauge here is the price-to-sales ratio, which compares Astroscale Holdings' market value with its ¥5,886.0 million in revenue. For a business that is still loss making, investors often lean on P/S as a rough way to weigh how much they are paying for each unit of current sales when earnings are not yet a helpful guide.
Against that backdrop, the 27.8x P/S figure looks high when set beside both the estimated fair P/S ratio of 3.5x and the Asian Aerospace & Defense industry average of 6.9x. Even relative to a peer average of 21.1x, Astroscale Holdings trades on a richer sales multiple. This suggests the market is placing a sizeable premium on its growth profile and future profitability that could compress if expectations cool.
Explore the SWS fair ratio for Astroscale Holdings.
Result: Price-to-sales of 27.8x (OVERVALUED)
Still, the narrative around Astroscale Holdings can crack if contract timing slips or if losses near ¥8,558 million persist longer than investors expect.
Find out about the key risks to this Astroscale Holdings narrative.
Another view on Astroscale Holdings valuation
The high 27.8x P/S ratio paints Astroscale Holdings as expensive today. Yet the SWS DCF model points the other way, with a fair value estimate of ¥1,326.02 versus the current ¥1,153. That implies the cash flow view sees the shares as undervalued rather than frothy.
This sort of clash between a rich sales multiple and an apparently supportive cash flow model leaves a simple question for investors: Which lens deserves more weight for a loss making growth story that still needs to prove its economics at scale, the revenue multiple or the DCF outcome?
Look into how the SWS DCF model arrives at its fair value.
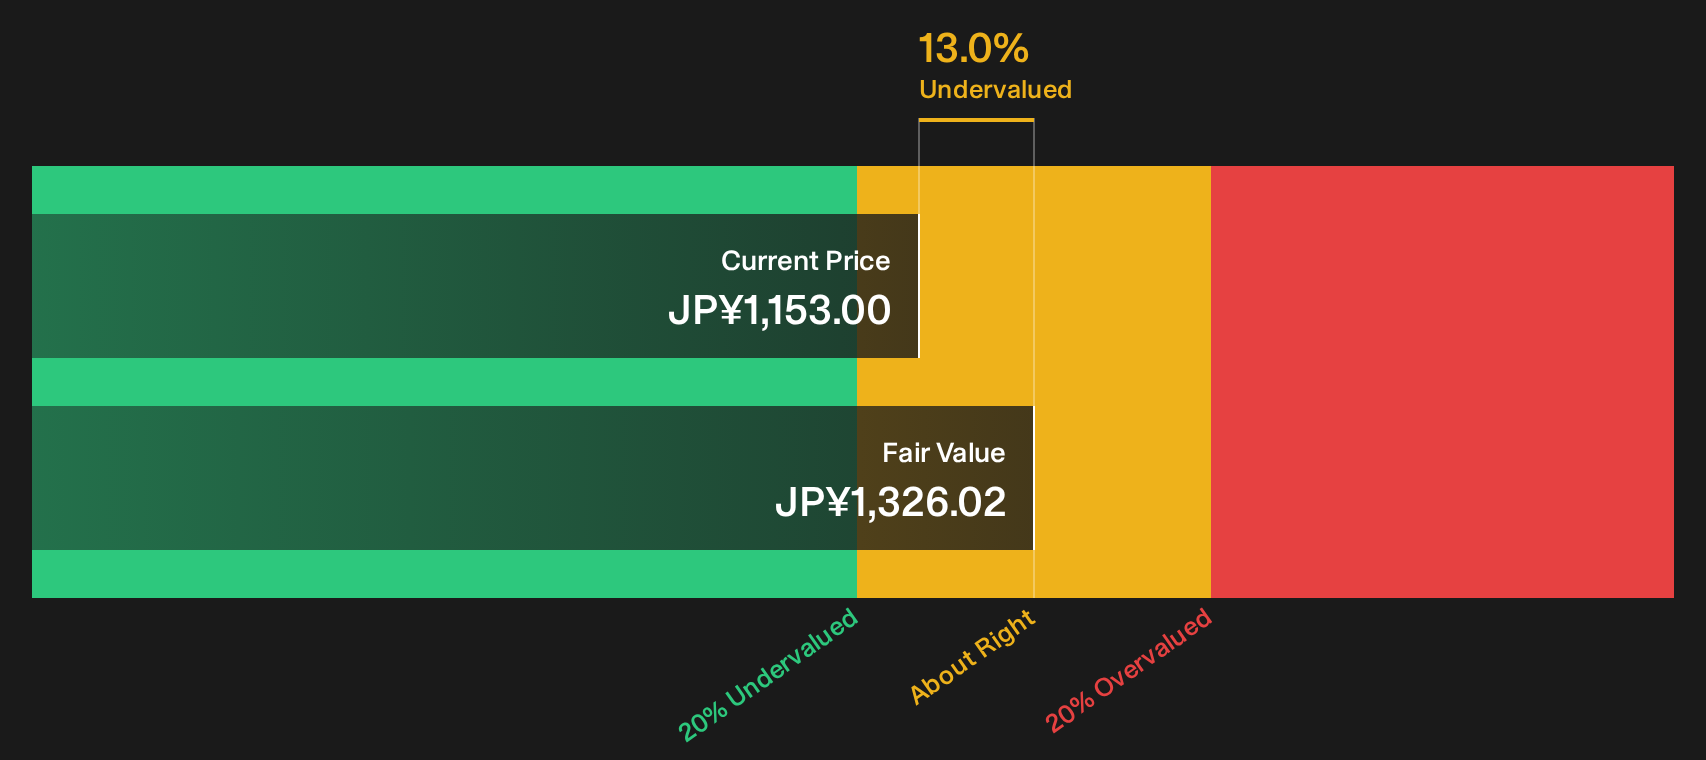
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Astroscale Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed about Astroscale Holdings after weighing its rich valuation against both the risks and rewards in the story so far? Act while the information is fresh. Pressure test the bullish and cautious arguments by reviewing the 2 key rewards and 1 important warning sign
Looking for more Astroscale Holdings style ideas?
If Astroscale Holdings has caught your attention, do not stop here. Fresh opportunities move quickly, and the next idea rarely waits for anyone.
- Target resilient balance sheets and steady fundamentals by running a focused search through our list of solid balance sheet and fundamentals (21 results).
- Hunt for quality businesses priced below what their fundamentals suggest by scanning the 17 high quality undervalued stocks.
- Prioritise stability and income potential by reviewing companies in the 14 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com