
Is National Bank Of Canada (TSX:NA) Undervalued Following Its Preferred Stock And Bond Issuance?
National Bank of Canada financing move puts preferred stock in focus
National Bank of Canada (TSX:NA) has launched a CAD 750 million variable rate preferred stock offering. This fresh capital raise sits alongside recent large bond issues and puts its broader funding mix on investors’ radar.
Recent funding activity lands as National Bank of Canada’s share price sits at CA$213.08, with the stock recording a 1-day share price return of 0.95% and a year-to-date share price return of 22.99%. The 1-year total shareholder return of 44.15% and very large 3-year and 5-year total shareholder returns above 150% hint that longer term momentum has been strong, even as the 30-day and 90-day share price returns have slipped. This suggests some investors are reassessing near term risk after a series of sizeable bond and preferred issuances.
Scan other bank stocks that combine active funding programs with solid balance sheets using our curated list of solid balance sheet and fundamentals (7 results) as a comparison point to National Bank of Canada’s latest moves.
National Bank of Canada now trades close to analyst targets yet still carries a sizeable intrinsic discount. Does that gap reflect caution around the latest funding wave, or an opportunity in plain sight?
Most Popular Narrative: 5% Undervalued
National Bank of Canada shares closed at CA$213.08 compared with a narrative fair value estimate of about CA$223.92, which frames the new preferred financing against a market that already sees some upside based on earnings and return assumptions.
Successful integration of Canadian Western Bank (CWB) and rapid realization of cost and funding synergies are progressing ahead of expectations, with revenue synergies yet to come. This positions the bank for accelerated revenue growth and improved net margins as integration milestones are completed over the next 18 months.
See why 60 investors see National Bank of Canada as 5% undervalued.
Result: Fair Value of CA$223.92 (UNDERVALUED)
Still, National Bank of Canada faces pressure from rising technology spending and ongoing net interest margin compression, which could challenge the upbeat earnings narrative that investors are leaning on.
Find out about the key risks to this National Bank of Canada narrative.
Another View on National Bank of Canada’s Valuation
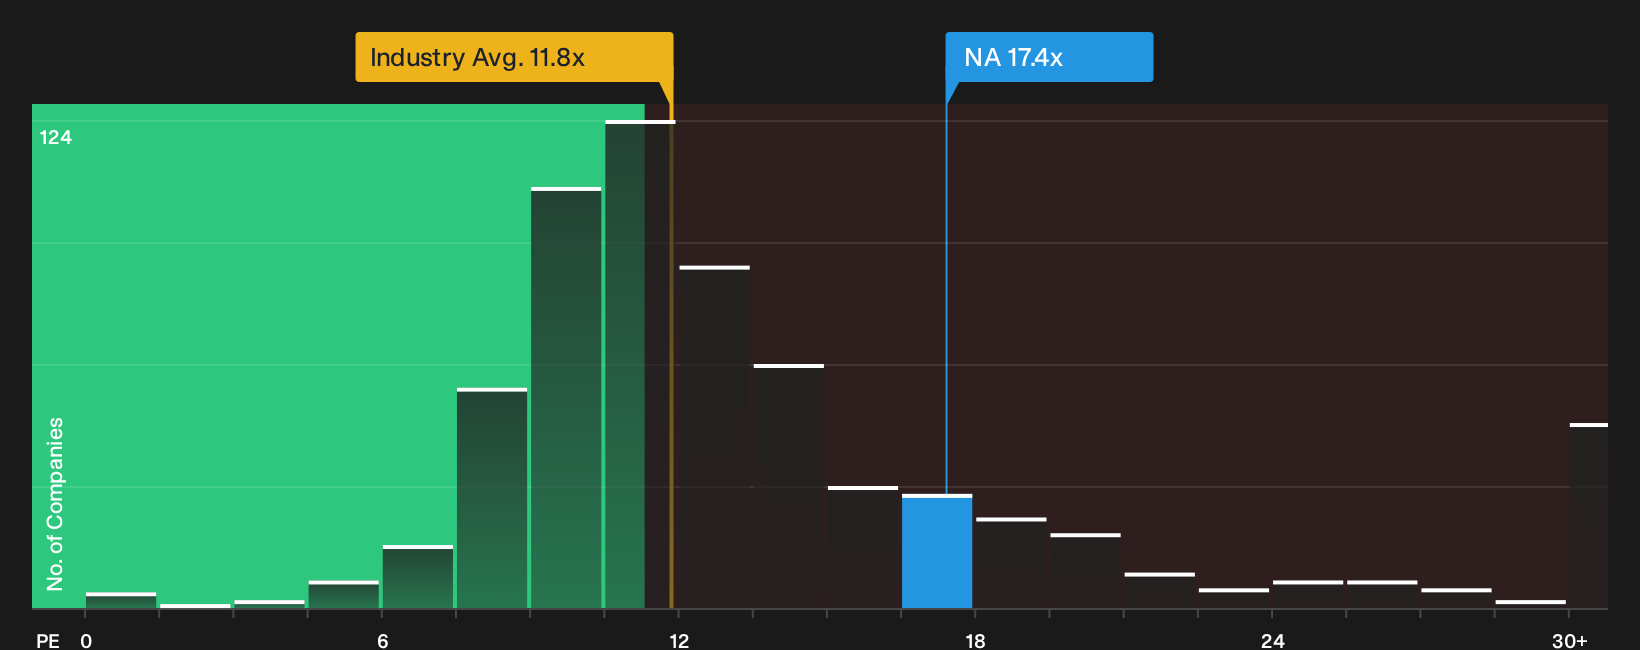
There is a different read on National Bank of Canada when looking at simple pricing metrics. The stock trades on a P/E of 17.4x compared with a fair ratio of 16.7x and the wider North American banks group around 11.8x. That points to a richer tag than both the fair ratio and the regional sector, which means more valuation risk if sentiment cools or earnings surprise on the downside.
Put differently, investors are already paying a premium versus many peers, even though the bank scores 3 out of 6 on the internal value checklist. The question is whether the funding moves, integration story and earnings profile justify that higher multiple, or whether there is less room for error than the discounted cash flow view implies.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on National Bank of Canada so far? If you want to move fast and build your own conviction, start by weighing the 4 key rewards and 1 important warning sign
Looking for more National Bank of Canada style investment ideas?
Do not stop at National Bank of Canada. The next opportunity might sit just outside your current watchlist, and you will only see it if you look.
- Target resilience by comparing banks like National Bank of Canada with companies screened for strong balance sheets and fundamentals through our list of solid balance sheet and fundamentals (7 results).
- Hunt for mispriced opportunities by scanning a curated pool of 4 high quality undervalued stocks before the crowd pays attention.
- Prioritise stability and peace of mind by reviewing a focused set of 8 resilient stocks with low risk scores that aim to keep downside in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com