
Is CBIZ (CBZ) Fully Valued As Its Earnings Outlook Improves?
Why CBIZ Is Back On Investors’ Radar
CBIZ (CBZ) has drawn fresh attention after Zacks highlighted the stock’s positive year-to-date performance and improving earnings outlook, pointing to stronger sentiment compared with the broader Business Services sector.
For anyone tracking CBIZ, that recognition raises an obvious question. Does the recent share performance and earnings backdrop still line up cleanly with the company’s underlying business and current valuation, or has sentiment moved ahead of the fundamentals?
Recent trading in CBIZ shares has been steady rather than dramatic, with the share price at $54.63. A strong 90-day share price return of 90.61% has supported a 7.54% year-to-date share price gain, while the 1-year total shareholder return of 1.58% and 5-year total shareholder return of 67.53% indicate momentum that has developed over a longer period, even if the most recent year has been more muted once dividends are included.
Scan beyond CBIZ and compare its recent momentum with a curated group of peers screened for quality and valuation in our 35 high quality undervalued stocks.
After a near doubling over 90 days and a share price that now sits just below the latest analyst target, CBIZ leaves you with a simple tension. Is the meaningful upside already used up, or does the current valuation still leave room to run based on its earnings and cash flow profile?
Most Popular CBIZ Narrative: 5.7% Overvalued
CBIZ currently trades at $54.63, compared with a widely followed fair value estimate of about $51.67 that is built on detailed cash flow and earnings assumptions. That gap is small in dollar terms but important if you care about whether the buyout premium and recurring income profile fully justify today’s price.
The Marcum acquisition has significantly expanded CBIZ's client base, increased scale, and strengthened capabilities in core tax, accounting, and advisory services. This has enabled the firm to leverage cross-selling, deepen client relationships, and improve its competitive position in target middle-market segments. This is expected to fuel higher future revenue growth and structural margin expansion as integration synergies are realized.
See why 10 investors see CBIZ as 6% overvalued.
Using an 8.6% discount rate, the prevailing narrative links that $51.67 fair value to a view that CBIZ can grow revenue at 4.3% a year, raise profit margins from 4.4% to 9.3%, and lift earnings from $122.1m to $291.0m by around 2029. It also assumes the stock would trade on an 11.8x P/E at that point, which is below the current 23.6x level and lower than the present 22.1x multiple for the wider US Professional Services group.
Analysts supporting this framework also factor in modest share count reduction of 0.61% a year, which can amplify earnings per share even if top line growth stays relatively steady. Those expectations sit alongside the view that a material share of CBIZ’s activity is recurring in nature, while recent one off items and integration costs have weighed on reported profitability in the short term.
Several risks sit on the other side of that fair value story. Pricing on recent work has been described as running 200 to 300 basis points below past norms, 28% of revenue is tied to more cyclical, nonrecurring projects, and leverage following the Marcum deal has increased interest costs and reduced flexibility at a time when technology change across professional services is accelerating.
For anyone watching the Grant Thornton Advisors buyout proposal at $55 per share and the planned separation of the Benefits and Insurance Services arm, that narrative fair value gives a reference point for how much of the offered premium is being attributed to CBIZ’s projected growth and margin profile versus its cash flow today.
Result: Fair Value of $51.67 (OVERVALUED)
Still, if pricing pressure proves sticky and nonrecurring work stays weak, CBIZ could see its earnings path and the thesis of a 5.7% overvaluation come under pressure.
Find out about the key risks to this CBIZ narrative.
Another View On CBIZ’s Valuation
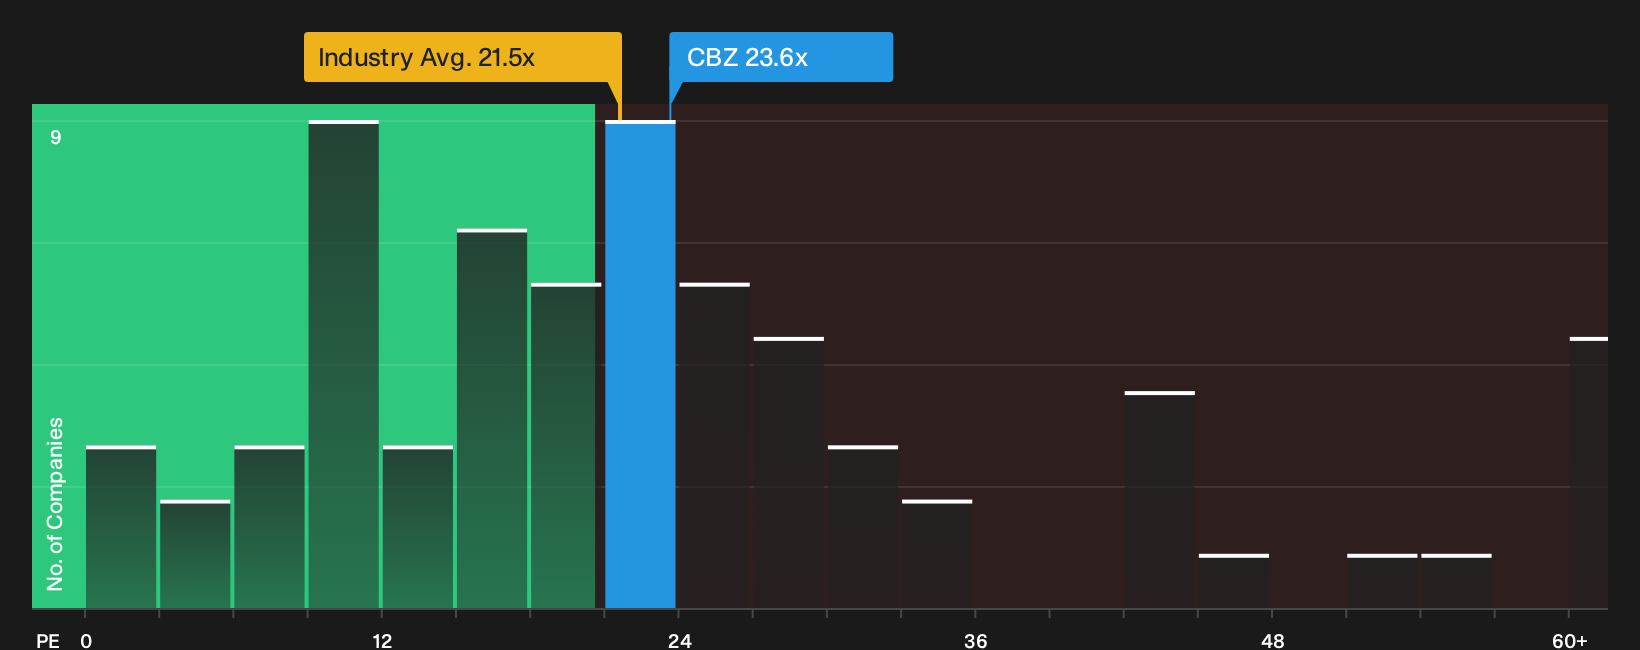
The earlier narrative framed CBIZ as about 5.7% overvalued relative to a $51.67 fair value. A different lens points elsewhere. On a P/E of 23.6x against a fair ratio of 26.7x, the stock screens as good value, even though it trades richer than both the US Professional Services average at 21.5x and direct peers at 22x. That gap cuts both ways. It can signal quality that justifies a premium, or it can narrow quickly if sentiment cools. Which side of that tradeoff feels more credible to you?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on CBIZ so far, with clear positives sitting alongside flagged concerns, make this a moment to move fast and test the numbers yourself. To see both sides laid out in one place, review the 3 key rewards and 2 important warning signs
Looking For More Investment Ideas Beyond CBIZ?
If you stop at CBIZ, you risk missing other opportunities that fit your risk, income, and quality goals. Broaden your watchlist with a few focused screens.
- Target potential mispricing by scanning for quality businesses trading below intrinsic value with the 35 high quality undervalued stocks.
- Prioritise resilience by filtering for companies with strong finances and healthy fundamentals through the list of solid balance sheet and fundamentals (23 results).
- Hunt for under-the-radar opportunities that others might be ignoring using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com