
How BoJ Rate Hike And Weak Yen Could Shape Advantest Stock
- Advantest is caught in an unusual macro mix as the Bank of Japan lifts rates to 1.25% while the yen remains weak against the dollar, creating a complex backdrop for its export driven semiconductor testing operations.
- This rare pairing of higher domestic borrowing costs with a still soft currency puts more focus on how Advantest balances pricing, capacity plans and cost control across its global footprint.
- We will now look at how Advantest's investment narrative interacts with tighter Japanese policy while the yen still trades soft.
Scan how other export oriented Japanese stocks are positioned in this same rate and currency mix with a curated set of 75 high quality undiscovered gems for fresh ideas beyond Advantest.
Advantest Investment Narrative Recap
To own Advantest, you need to believe that demand for advanced chip testing tied to AI, high performance computing and leading edge nodes can stay healthy enough to absorb a planned 60 to 70% capacity ramp by the end of 2026. The recent move by the Bank of Japan to a 1.25% rate with a still weak yen changes funding costs and currency swings, but does not rewrite that core thesis.
The nearer term swing factor remains how customers work through the flagged digestion period in the second half of FY 2025 after earlier pull ins. The biggest operational risk is that this pause collides with higher fixed costs from expansion and sharper FX moves, which could pressure margins and make already volatile earnings and share price moves more pronounced.
Recent commentary around a record Q1 underscores how dependent Advantest is on timing quirks like demand pull ins, a favorable product mix and the absence of one off losses. Management has already said those conditions are unlikely to repeat consistently. That matters more to the story than a single quarter of headline strength, especially once higher Japanese rates filter into borrowing costs.
Set against that, the same disclosures highlight capacity expansion plans into 2026 that are aimed at AI heavy and advanced node testers, along with a push into areas like system level test and services. For investors, the operational question is whether that larger footprint can be kept busy as customers move through digestion phases, and how a weak yen with tighter domestic policy shapes the eventual pay off from those projects.
Advantest's current analyst script points to revenues of ¥2.3477b and earnings of ¥838.0b by 2029, based on an assumed 24.0% yearly top line expansion and an earnings increase of about ¥378.0b from ¥460.0b today.
Uncover how Advantest's fair value indicates a 20% potential upside to its current price, which could narrow quickly as expectations adjust.
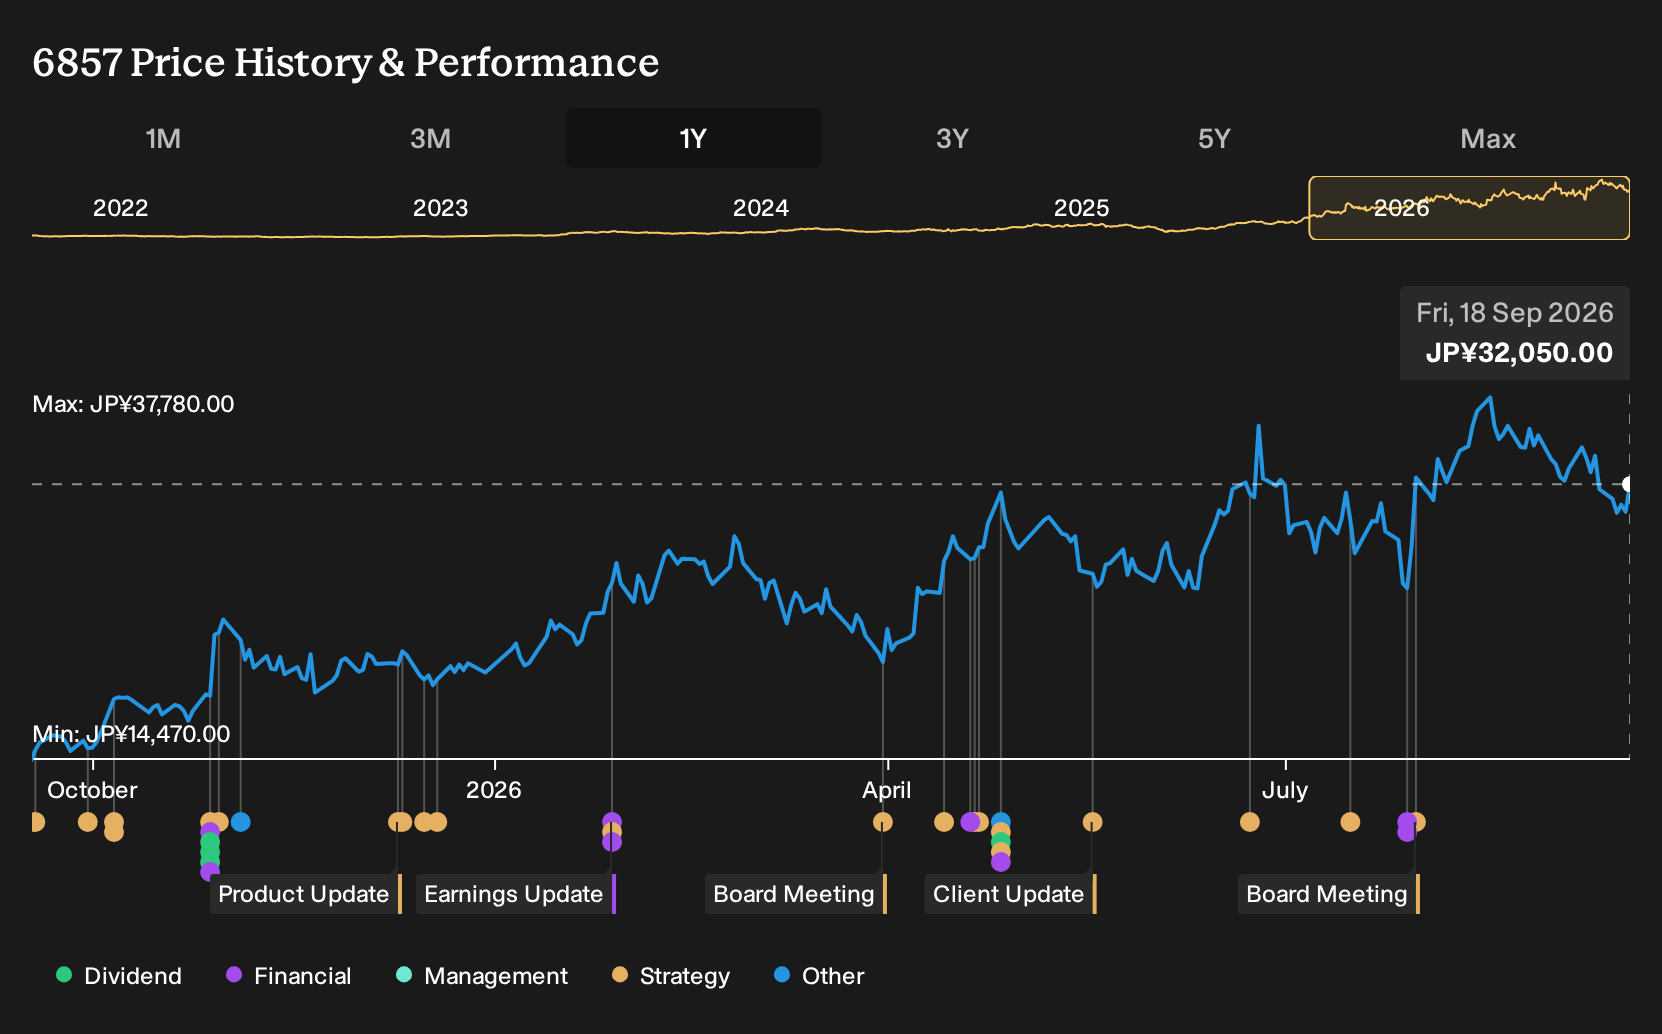
Exploring Other Perspectives
One alternate take treats currency risk, not AI demand, as the real swing factor for Advantest in light of higher Japanese rates alongside a still soft yen. The most optimistic analysts were already penciling in ¥3,609.0b of revenue and ¥1,510.4b of earnings by 2029. Those upbeat forecasts came before this rate and FX twist, so changes in views across the analyst spectrum may follow.
Explore 2 other Advantest fair value estimates, including one that suggests up to 31% potential price appreciation from the current level.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Advantest research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Advantest. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Advantest's overall financial health at a glance.
Looking for more investment ideas beyond Advantest?
Once you have formed a view on Advantest, it can help to compare that thesis with other companies that share similar qualities or very different risk profiles. The Simply Wall St Screener gives you a fast way to scan for stocks that fit the kind of portfolio you want to build next.
- If you want potential value with quality fundamentals, start by reviewing a curated set of 17 high quality undervalued stocks that combine stronger balance sheets with attractive pricing signals.
- For income focused investors, consider stocks that target higher yields and more resilient payouts by checking the 14 dividend fortresses. These may complement a growth oriented position like Advantest.
- If capital protection matters most, narrow your search to companies with steadier profiles using the 21 resilient stocks with low risk scores. You can then compare how their risk scores stack up against what you see in Advantest.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com