
DuPont De Nemours (DD) Could Be 25% Undervalued Following Its Tyvek Launch
DuPont de Nemours (DD) has expanded its Tyvek franchise with the global launch of Tyvek with Renewable Attribution for consumer and industrial uses, putting lower carbon material sourcing in focus for investors.
Recent trading shows mixed momentum for DuPont de Nemours. The share price is up 1.6% over the past week but down 6.7% over 30 days and 10.8% over 90 days, while the 1-year total shareholder return of 34.0% and 5-year total shareholder return of 65.9% indicate a much stronger longer-term experience for investors.
Scan beyond DuPont de Nemours and compare this lower carbon materials story with other hand picked industrial players that are shaping the next cycle through list of solid balance sheet and fundamentals (23 results).
That mix of a short-term pullback and strong multi-year gains leaves DuPont de Nemours at an interesting crossroads. Are you looking at a business reset in progress, or a swing in mood around the stock that valuation now needs to sort out?
Most Popular Narrative: 25% Undervalued
According to the latest numbers, the Simply Wall St narrative estimates DuPont de Nemours has a fair value of about $172 per share versus a last close of $129.01. This frames the current pullback as a valuation gap that depends on how credible the long term growth story is.
DuPont's accelerated growth in Electronics, particularly from AI-driven applications, advanced packaging, and high-performance computing, positions the company to capture outsized revenue expansion as node migrations and broader electronics market recovery unfold through 2025 and beyond.
See why 32 investors see DuPont de Nemours as 25% undervalued.
Result: Fair Value of $172.07 (UNDERVALUED)
Still, DuPont de Nemours faces live swing factors, including ongoing PFAS litigation cash outflows and potential revenue or margin pressure related to its concentrated China electronics exposure.
Find out about the key risks to this DuPont de Nemours narrative.
Another View: DuPont de Nemours Looks Expensive On Earnings
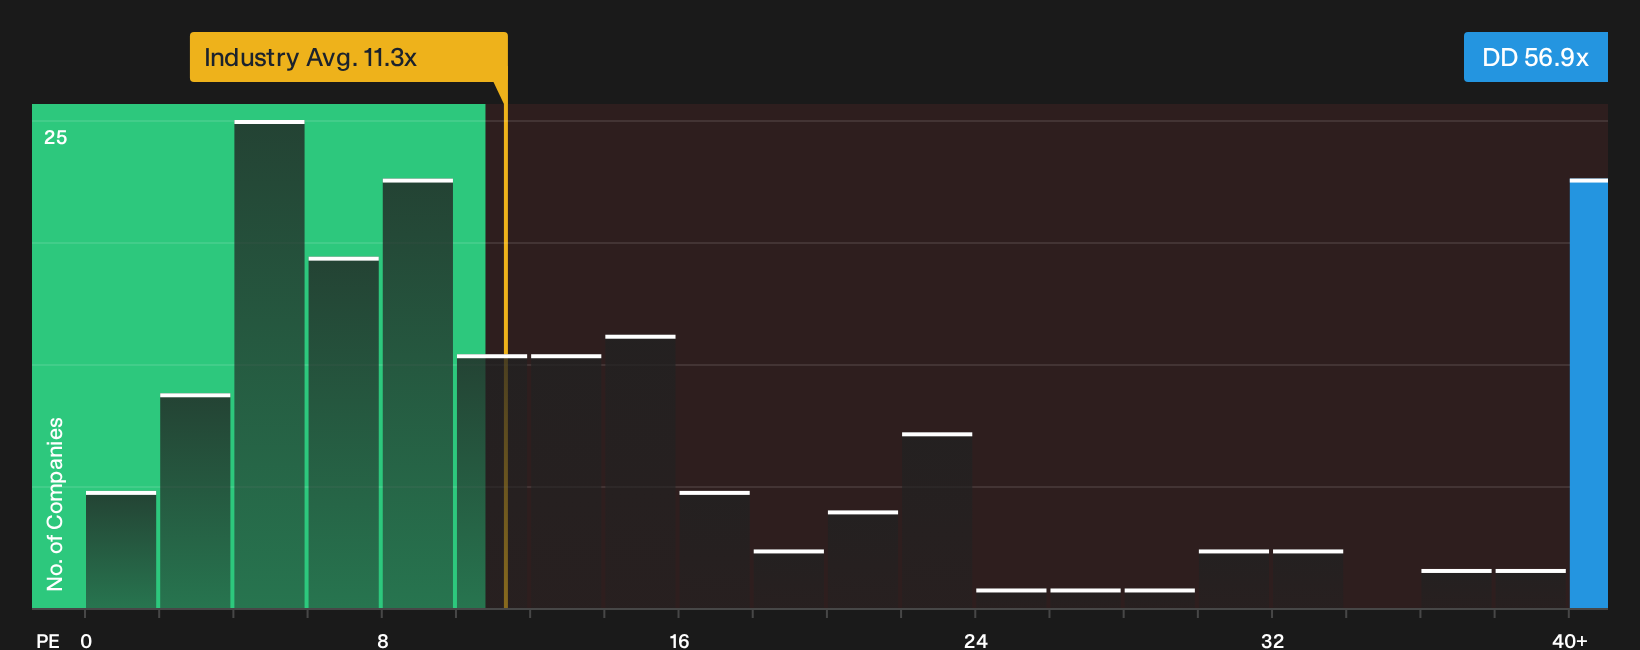
Analyst models and the SWS narrative point to DuPont de Nemours trading below estimated fair value, yet the current P/E of 56.9x tells a very different story. That multiple is far above the global industrials average of 11.3x, the peer average of 29.4x, and even the 37x fair ratio the market could move towards.
If earnings or sentiment falter, that premium could unwind faster than a spreadsheet suggests. Are you comfortable paying this kind of earnings mark up for DuPont de Nemours, or does this risk tilt the scales for you?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around DuPont de Nemours can pull you in opposite directions, so move quickly, stress test the thesis against your own risk tolerance, and weigh the 4 key rewards and 2 important warning signs
Looking for more DuPont de Nemours sized ideas?
If DuPont de Nemours has your attention, do not stop here. Use the Simply Wall St Screener to spot fresh setups before the crowd catches on.
- Target resilience first and filter for companies with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (23 results).
- Shift your focus to value and scan for potential mispriced opportunities using the 35 high quality undervalued stocks.
- Stack potential income on top of capital growth and search for high-yield payers with the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com