
Did Outdoor Gear Demand Just Shift Columbia Sportswear's (COLM) Investment Narrative?
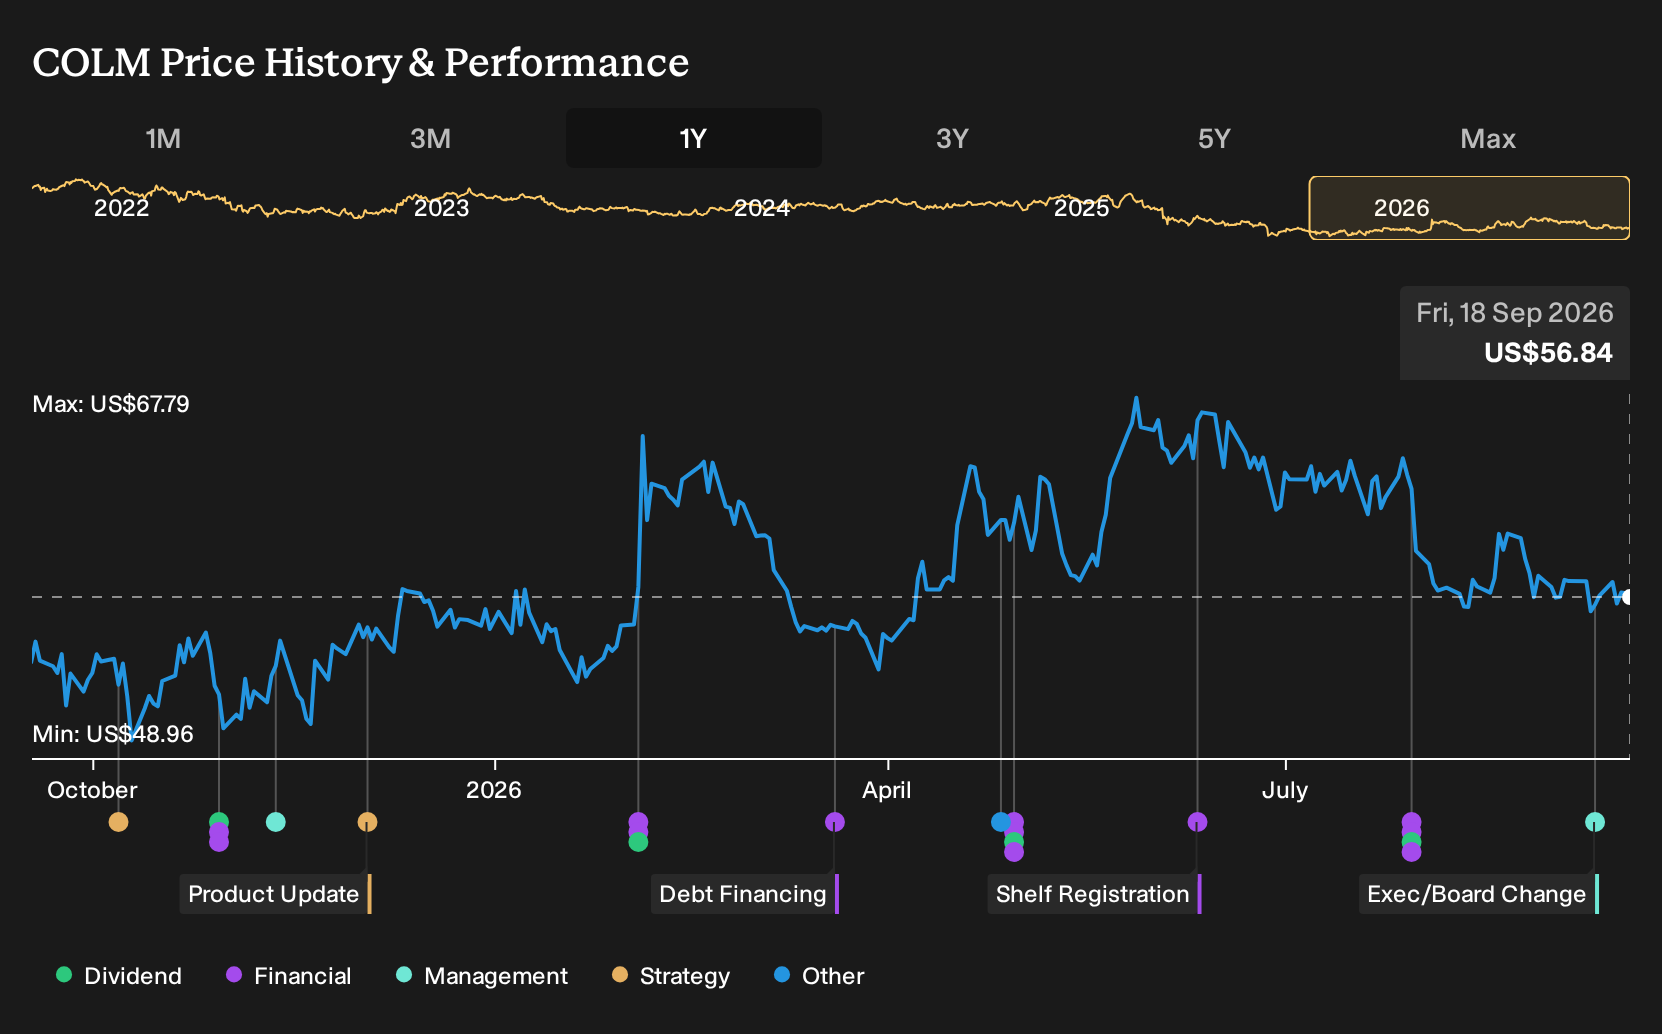
- Columbia Sportswear reshuffled leadership at its Mountain Hardwear unit, appointing Peter Rauch as President and moving Troy Sicotte to Global Vice President, Sales. Both executives will step into their new positions on September 28, 2026, to support brand execution and marketplace relationships.
- The leadership shift at Mountain Hardwear lands as the wider outdoor products market is projected to reach US$253.9b by 2035. This highlights how Columbia Sportswear is positioning management to address demand for high performance, sustainable gear.
- We will look at how Columbia Sportswear's investment narrative aligns with this leadership change at Mountain Hardwear and outdoor demand.
Scan how Columbia Sportswear's leadership reshuffle compares with other outdoor-focused businesses preparing for rising gear demand by reviewing the hand picked list of solid balance sheet and fundamentals (23 results).
Columbia Sportswear Investment Narrative Recap
For you to back Columbia Sportswear, you need to believe it can convert global interest in outdoor recreation into steady demand across apparel, footwear and equipment while keeping costs in check. The Mountain Hardwear leadership reshuffle looks operational rather than transformational, so it does not materially change the near term picture on its own.
The key near term swing factor remains execution on product and channel strategy as consumer spending stays mixed and tariffs and input costs pressure margins. The main risk is that earnings, already expected by analysts to decline slightly on average over the next three years, remain under strain if international strength or emerging brands underperform.
One linked thread is the focus on emerging brands such as Mountain Hardwear as a way to diversify beyond the core Columbia label. Management commentary points to these smaller banners as important for spreading revenue across categories and regions, which matters if cold weather outerwear demand softens or U.S. performance lags.
The move that places Peter Rauch at the head of Mountain Hardwear and shifts Troy Sicotte into the global sales role sits directly in that context. Your attention probably belongs on whether this pairing can tighten product positioning and wholesale and DTC execution in a market where digital competition is intense and tariff and climate related risks hang over margins and inventory planning.
Columbia Sportswear's narrative projects US$3.7b revenue and US$211.3 million earnings by 2029. This assumes 3.0% yearly revenue growth and a US$5.3 million earnings increase from US$206.0 million today.
Uncover why Columbia Sportswear's fair value indicates a 23% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
Tariffs sit at the center of the most pessimistic view. The lowest Columbia Sportswear analysts were already assuming only 2.4% annual revenue growth and earnings of US$193.5 million by 2029, compared with US$169.3 million today. You can read those forecasts as a warning that leadership shifts, such as Mountain Hardwear's, might eventually reshape these expectations in either direction.
Explore 2 other Columbia Sportswear fair value estimates, including one that suggests it could be worth just $69.83!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Columbia Sportswear research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Columbia Sportswear. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Columbia Sportswear's overall financial health at a glance.
Looking For More Columbia Sportswear Style Ideas?
If the Columbia Sportswear story has you thinking about portfolio gaps, it can help to scan other businesses with different strengths and risk profiles using the Simply Wall St Screener.
- If stability is near the top of your checklist, consider reviewing a 30 resilient stocks with low risk scores that have been filtered for resilience and lower risk scores.
- If you want income on top of potential price moves, check out a set of 7 dividend fortresses that offer higher yields while still focusing on durability.
- If you prefer potential mispricing opportunities, broaden your watchlist with a curated 16 high quality undiscovered gems that combine strong fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com