
3 Undervalued Stocks To Watch In September 2026
The Federal Reserve just raised interest rates again to tackle inflation, which puts extra pressure on weaker businesses that rely heavily on cheap debt. Stronger companies with healthy cash flows and cleaner balance sheets look more appealing when borrowing costs stay high. That is exactly where this group of quietly priced opportunities comes in. This article highlights three stocks from that high quality, undervalued pool that are worth putting on your watchlist.
The stocks covered below are only a small sample from this high quality undervalued group, and the wider screen surfaced 32 more companies with similar balance sheet strength and cash flow stories that are not included here. To identify your own highest conviction ideas from that broader set, head straight into the High Quality Undervalued Stocks screener
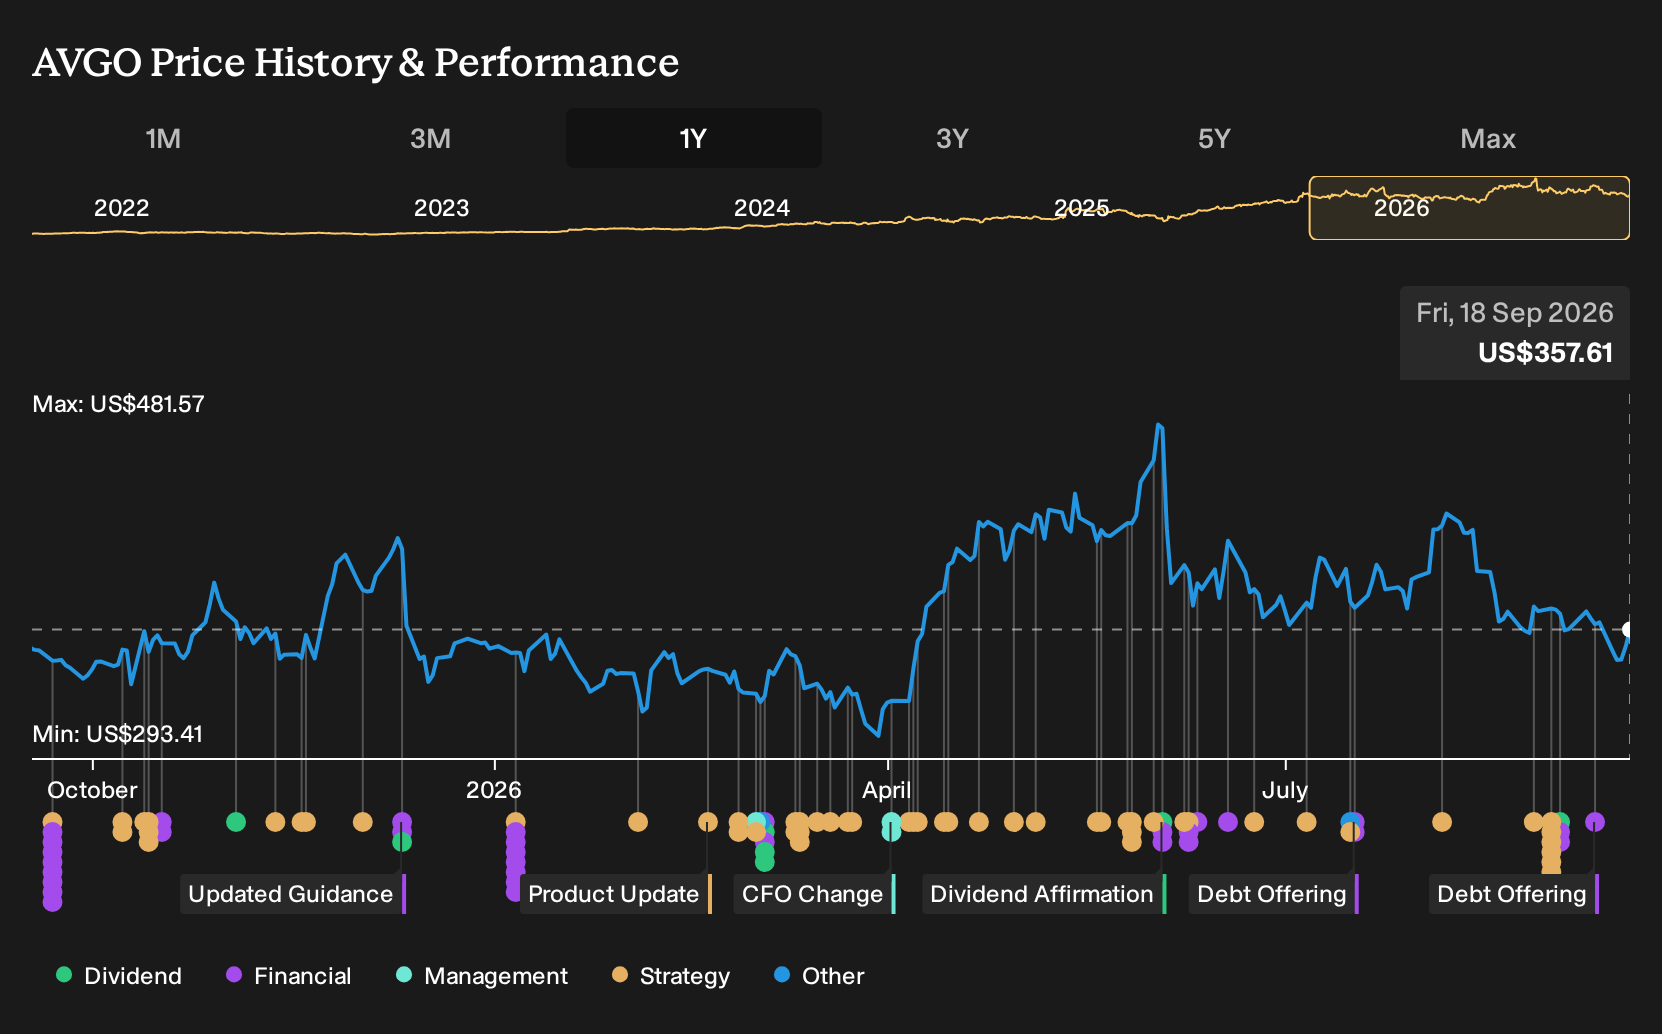
Broadcom (AVGO)
Overview: Broadcom is a digital infrastructure company that supplies semiconductor hardware and VMware-based software that keep modern data centers, networks, and AI systems running.
Operations: Broadcom generates about US$59.4b from Semiconductor Solutions and US$29.7b from Infrastructure Software, reflecting a balanced hardware and software mix.
Market Cap: US$1.7t
For the High Quality Undervalued Stocks theme, Broadcom matters because its AI-ready networking chips and VMware software sit inside many data-center and enterprise setups that need reliable cash generation and resilient balance sheets behind them.
"Broadcom is generating substantial free cash flow, expanding its custom silicon business, strengthening its position in networking, and integrating software assets that further diversify earnings."
What happens to that cash engine if a single unseen pressure on hyperscaler AI spending or financing terms meaningfully shifts?
If that hidden stress test is on your mind, read the full narrative for Broadcom to see how Broadcom’s cash engine responds when AI spending and debt costs decouple.
Oracle (ORCL)
Overview: Oracle is a global software and cloud provider that runs critical databases, business applications, and Oracle Cloud services for enterprises.
Operations: Oracle generates about US$62.8b from Cloud and software, US$5.8b from Services, and US$3.2b from Hardware.
Market Cap: US$446.3b
Oracle matters for the High Quality Undervalued Stocks theme because its Oracle Cloud SaaS and Oracle Cloud Infrastructure units convert long-term customer contracts into recurring cash flows that support both balance sheet resilience and the potential for a re-rating if that cloud uptake continues.
"In 2024, OpenAI made headlines by expanding its cloud footprint to include Oracle Cloud Infrastructure (OCI), a move described as strategic, reflecting the growing demand for massive compute power and the need for multi-cloud resilience. This partnership positioned OCI as a key extension of the Microsoft Azure AI platform."
What happens to Oracle’s margins and cash generation profile if a single assumption about AI-driven cloud usage or pricing power meaningfully shifts?
That single shift can change the whole cash story, so read the full narrative for Oracle to see whether Oracle’s AI cloud momentum is accelerating or quietly stalling.

Super Micro Computer (SMCI)
Overview: Super Micro Computer designs and builds high performance AI and data center servers, storage systems, and rack scale solutions for global customers.
Operations: Super Micro Computer generates about US$39.1b from high performance server solutions, with roughly US$27.7b coming from the United States and the rest from international markets.
Market Cap: US$25.7b
Super Micro Computer matters for this High Quality Undervalued Stocks screen because its AI focused server platforms turn rising compute demand into a tangible hardware and services pipeline that can support cash generation and balance sheet strength if current AI build out plans hold.
"The accelerating global adoption of AI and analytics continues to drive demand for high-performance, scalable server and data center solutions, positioning Super Micro for strong multi-year revenue growth as enterprises and nations build out AI infrastructure, directly supporting projected revenue outperformance."
What happens to that AI server story if a single unseen pressure on pricing power or order conversion quietly shifts the margin profile?
If that margin risk worries you, read the full narrative for Super Micro Computer to see whether Super Micro Computer’s accelerating AI server demand is masking fragility or building a stronger core.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities do not stay quiet for long. Screens are shifting, momentum builds, and the best entries can be captured quickly. Review these curated ideas while they are timely and decide how they may fit your approach.
- Explore early potential in smaller, fast-moving companies by reviewing the 9 elite penny stocks with strong financials before their stories move from under the radar to front-page attention.
- Monitor the evolving landscape of computing by tracking the 25 quantum computing stocks while expectations, pricing, and real-world adoption are still developing.
- Include exposure to harder assets on your watchlist by checking the 36 elite gold producer stocks as sentiment shifts around these producers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com