
Is Crocs (CROX) Undervalued, Or Are Cash Flows Already Priced In?
Crocs has delivered a strong share price run over the past year, and that puts a spotlight on a simple question for you as an investor. Is the current US$122.24 price tag adequately backed by the cash the business can generate over time, or has sentiment moved ahead of its cash flows?
- The stock is up 52.2% over the past year, which raises the stakes on whether recent enthusiasm is grounded in the company’s underlying cash generation.
- The business model converts a significant portion of its earnings into cash, which can support valuation if that conversion remains consistent and capital needs stay contained.
- Prefer to judge Crocs on earnings? See what Crocs's 9.9x P/E says about the price.
For investors, the debate is whether Crocs' current share price is properly supported by the intrinsic value suggested by its cash flows.
If you want more context around Crocs and cash-flow-driven pricing, comparing it with companies in the 35 high quality undervalued stocks can give you a clearer sense of what value looks like in practice.
Is Crocs a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash Crocs can return to shareholders over time. On the latest numbers, the business produced about $688.7m of free cash flow over the last twelve months, which is sizeable for a company with a share price of $122.24.
Analysts feeding into this DCF expect Crocs' free cash flow to stay positive and broadly growing over the next decade rather than swinging between big surpluses and cash shortfalls. The projections point to a pattern of steady, mid hundreds of millions of dollars in annual free cash generation, which assumes the footwear maker keeps converting earnings to cash at a similar rate and does not need very heavy reinvestment to sustain the brand. Based on those cash flow forecasts, the DCF model currently puts Crocs' estimated intrinsic value substantially above the current share price. Find out what Crocs could be worth using our Discounted Cash Flow (DCF) estimate.
The Crocs Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Crocs pick up where the cash flow puzzle leaves off. They explain which assumptions on Crocs' growth, profitability, and earnings path would need to hold for the valuation to appear meaningfully higher or lower than today’s share price. Each narrative also links a specific fair value to a clear story about future catalysts and risks so you can track over time which version of events is actually unfolding.
Community views on Crocs are split between those who see a long runway left in the story and those who think expectations already look demanding.
Bull case: 12% undervalued
"The company's accelerating direct-to-consumer (DTC) strategy expanding owned retail and digital channels is enabling Crocs to maintain higher pricing and capture higher-margin sales..."
Discover why this Narrative puts Crocs at 12% undervalued.
Bear case: 29% overvalued
"The company's persistent overreliance on its signature clogs and lack of substantial diversification beyond core silhouettes makes Crocs vulnerable to sharp demand drops if clogs fall out of favor..."
Explore why this Narrative puts Crocs at 29% overvalued.
One more Crocs factor to check before making a move
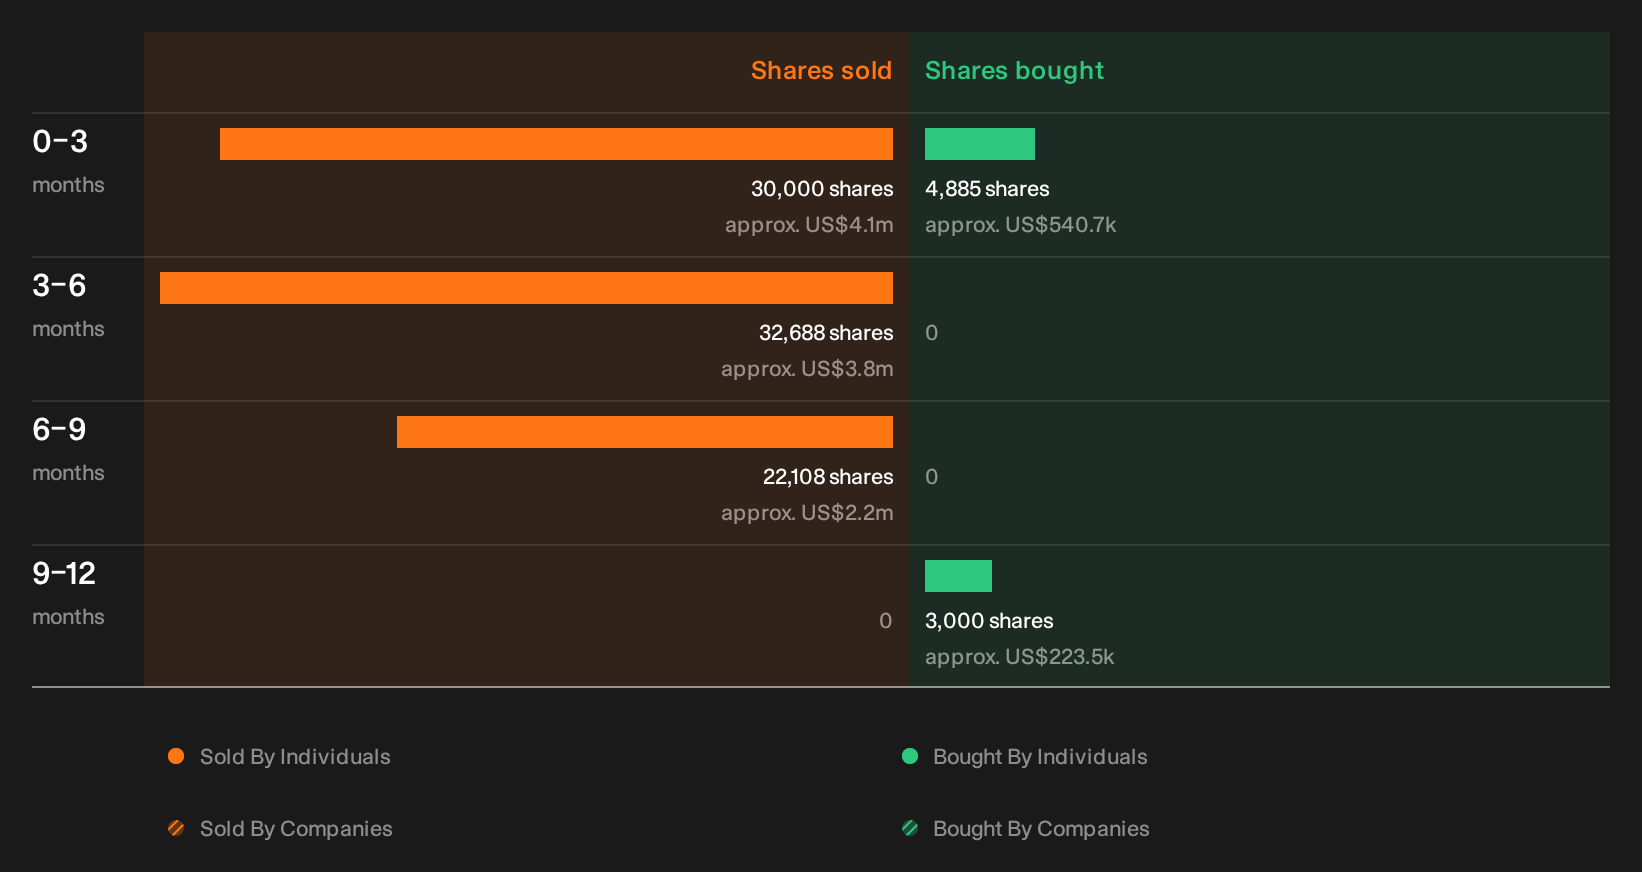
Before acting on any view of Crocs, it is worth knowing that recent trades from people inside the business have been picked up by our checks, and the who, how much and why are still for you to inspect. See the recent insider selling flagged for Crocs.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com