
SL Green Realty (SLG), What Is Behind Its Latest Update?
SL Green Realty (SLG) just paired strong Manhattan leasing activity with fresh cash returns, as the board declared quarterly dividends on both its common and Series I preferred shares.
Despite the new leasing wins and dividend declarations, SL Green Realty shares have eased in the short term, with a 1 month share price return down 9.35%, while the year to date share price return is up 10.90% and the 3 year total shareholder return sits at 65.64%. This suggests that longer term momentum has been stronger than the recent pullback.
Scan beyond SL Green Realty and size up other real estate players that are showing resilient cash flows and valuation support using our hand picked 35 high quality undervalued stocks.
Bulls point to SL Green Realty's richer leases and DCF upside, while bears focus on office demand risks after the recent pullback. Which side do the current cash flows and valuation math lean toward next?
Most Popular Narrative: 11% Undervalued
SL Green Realty closed at $52.08, while the most followed fair value narrative pegs the stock nearer to $58.74, creating a gap that bullish and cautious investors are reading very differently.
Value add developments and transformative projects (such as One Vanderbilt and the potential Caesars Palace Times Square casino) may unlock new high margin revenue streams, increase portfolio valuation, and expand SL Green's income base in the medium to long term.
See why 23 investors see SL Green Realty as 11% undervalued.
Result: Fair Value of $58.74 (UNDERVALUED)
Still, high interest costs and uncertain asset sales pricing could pressure SL Green Realty's earnings path and challenge the optimistic fair value narrative.
Find out about the key risks to this SL Green Realty narrative.
Another View on SL Green Realty Valuation
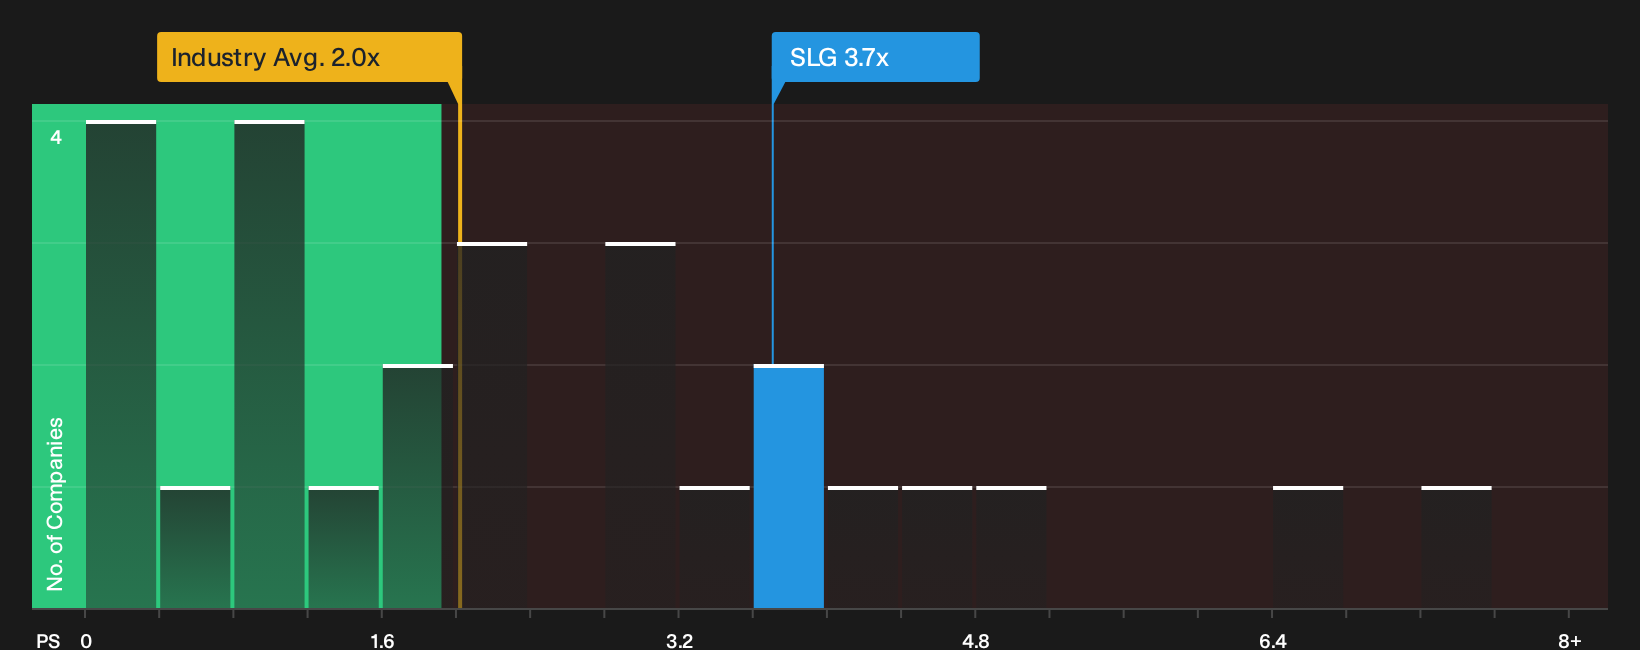
The first narrative leans on analyst targets and future earnings assumptions to argue that SL Green Realty looks about 11% undervalued at $52.08. A different lens tells a more cautious story. On a P/S of 3.7x, the stock trades above the US Office REITs industry at 2x and above its own fair ratio of 2.6x, which points to valuation risk if sentiment cools or revenue weakens further.
Investors comparing these mixed signals may want to see how the numbers stack up when the focus shifts back to what the SWS DCF model says about SL Green Realty, and how that approach arrives at its view of fair value relative to today’s price. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around SL Green Realty can easily pull views in opposite directions, so move quickly, review the full data set, and weigh both the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond SL Green Realty?
SL Green Realty might be front of mind today, but your next strong opportunity could be sitting elsewhere, quietly lining up better risk and reward trade offs.
- Target robust cash returns with companies that focus on reliable payouts by reviewing a curated set of 7 dividend fortresses.
- Hunt for quality businesses that the market prices cautiously by scanning our focused group of 30 resilient stocks with low risk scores.
- Spot future leaders before the crowd by checking a carefully selected 16 high quality undiscovered gems
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com