
Is J. M. Smucker (SJM) Undervalued After Its Rebound Despite Weak Unit Demand?
Weak unit demand and a projected sales decline at J. M. Smucker (SJM) have pulled fresh attention to the stock as investors reassess a forward P/E of 12.2x in light of below average returns on capital.
Despite weak unit trends, J. M. Smucker’s recent share price performance has been resilient, with a 90 day share price return of 14.7% and a year to date share price gain of 27.24% up to the latest close of US$122.95. The 1 year total shareholder return of 17.68% suggests momentum has improved in the short term after more modest gains over three and five years.
Compare J. M. Smucker’s setup with a curated group of consumer-facing businesses by scanning the 35 high quality undervalued stocks that currently combine compressed valuations with stronger fundamentals.
J. M. Smucker still looks like a solid packaged foods business, yet the share price has just sprinted ahead while unit demand and returns on capital lag. Is that recent rebound offering value or asking too much?
Most Popular Narrative: 13% Undervalued
Against a last close of $122.95, the most followed narrative on J. M. Smucker pegs fair value at about $141.44, framing the recent rebound as still leaving a valuation gap if the profit story plays out.
Increased free cash flow generation (with a raised outlook for FY26 and ongoing annual benefits) provides resources to de-leverage, reinvest, or support strategic brand-building and automation initiatives, strengthening earnings quality and balance sheet flexibility over the long term. Ongoing growth in e-commerce, convenience, and direct-to-customer channels, supported by a dedicated sales force, expands distribution reach and enables sharper, data-driven marketing, providing further opportunities to capture market share and drive future sales growth.
See why 15 investors see J. M. Smucker as 13% undervalued.
Result: Fair Value of $141.44 (UNDERVALUED)
Still, the narrative can break if coffee commodity costs and tariffs squeeze margins harder than expected, or if Hostess integration issues weigh on profit quality.
Find out about the key risks to this J. M. Smucker narrative.
Another View on J. M. Smucker’s Valuation
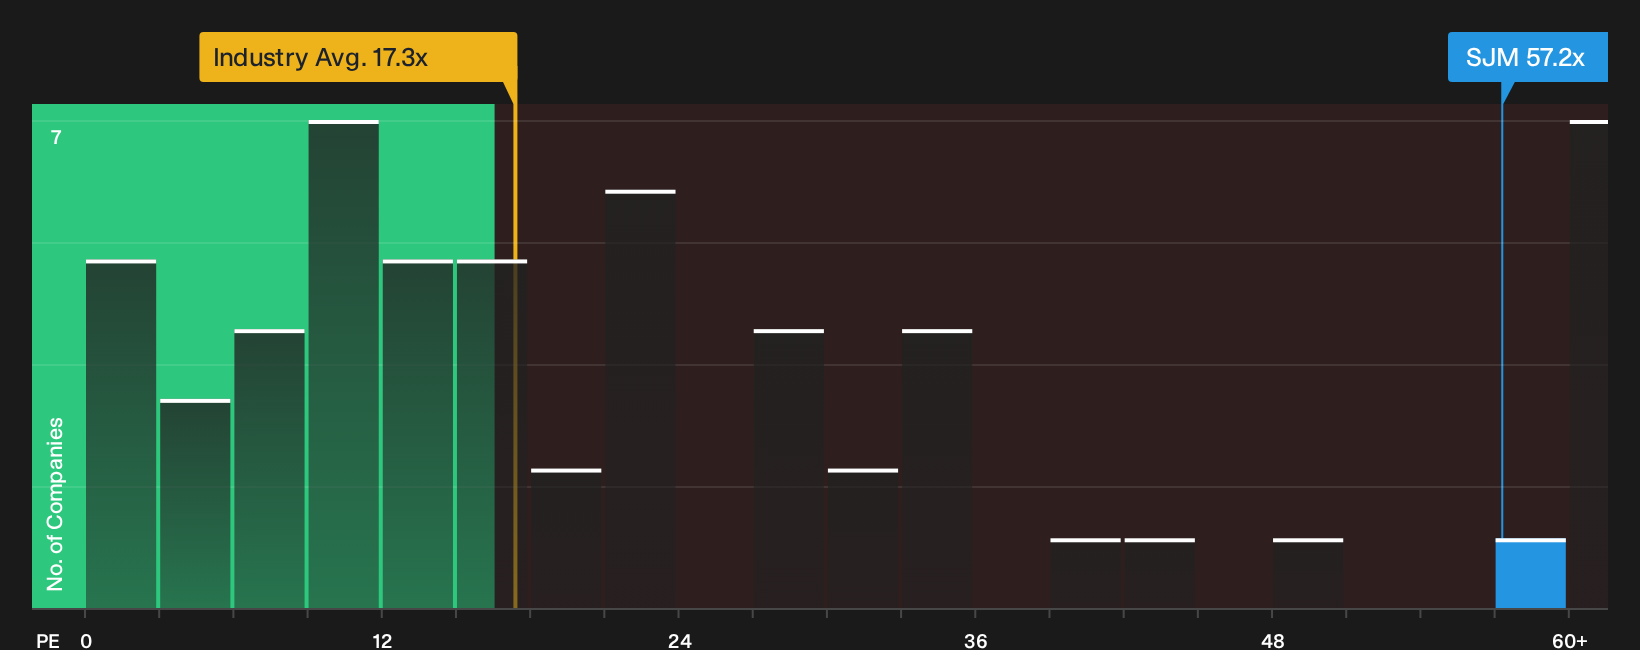
That 13% upside to fair value hinges on earnings forecasts and target P/E assumptions. On today’s numbers though, J. M. Smucker trades on a P/E of 57.2x compared with 17.3x for the wider US Food group, 21.3x for peers, and a fair ratio of 25.7x.
This gap points to a rich valuation on current earnings, which can leave less room if profit delivery or margin recovery slip. The question for investors is whether future earnings growth justifies paying more than double the fair ratio today.
For a closer look at how this compares with earnings based valuation work, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around J. M. Smucker’s valuation and business momentum tend to trigger strong opinions, so move quickly, check the underlying data, and shape your own stance using the 3 key rewards and 4 important warning signs.
Looking for more ideas beyond J. M. Smucker?
If J. M. Smucker has your attention, do not stop there. Broader idea hunting can sharpen your portfolio and reveal opportunities you would otherwise miss.
- Target stability first by scanning a list of solid balance sheet and fundamentals (23 results) that can help you focus on financially healthier businesses when markets feel unpredictable.
- Hunt for mispriced quality using the 16 high quality undiscovered gems so you are early to strong fundamentals before wider attention arrives.
- Prioritize resilience with the 30 resilient stocks with low risk scores if you want candidates with lower overall risk scores supporting a steadier sleep at night.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com