
Is Wingstop (WING) Cheap On Its Loyalty Push And Lemon Pepper Launch?
Wingstop (WING) recently leaned into game day habits with a limited time Lemon Pepper Trio and a members only Wing Pass season ticket, giving investors a fresh product and loyalty angle to assess.
That game day push comes at a tricky time for Wingstop, with the share price at US$104.08 and the 90 day share price return down 33.6% and the year to date share price return down 59.48%, while the 1 year total shareholder return has declined 58.62%. This points to fading momentum even as recent product launches and a mixed set of broker views keep the debate alive over whether recent weakness reflects growth worries or a reassessment of risk.
Compare Wingstop's current setup with a curated group of resilient operators by scanning the 30 resilient stocks with low risk scores that have kept risk scores in check while sentiment swings around them.
Wingstop now trades well below both analyst targets and one intrinsic value estimate, yet the recent share-price slump hints at persistent doubt. Is this a discount on mispriced fear, or a fair warning label on the valuation story ahead?
Most Popular Narrative: 50% Undervalued
Wingstop's most followed valuation storyline pegs fair value at about $206.59 per share, almost double the last close at $104.08. This leaves a wide gap between what the narrative suggests and what the market is currently willing to pay.
The expansion and planned system-wide launch of MyWingstop's proprietary digital infrastructure, including hyper-personalized marketing and a new loyalty program leveraging a rapidly growing 60 million-member digital guest database, sets the stage for higher customer engagement, increased transaction frequency, and a sustained lift in digital sales mix, supporting long-term earnings growth.
See why 27 investors see Wingstop as 50% undervalued.
Result: Fair Value of $206.59 (UNDERVALUED)
Still, if softer demand among lower income guests lingers and new units underperform, the upbeat Wingstop narrative could look far too generous.
Find out about the key risks to this Wingstop narrative.
Another Check On Wingstop’s Valuation
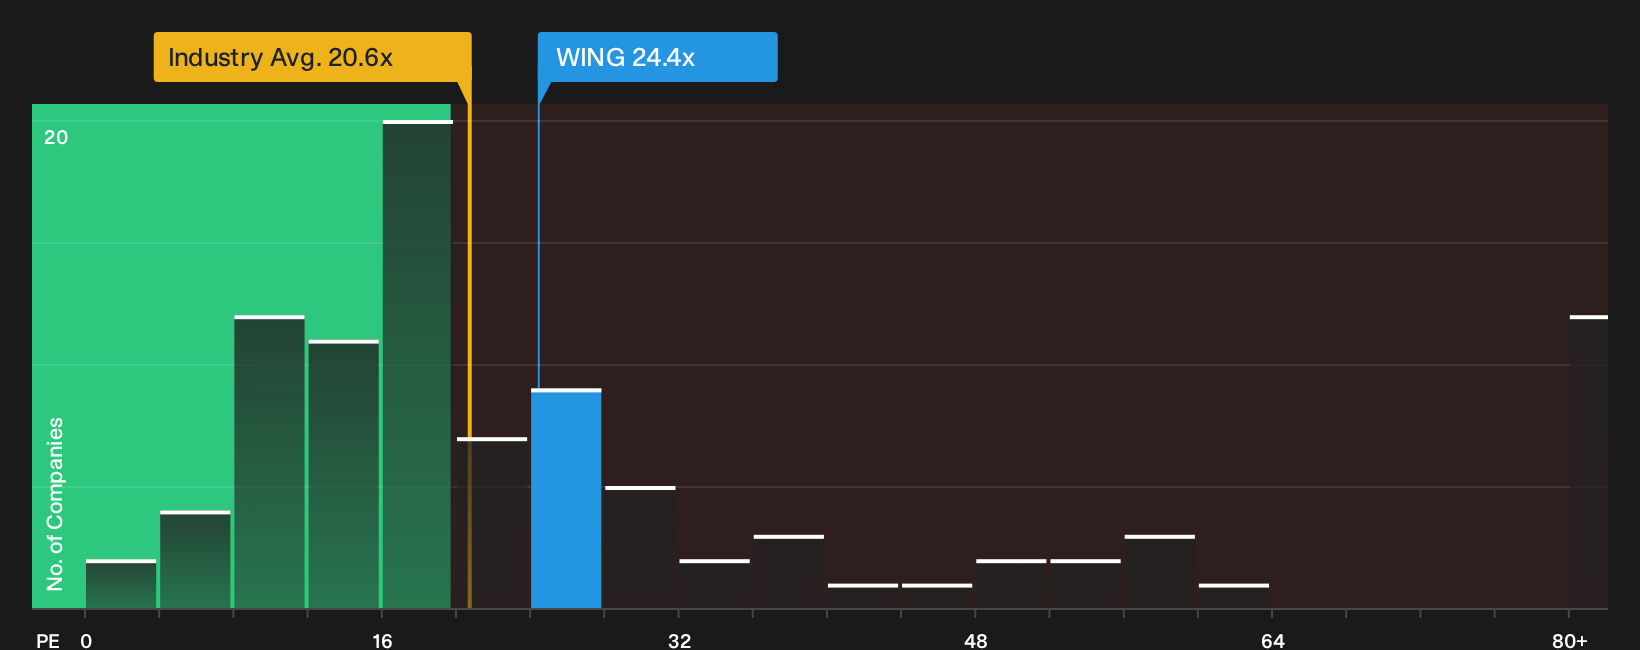
Analysts pitch Wingstop as almost 50% undervalued based on their fair value of about $206.59, yet the market still prices the shares at a P/E of 24.4x. That is higher than the US Hospitality average of 20.6x and above a fair ratio of 21.7x, while still lower than peer levels around 46.6x. Does that mix of a premium to the sector but a discount to peers signal opportunity, or a warning that expectations need resetting?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Wingstop's story are obvious. Move quickly, review the underlying metrics, and weigh the 2 key rewards and 3 important warning signs for yourself before forming a view.
Looking for more investment ideas beyond Wingstop?
If Wingstop has you rethinking your playbook, broaden your watchlist with a few focused screens that can surface different kinds of opportunities before the crowd catches on.
- Target dependable income by scanning companies that act like payout anchors through the 7 dividend fortresses.
- Hunt for mispriced quality by reviewing the 35 high quality undervalued stocks that combine solid fundamentals with discounted market expectations.
- Protect your downside by filtering for sturdier balance sheets using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com