
Why Did Enova International (ENVA) Stock Drop After Its Latest Update?
Why Enova International’s withdrawn banking bid matters now
Enova International (ENVA) pulled its banking license applications tied to the proposed Grasshopper Bancorp acquisition, while management reaffirmed 2026 revenue growth guidance and outlined plans for a business update.
Recent volatility around Enova International reflects that tension. The share price is down 21.8% over the past week and 28.1% over the past month, even after a 7.9% year to date share price gain and a 5 year total shareholder return of more than 4x. Together these figures indicate that long term momentum is intact, while shorter term confidence has clearly faded following the withdrawn banking bid and fresh guidance.
Spot 35 high quality undervalued stocks that, like Enova International, are in focus after regulatory or guidance shocks reset expectations.Enova International still looks like a profitable online lender with reaffirmed growth targets, yet the stock just reset sharply after the banking retreat. Is that reset generous pricing, or a rare opening for long term investors?
Most Popular Narrative: 37% Undervalued
Analysts tracking Enova International see a fair value of about $277 per share, which sits well above the recent $174.72 close, and link that gap directly to how the digital lending engine scales.
The scaling efficiencies of Enova's digital customer base, disciplined cost controls, and continued optimization of marketing effectiveness are driving operating leverage, leading to declining operating expenses as a percent of revenue and contributing to accelerating adjusted EPS growth and improving operating margins.
See why 11 investors see Enova International as 37% undervalued.
Result: Fair Value of $277.14 (UNDERVALUED)
Still, the Enova International story can break if regulators clamp down on high cost lending, or if credit losses spike for its largely nonprime borrowers.
Find out about the key risks to this Enova International narrative.
Another View: Enova International Through A Cash Flow Lens
The analyst fair value for Enova International sits at about $277 per share and points to a 37% gap versus the recent $174.72 price. A different tool tells a very different story. The SWS DCF model values ENVA at roughly $95.42, which implies the stock trades well above that cash flow estimate.
This second method leans entirely on long term cash generation rather than earnings multiples. For readers, the contrast is stark. One framework flags upside, the other suggests limited value on a cash flow basis. Which foundation do you trust more when real money is on the line: headline earnings or modeled future cash?
Look into how the SWS DCF model arrives at its fair value.
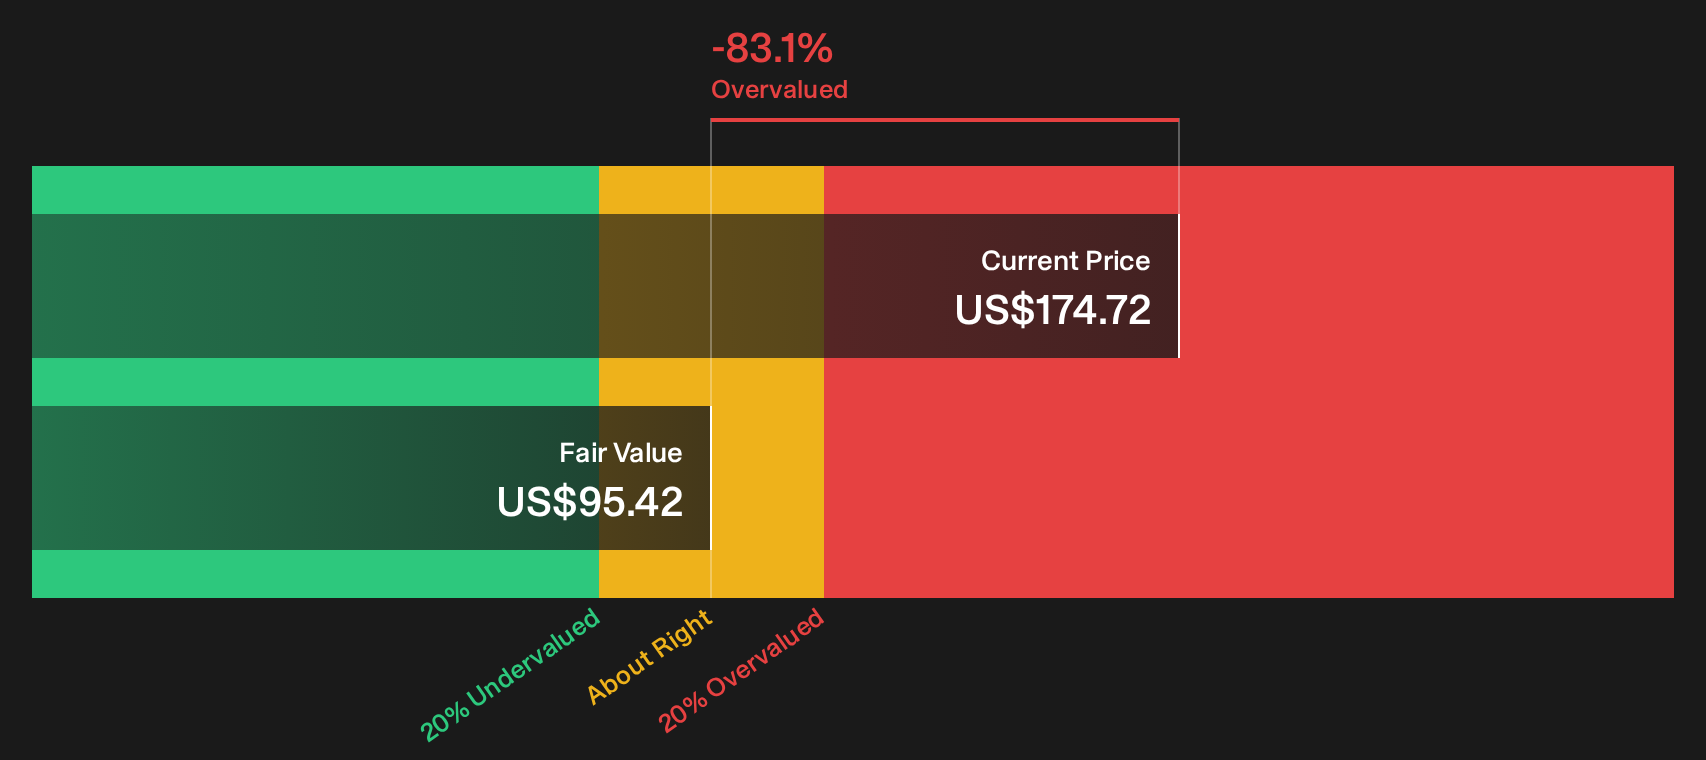
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Enova International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Enova International so far, right. If you want to move quickly and decide where you stand, start by weighing the 4 key rewards and 1 important warning sign.
Hunting for more ideas beyond Enova International?
Do not stop your research with Enova International when a wider watchlist could reveal opportunities that better match your risk profile, income goals, or growth preferences.
- Target potential mispricings by scanning a curated 35 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect their underlying business strength.
- Lock in potential income streams by reviewing a focused group of 7 dividend fortresses that aim to pair high yields with durability.
- Prioritize resilience by filtering through a handpicked 30 resilient stocks with low risk scores designed to keep sudden shocks from dominating your portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com