
Is Vail Resorts (MTN) Undervalued On Oasis Management Pressure And Epic Pass Concerns?
Oasis Management’s boardroom push at Vail Resorts (MTN) has sharpened attention on the business, as the activist questions how a 42 resort portfolio and Epic Pass trends are being managed.
Recent trading around Vail Resorts reflects that debate. The share price sits at US$139.80 after a 1-day share price return of 1.48%. However, the 30-day share price return is down 8.51% and the 1-year total shareholder return is only 1.42%. The 3 and 5 year total shareholder returns are down 33.03% and 50.84% respectively, pointing to weak longer term momentum that activist headlines and concerns about Epic Pass sales may now be bringing back into focus.
Spot potential alternatives while this Vail Resorts story plays out and scan a curated list of 35 high quality undervalued stocks that may offer stronger risk reward profiles.For Vail Resorts, the question now is whether the recent share move reflects a business under pressure or simply sentiment reacting to activism and Epic Pass worries. The valuation numbers give the next clues.
Most Popular Narrative: 5.9% Undervalued
Against Vail Resorts' last close at $139.80, the most followed narrative pegs fair value at $148.50. This frames the current activism and Epic Pass concerns against a modestly discounted valuation built on detailed future earnings assumptions.
The Epic Pass and Epic Day Pass programs are expected to continue growing, with a 7% average price increase for the 2025-2026 season, which should contribute positively to lift ticket revenue and overall EBITDA.
Vail Resorts' commitment to returning capital to shareholders through dividends and share repurchases demonstrates strength in cash flow management and capital allocation, which is likely to enhance earnings per share over time.
See why 8 investors see Vail Resorts as 6% undervalued.
The narrative uses a 10.09% discount rate and assumes revenue climbs from $2,831.4m to about $3.2b, with profit margins improving from 5.5% to 9.7%. That set of inputs produces a fair value estimate of $148.50 per share, only 5.9% above the current market price. The gap is relatively narrow despite the much larger $271.74 future cash flow value suggested by the separate SWS DCF model.
Analysts in this storyline expect earnings to rise from $156.8m to $310.0m by around July 2029, which implies significant earnings growth supported by cost efficiencies and higher margin pass products, although their forecasts span a wide range between $233.6m and $360.1m. To line up with the $148.50 target, that profit stream would need to trade on a 22.3x P/E multiple that is slightly below the current US Hospitality average. This effectively bakes in some moderation from today's P/E of 31.8x already flagged as expensive versus both industry and peers.
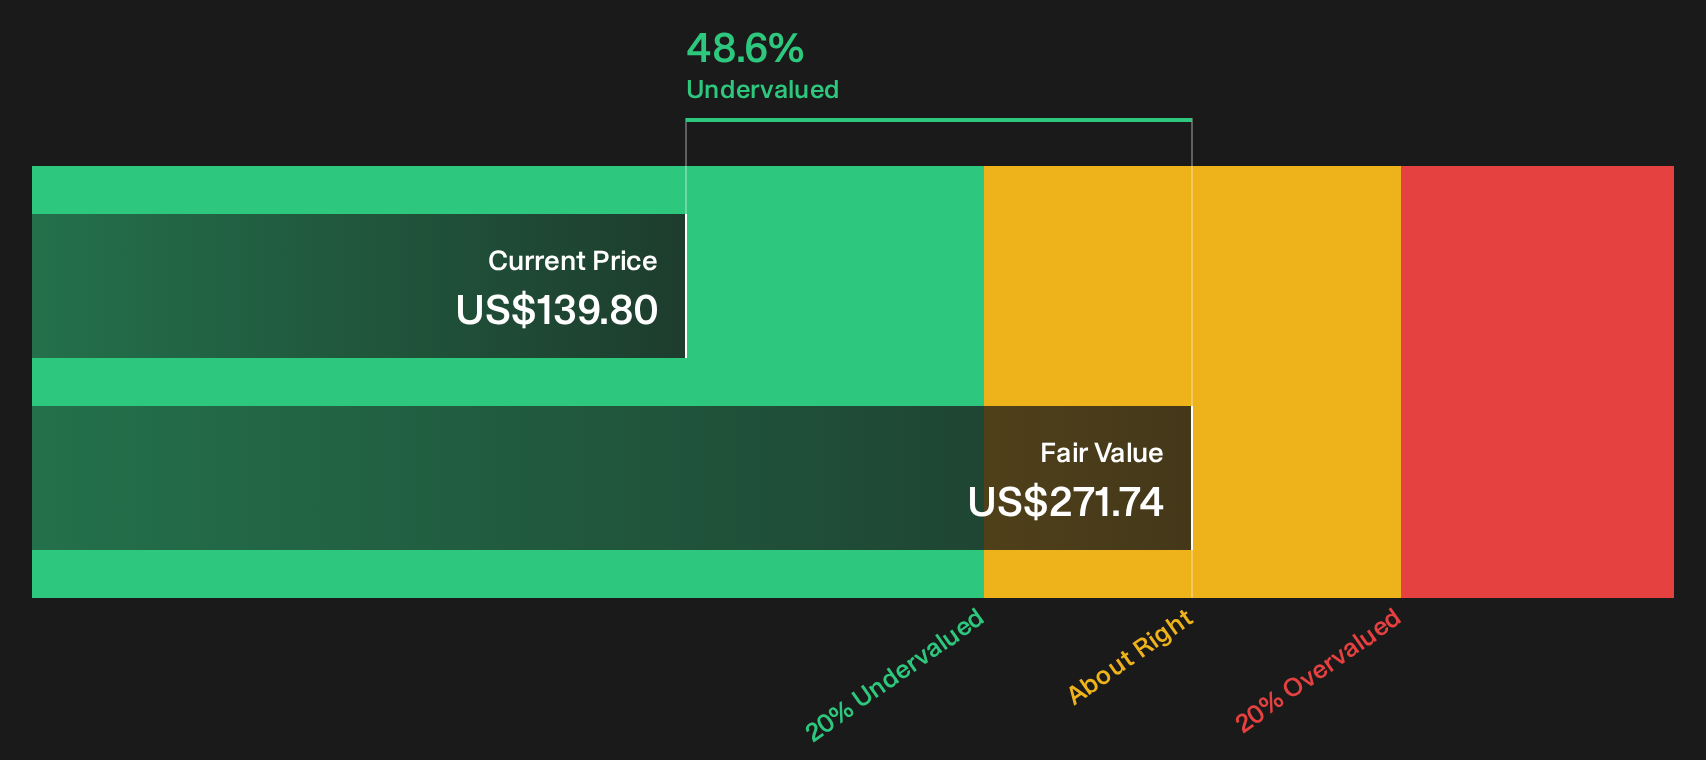
For readers weighing the Oasis campaign against these valuations, the key tension is clear. The narrative signals that Vail Resorts is only modestly undervalued on consensus assumptions, while the SWS DCF output and the 48.6% discount to internal fair value highlight a much larger upside implied by long term cash flow projections if execution matches those earnings and margin goals.
Result: Fair Value of $148.50 (UNDERVALUED)
Still, weather related swings in skier visits and softer early Epic Pass demand, including the reported 10% early season pass shortfall, leave Vail Resorts exposed if conditions remain challenging.
Find out about the key risks to this Vail Resorts narrative.
Another View on Vail Resorts Valuation
On the flip side of that 5.9% narrative undervaluation, the SWS DCF model points to a future cash flow value of $271.74 per share versus Vail Resorts' $139.80 price, suggesting the stock trades at roughly half that estimate. If cash flows come in closer to this DCF path, is the current focus on short term Epic Pass weakness missing the bigger picture?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Vail Resorts can easily pull views in opposite directions, so move quickly, review the full picture, and weigh both the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Vail Resorts?
If Vail Resorts has your attention but you want a wider opportunity set, use the Simply Wall St Screener to quickly surface fresh ideas that fit your style.
- Target potential upside by scanning a curated pool of companies that screen as attractively priced on quality and valuation using the 35 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (23 results) that can help you focus on businesses with stronger financial footing when conditions get bumpy.
- Hunt for under the radar opportunities through a 16 high quality undiscovered gems that could add diversification before the crowd pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com