
Axon Enterprise (AXON) Could Be 35% Below Fair Value After $1b Note Offering
Axon Enterprise (AXON) just closed a 0% convertible note offering that raised $1 billion, a funding move that sits at the center of current debate around dilution, balance sheet flexibility and long term growth spending.
Axon Enterprise shares have swung sharply around the financing news, with a 1-day share price return of down 1.27% and a 7-day move of down 6.59% as investors weigh potential dilution risk against the company’s increased capacity for acquisitions and growth projects.
Capitalize on the same balance sheet theme driving Axon Enterprise's $1b zero coupon notes by lining up other potential beneficiaries in our hand picked list of solid balance sheet and fundamentals (23 results).Axon Enterprise has slid from recent highs while analyst targets and intrinsic models point much higher, leaving a wide valuation gap. Is the market discount now generous, or already fair once dilution and execution risk are factored in?
Most Popular Narrative: 35% Undervalued
Axon Enterprise closed at $447.76 compared with a widely followed fair value estimate of $693.40. This frames the stock as trading at a steep narrative discount while debate builds around how durable its growth and margins really are.
Accelerating demand for next-generation technologies including AI, drones, robotics, body cameras, and digital evidence management demonstrates a rapid shift by public safety agencies toward modern, cloud-based, and connected solutions. This supports sustained revenue growth as agencies upgrade from legacy systems and adopt more comprehensive SaaS offerings.
See why 109 investors see Axon Enterprise as 35% undervalued.
Result: Fair Value of $693.40 (UNDERVALUED)
Still, Axon Enterprise leans heavily on government budgets and faces rising competition in AI, drones and evidence management. Any stumble here could quickly challenge that 35% undervalued story.
Find out about the key risks to this Axon Enterprise narrative.
Another View: SWS DCF Says Axon Enterprise Is Fairly Priced
The popular story paints Axon Enterprise as 35% undervalued, yet the SWS DCF model points to a very different conclusion. On that framework, Axon trades slightly above an estimated future cash flow value of $443.19, so the shares look closer to fairly valued than deeply discounted. Does that make the narrative gap a safety margin or a mirage for anyone leaning on the growth story?
Look into how the SWS DCF model arrives at its fair value.
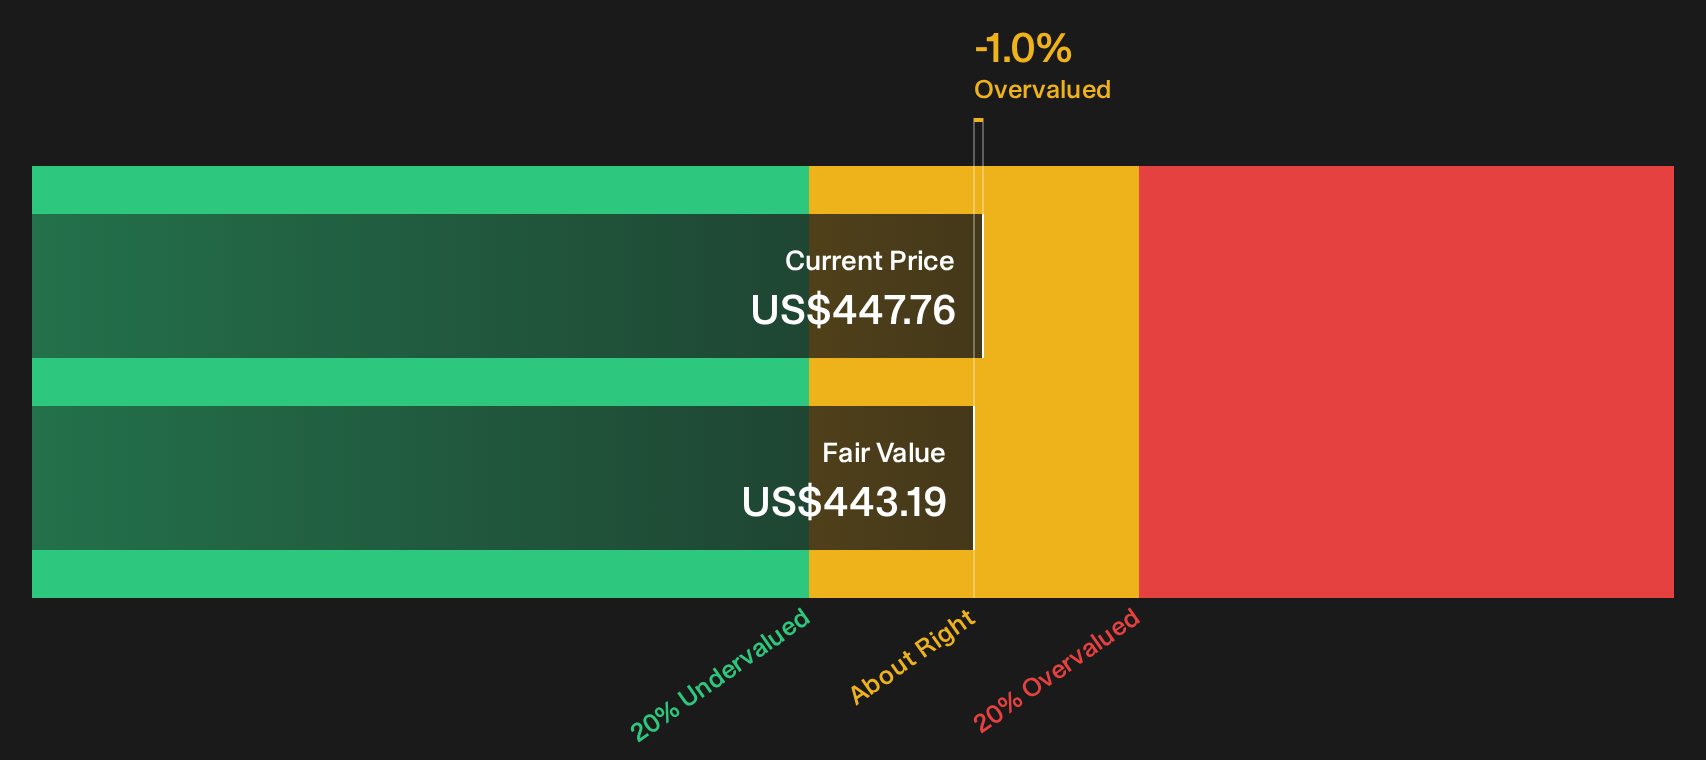
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Axon Enterprise for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted about whether Axon Enterprise is a bargain or already priced for perfection, especially after this zero coupon deal and valuation debate? Act quickly and stress test the story against both the upside potential and the risks, then cross check your view against our breakdown of 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Axon Enterprise?
If Axon Enterprise has you rethinking valuation, risk and balance sheet strength, use that momentum and line up a few fresh ideas that fit your own playbook.
- Target potential mispricings by scanning companies that combine quality fundamentals with attractive pricing using the 35 high quality undervalued stocks.
- Prioritize resilience and sleep-better-at-night holdings by checking out the 30 resilient stocks with low risk scores that filters for sturdier balance sheets and cleaner risk profiles.
- Get ahead of the crowd by reviewing the 16 high quality undiscovered gems that highlights strong businesses still flying under most investors' radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com