
Did Reduced Growth Outlook Just Shift Danaher Stock Investment Narrative?
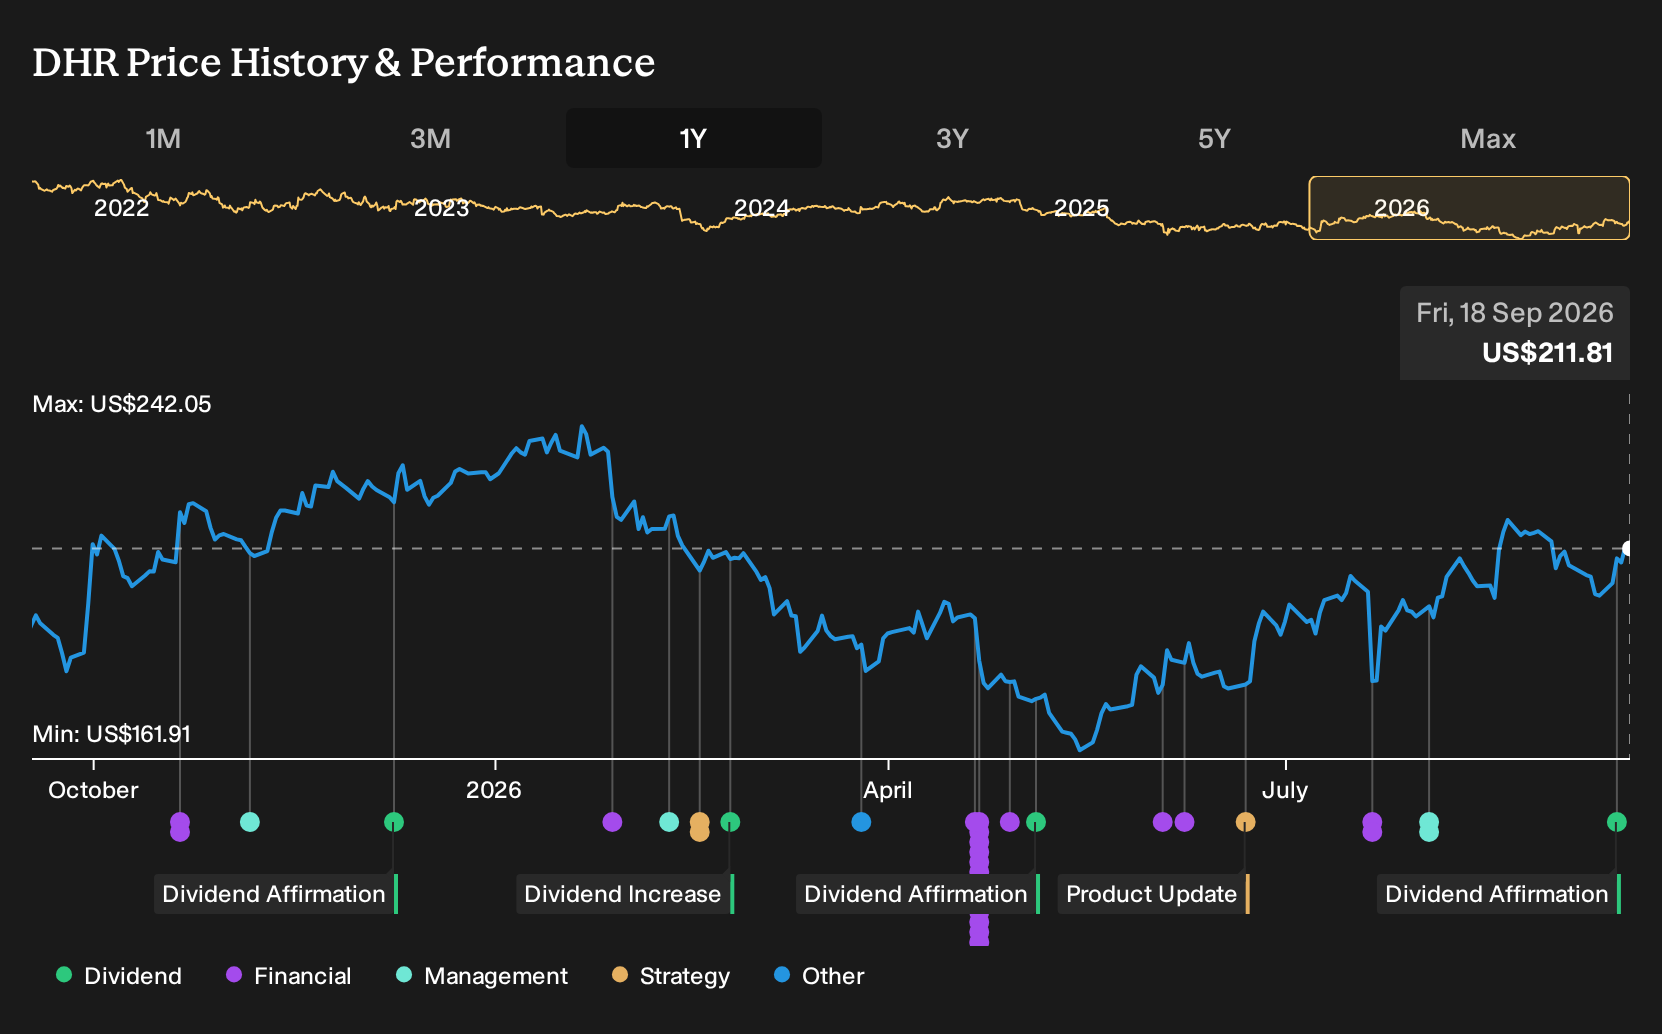
- Danaher Corporation confirmed a regular quarterly cash dividend of $0.40 per share, with the payment made on October 30, 2026 to shareholders of record as of September 30, 2026.
- Alongside this routine dividend, Danaher issued a reduced full year revenue growth outlook tied to deferred revenue, highlighting pressure on organic demand and cost efficiency at a time when recurring consumables and services are central to its business model.
- The focus now turns to how Danaher's lowered growth outlook, shaped by deferred revenue, may reshape the broader investment narrative around the group.
Danaher Investment Narrative Recap
To stay comfortable as a Danaher shareholder, you need to believe its consumables heavy model in biotechnology, life sciences and diagnostics keeps delivering steady demand even when equipment orders soften. The reduced full year revenue growth outlook and deferred revenue commentary do not change that long term thesis on their own, but they do underline slower near term momentum. The key short term catalyst is a clearer inflection in organic demand for bioprocessing and genomics tools. The biggest risk is that funding pressure in early stage biotech and policy changes in China keep that recovery muted for longer.
Cardinal Health’s stronger recent quarter created a sharp contrast that has put Danaher’s execution under a brighter spotlight. For you, the practical question is whether Danaher can keep converting its large installed base and recurring consumables into consistent earnings growth while dealing with deferred revenue and softer organic demand. The affirmed US$0.40 quarterly dividend shows the board’s confidence in current cash generation, but it does not offset fundamental risks around high exposure to bioprocessing, concentrated end markets and a high level of debt. Future quarters need to show that the Danaher Business System is still delivering cost productivity and margin resilience.
Danaher's current analyst narrative points to revenues of US$31.7b and earnings of US$6.9b by 2029, built on an assumed 8.0% yearly increase in revenue and an earnings uplift of US$2.9b from about US$4.0b today.
Uncover why Danaher's fair value indicates an 8% potential upside to its current price that could narrow quickly if sentiment improves.
Exploring Other Perspectives
The three fair value views from the Simply Wall St Community cluster tightly between about US$223.7 and US$229.1 per share, so you are looking at consistency rather than extremes. Those retail investors are not yet factoring in Danaher’s dividend affirmation, revenue deferrals, or biotech funding risks. Use their work as a starting point and explore more viewpoints.
Explore 2 other Danaher fair value estimates, including one that suggests up to 8% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Danaher research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Danaher. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Danaher's overall financial health at a glance.
Looking for more investment ideas beyond Danaher?
If the Danaher story has sharpened your thinking about quality fundamentals and risk, it can be useful to widen the lens and scan for other companies that fit the profile you care about most. The Simply Wall St Screener lets you filter for balance sheet strength, income potential, or unloved opportunities where the numbers and the share price are out of sync.
- For income focused investing with an eye on resilience, start with steady payers by reviewing 7 dividend fortresses that aim to combine higher yields with robust financial backing.
- If capital protection and stability matter most, tighten your risk profile by filtering for 30 resilient stocks with low risk scores where volatility and balance sheet pressure are already screened out.
- When you want to hunt for potential mispriced opportunities off the beaten track, cast a wider net across 16 high quality undiscovered gems that pair solid fundamentals with limited current attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com