
XPO (XPO) Faces Rising Diesel Costs, Is The Valuation Gap Still Compelling?
Why Rising Diesel Costs Put Fresh Attention on XPO Stock
Rising diesel prices are reshaping freight economics, and XPO (XPO) sits right in the middle of that shift through its cross-border less-than-truckload and European trucking operations.
The stock has fallen about 12% over the past month and 13% over the past 3 months, so investors are watching how fuel surcharges, pricing, and XPO's AI-driven efficiency efforts might influence margins from here.
Short term momentum for XPO has cooled, with the share price down 4.35% over the past week and 11.88% over the past month. However, the 1-year total shareholder return of 33.08% and 3-year total shareholder return of around 15x still point to a stock that has rewarded patient holders, even as recent diesel headlines and conference appearances, such as the upcoming Morgan Stanley Laguna event on 16 September 2026, reset expectations around fuel risk and execution.
Scan other freight and logistics plays facing the same diesel squeeze as XPO by reviewing our curated list of list of solid balance sheet and fundamentals (23 results).
Bulls see XPO's recent pullback as a reset in a freight carrier that still posts revenue and net income growth. Bears point to diesel risk and an already strong 3-year share run. Which side does the current valuation reward?
Most Popular Narrative: 25% Undervalued
Against XPO's last close of $174.25, the most followed narrative pegs fair value at $231.00. This frames the recent diesel pullback as a valuation gap rather than a broken story.
The analysts have a consensus price target of $231.0 for XPO based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $10.3 billion, earnings will come to $851.6 million, and it would be trading on a PE ratio of 39.6x, assuming you use a discount rate of 8.4%.
See why 11 investors see XPO as 25% undervalued.
Result: Fair Value of $231.00 (UNDERVALUED)
Still, XPO's heavy tilt toward cyclical U.S. freight and exposure to rising labor and regulatory costs could quickly challenge the AI and margin upgrade story.
Find out about the key risks to this XPO narrative.
Another View On XPO: Valuation Through Earnings Multiples
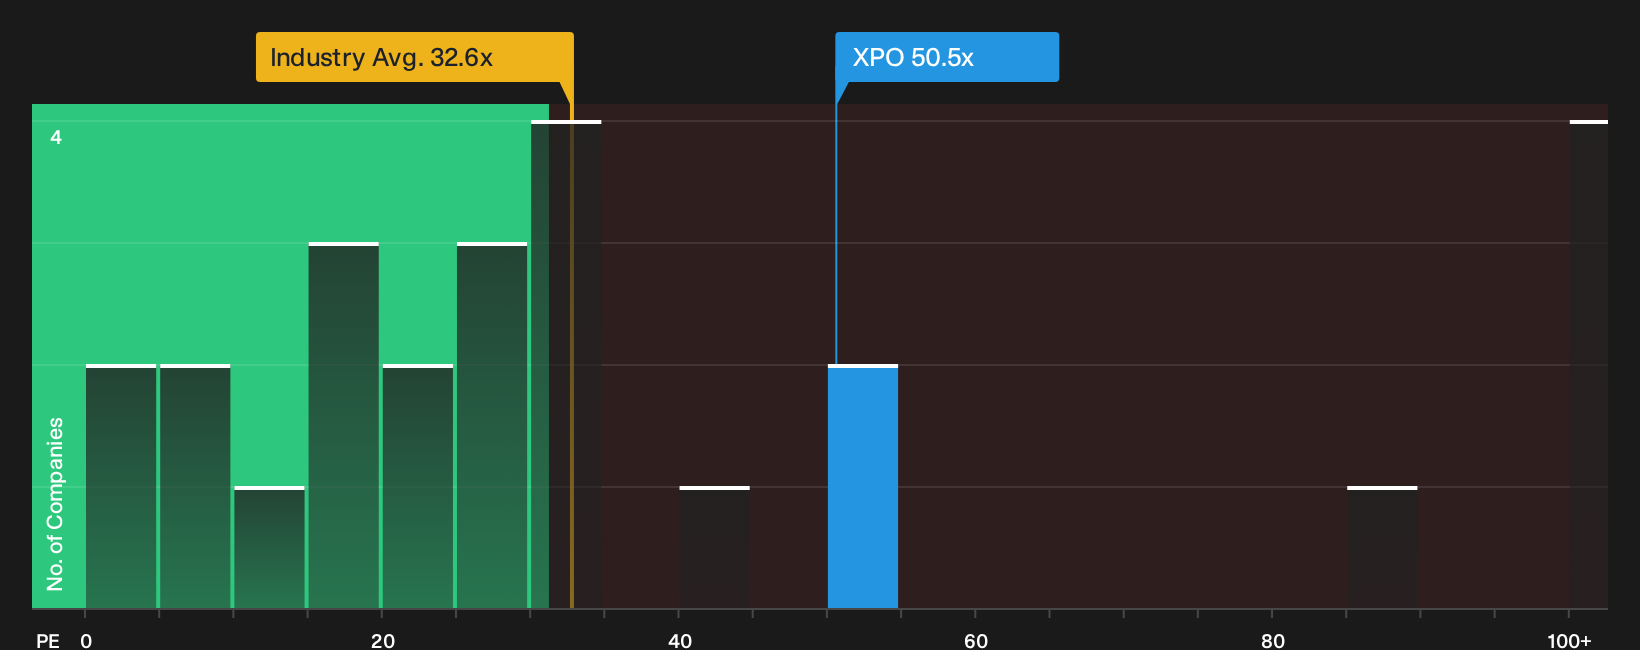
DCF work points to XPO trading below an estimated future cash flow value of $235.67. The picture changes when you zoom in on earnings ratios. The current P/E sits at 50.5x, well above the US Transportation industry on 32.6x and a fair ratio of 24.2x, which concentrates more valuation risk in any earnings disappointment.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views about whether XPO's recent pullback is a fresh opening or a warning flag. Act while sentiment is still resetting and weigh both sides by reviewing the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond XPO?
Do not stop your research with XPO. Broaden your watchlist now and give yourself more ways to react when the next opportunity shows up.
- Target potential mispricing by scanning a focused set of companies that screen as attractively valued using our 35 high quality undervalued stocks.
- Strengthen your income playbook by reviewing rock-solid payers highlighted in the 7 dividend fortresses.
- Protect your downside first by filtering for sturdier balance sheets inside the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com