
Does Earnings Beat Change The Bull Case For Ingersoll Rand Stock?
- Ingersoll Rand recently reported Q2 revenue up 8.5% year over year, beating analyst estimates on both sales and EPS while keeping full year EBITDA guidance unchanged.
- The quarter highlights solid demand for the company’s mission critical gas and liquid handling solutions, even as peers in the sector show mixed operating trends.
- We will now explore how this strong Q2 performance, combined with unchanged guidance, could affect Ingersoll Rand's broader investment narrative.
Compare Ingersoll Rand's Q2 setup with other industrial names that pair resilient demand with recent share price pressure by scanning our curated list of solid balance sheet and fundamentals (23 results)
Ingersoll Rand Investment Narrative Recap
To own Ingersoll Rand, you need to believe its focus on energy efficient equipment, aftermarket services and geographic breadth can keep demand reasonably steady through different spending cycles. The Q2 beat on sales and EPS, with EBITDA guidance unchanged, supports that thesis for now, even if the market reaction has been negative.
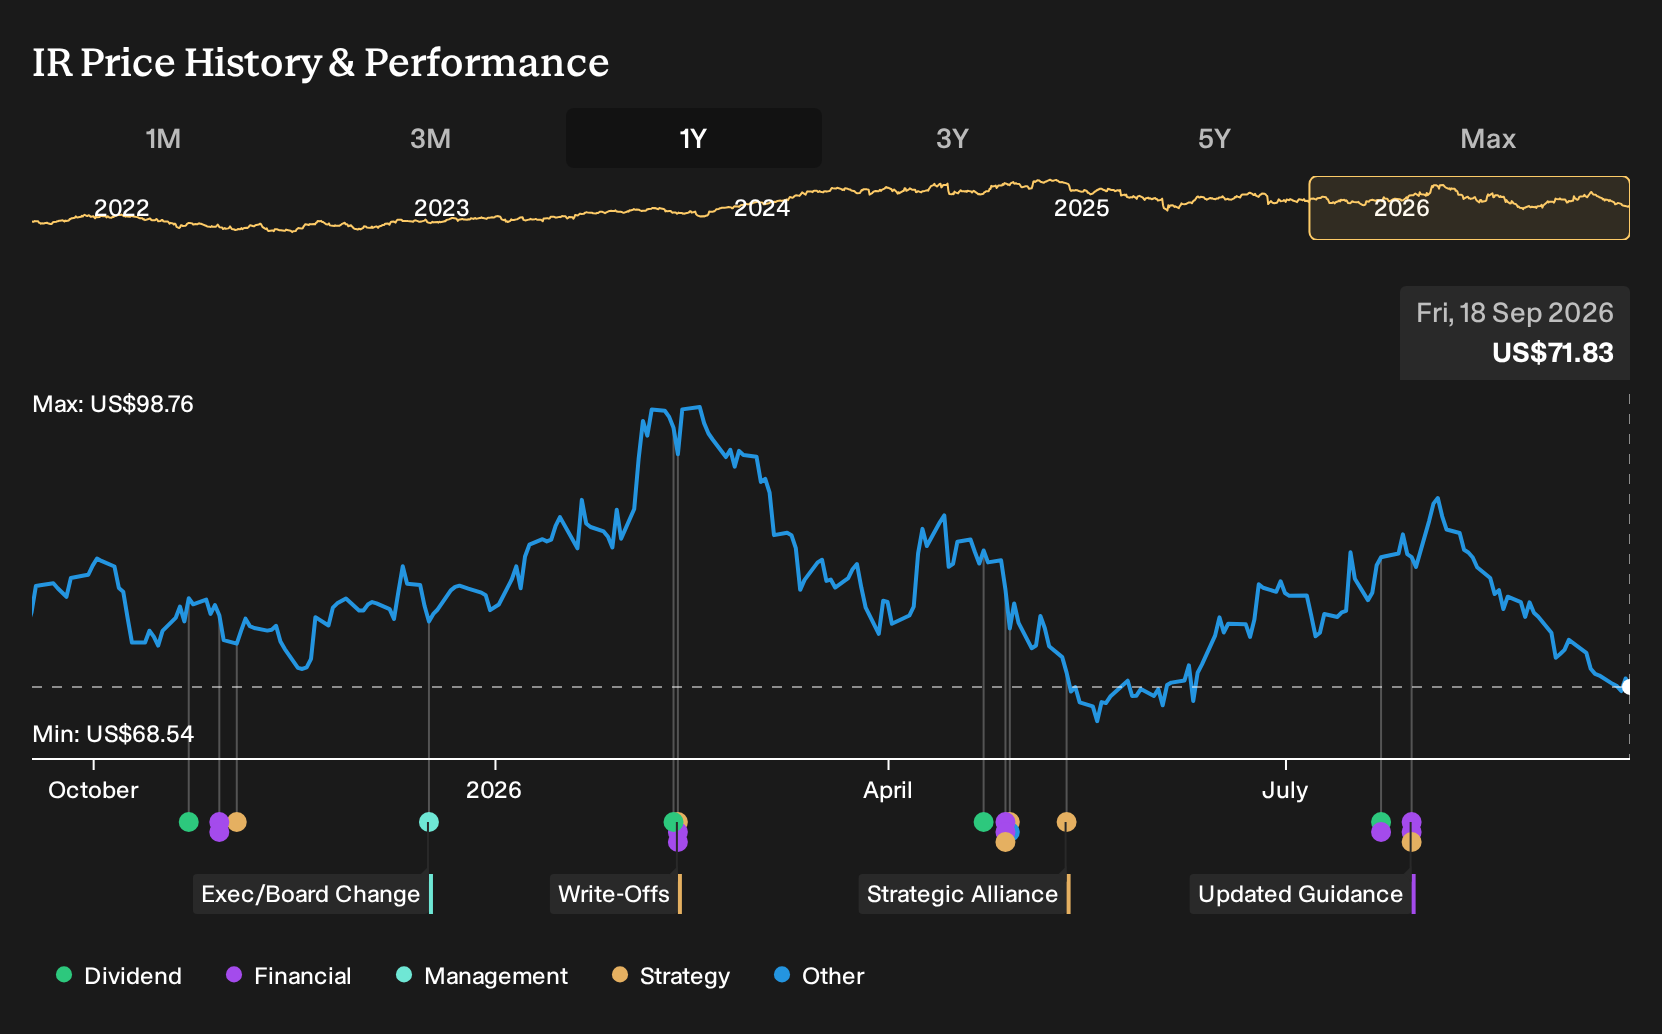
The key near term swing factor is how orders and pricing hold up in Compressors and related equipment as customers weigh big ticket projects. The sharp share price drop since earnings does not appear to stem from a clear deterioration in the business. The bigger risk still looks tied to acquisition execution and any future impairments.
With no fresh major announcements alongside this quarter, the most relevant context comes from the existing playbook investors already know. Ingersoll Rand has leaned on acquisitions, new products such as the CompAir Ultima compressor and the EVO Series pump, and a growing aftermarket mix to broaden its reach and lift margins over time.
That toolkit matters for the current catalyst debate. Strong Q2 results alongside a weaker share price leave execution in focus. The same M&A push that expanded markets and technology also brought impairments such as ILC Dover, so any next deal or integration update will likely be watched closely as investors weigh growth opportunities against the risk of lower returns.
Ingersoll Rand's narrative points to US$9.4b in revenue and US$1.6b in earnings by 2029, according to analyst estimates that reflect 5.9% yearly revenue growth and an earnings increase of about US$641m from current earnings of US$959.1m.
Uncover why Ingersoll Rand's fair value indicates a 34% potential upside to its current price that could narrow quickly as sentiment stabilizes.
Exploring Other Perspectives
For a very different angle, consider the bullish analysts who viewed Ingersoll Rand’s M&A push as a powerful catalyst. Before this Q2 report, that group was penciling in US$9.7b of revenue and US$1.6b of earnings by 2029, with a US$109.0 target. Their optimism may shift, and your view does not need to match theirs.
Explore 2 other Ingersoll Rand fair value estimates, including one that suggests as much as 34% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ingersoll Rand research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Ingersoll Rand. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ingersoll Rand's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ingersoll Rand?
If the Ingersoll Rand story has you thinking about where else resilient balance sheets and clear earnings drivers might show up, it can help to widen the lens and scan for other companies that fit your style and risk tolerance.
- If capital preservation comes first for you, start with a focus on financial strength and steady fundamentals using our 30 resilient stocks with low risk scores.
- If value is your north star, search for quality businesses trading below their estimated worth by running the 35 high quality undervalued stocks.
- If you prefer under-the-radar potential, hunt for lesser known businesses with solid financial profiles through the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com