
China Resources Power Holdings (SEHK:836) Renewable Output Picks Up, Is The Low P E Still Justified?
China Resources Power Holdings: Renewable output picks up pace
China Resources Power Holdings (SEHK:836) has released new figures, with August and year-to-date operating data indicating higher total power generation and faster growth from its wind and solar subsidiaries.
China Resources Power Holdings shares trade at HK$18.89 and the stock has built a steady positive trend, with a 30-day share price return of 5.53% and a 1-year total shareholder return of 10.41%. The 3-year total shareholder return of 52.43% suggests earlier buyers have already seen a substantial payoff as the market reacts to ongoing renewable expansion and a P/E of 7.3x that is below many peers.
Extend your research beyond China Resources Power Holdings and scan a curated 39 power grid technology and infrastructure stocks that could also benefit as electricity demand and grid investment trends evolve.
After a 5.53% move over the past month and a 3-year total return above 50%, the question around China Resources Power Holdings tightens. Do you pay the current 7.3x P/E, or wait for a cheaper swing point?
Preferred P/E of 7.4x for China Resources Power Holdings: Is it justified?
On the numbers alone, China Resources Power Holdings looks inexpensive, with a P/E of 7.4x at a HK$18.89 share price and several checks flagging it as good value against peers, the wider Hong Kong market, and an estimated fair P/E of 10x.
The P/E ratio tells you how much investors are paying for each unit of earnings, which matters a lot for a utility and renewable player where profit trends and capital intensity often shape sentiment more than rapid revenue expansion. For China Resources Power Holdings, earnings grew 3.1% over the past year and have compounded at 25.8% per year over the past 5 years, while net profit margins sit at 12.5%, slightly above last year, and are classed as high quality.
Compared with an Asian Renewable Energy industry average P/E of 14.6x and a Hong Kong market level of 10.9x, the 7.4x multiple looks materially lower and suggests the market is pricing in slower forecast growth of 2.6% earnings and 2.2% revenue per year. The fair P/E estimate of 10x implies a level the multiple could gravitate toward if investors place more weight on the company’s profit track record, quality of earnings and current return profile.
Explore the SWS fair ratio for China Resources Power Holdings.
Result: Price-to-Earnings of 7.4x (UNDERVALUED)
Still, China Resources Power Holdings faces potential pressure from tighter coal and gas costs, as well as any policy shifts that weigh on thermal power profitability.
Find out about the key risks to this China Resources Power Holdings narrative.
Another view on China Resources Power Holdings valuation
Our DCF model points to a future cash flow value of HK$18.17 per share, which is slightly below the current HK$18.89 price and suggests China Resources Power Holdings screens as mildly overvalued on this method. So which signal should carry more weight for you: the cheap 7.4x P/E or the full cash flow model?
Look into how the SWS DCF model arrives at its fair value.
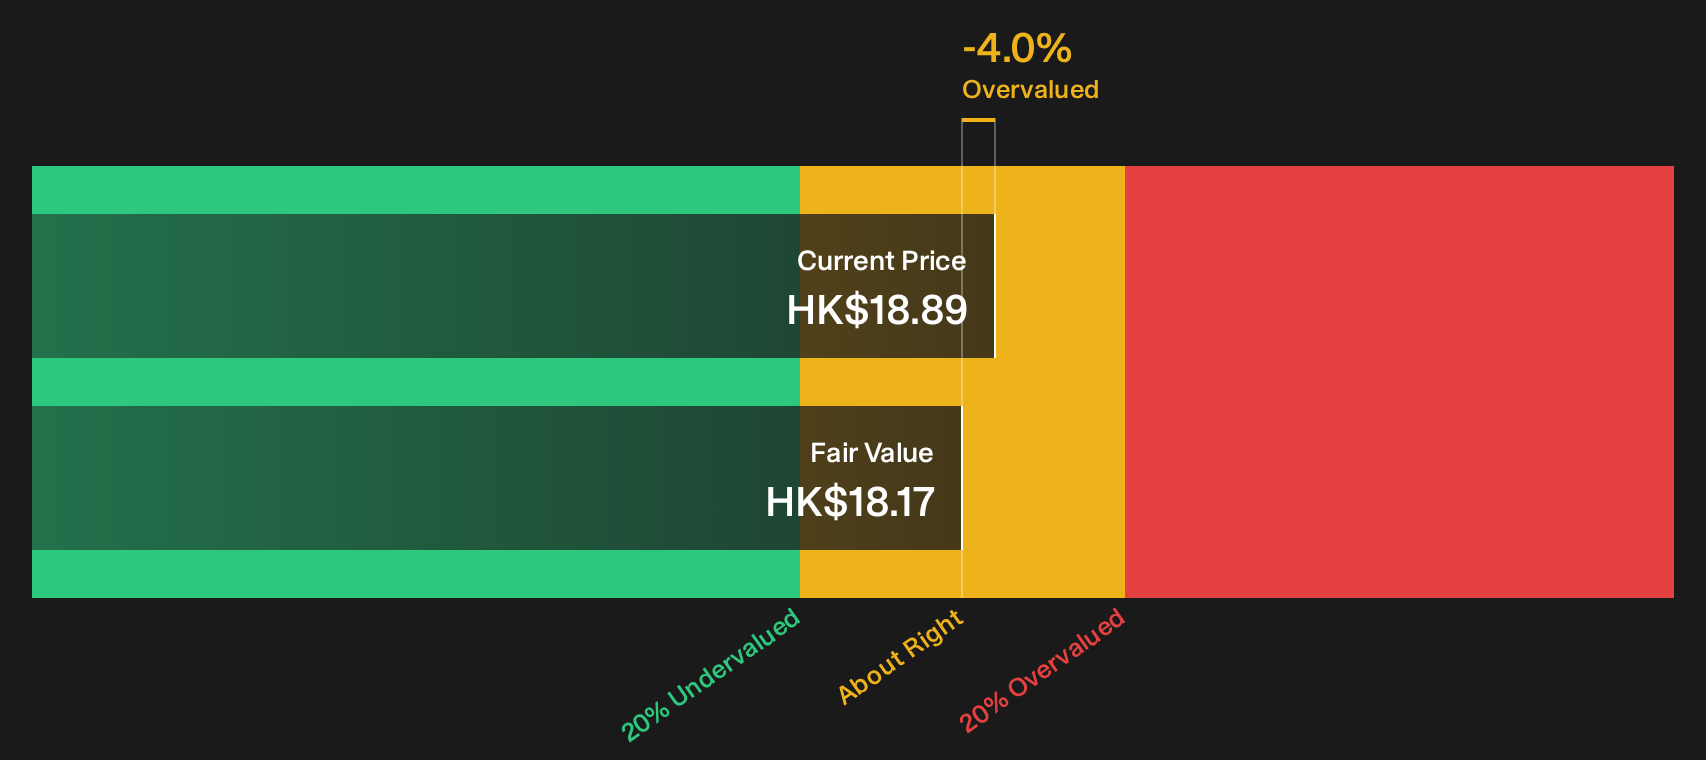
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Resources Power Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 180 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around China Resources Power Holdings valuation can feel confusing, especially with both risks and rewards on the table. Act while the data is fresh and stress test the thesis yourself by checking the 3 key rewards and 2 important warning signs
Looking for more China Resources Power Holdings investment ideas?
Do not stop with China Resources Power Holdings alone. The same discipline you apply here can reveal opportunities across sectors if you tap into a few focused screeners.
- Target durable value by scanning a curated pool of companies through the 180 high quality undervalued stocks that combine appealing prices with solid underlying fundamentals.
- Prioritise resilience and capital preservation by tracking a 226 resilient stocks with low risk scores that highlights businesses with more stable risk scores.
- Hunt for less crowded opportunities by reviewing a 613 high quality undiscovered gems that surfaces quality stocks the market has not fully priced yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com