
Xenon Pharmaceuticals (XENE) Could Be 47% Undervalued Following Psychiatry Trial Pause
Xenon Pharmaceuticals (XENE) is in focus after a sharp selloff tied to safety concerns in high profile psychiatry trials, just as its New Drug Application for azetukalner in focal seizures advanced with the FDA.
The sharp one-day share price drop of about 31% and roughly 35% decline over 30 days suggest risk perceptions around Xenon Pharmaceuticals have reset quickly after the psychiatry enrollment pause, even though the NDA news keeps attention on epilepsy as the nearer-term driver.
Stress test your thesis on Xenon Pharmaceuticals against peers by scanning a curated set of 30 resilient stocks with low risk scores that have held up better when trial or regulatory setbacks hit sentiment.
Epilepsy data and an NDA in hand suggest a real business taking shape at Xenon Pharmaceuticals, while a drop of more than 30% forces a different question. After this reset, is the pipeline strength already fully reflected in today’s price or not?
Most Popular Narrative: 47% Undervalued
Compared with the last close at $39.75, the most followed narrative for Xenon Pharmaceuticals points to a fair value of about $75.69, which frames the recent selloff as a valuation reset rather than an end of the story.
Advancing azetukalner toward multiple late stage readouts in focal onset and generalized seizures positions Xenon to tap a growing pool of refractory epilepsy patients who need better tolerated, easy to use therapies. This supports a step change in revenue on approval and later expands earnings as fixed R&D is leveraged.
See why 1 investors see Xenon Pharmaceuticals as 47% undervalued.
The narrative uses a discount rate of 7.27% and a fair value estimate of $75.69, which is about 47% above the current share price. Analysts in that framework model revenue reaching $449.0 million by around 2029 and earnings of $79.2 million, which implies a P/E of roughly 140x on those forecast profits to support that valuation.
That view leans heavily on azetukalner in epilepsy as the main economic engine, with psychiatry framed as optional upside rather than the anchor. It also bakes in ongoing investment, given Xenon Pharmaceuticals is currently loss making with a reported net loss of $409.2 million and no revenue, and is not forecast to reach profitability within the next three years.
The same storyline flags clear trade offs. A high implied future P/E multiple, expected share count growth of 7% per year over the next three years, and sensitivity to very large revenue growth assumptions all raise the bar for execution. At the same time, the SWS DCF model currently points to a future cash flow value of $425.24, which is far above both the narrative fair value and the present price, underlining how much of the projected cash generation still sits out in the future.
Result: Fair Value of $75.69 (UNDERVALUED)
Still, the story around Xenon Pharmaceuticals only holds if late stage epilepsy trials avoid meaningful safety or efficacy setbacks, and if tighter reimbursement trends do not squeeze pricing harder than analysts assume.
Find out about the key risks to this Xenon Pharmaceuticals narrative.
Another View: What Xenon Pharmaceuticals Looks Like On P/B
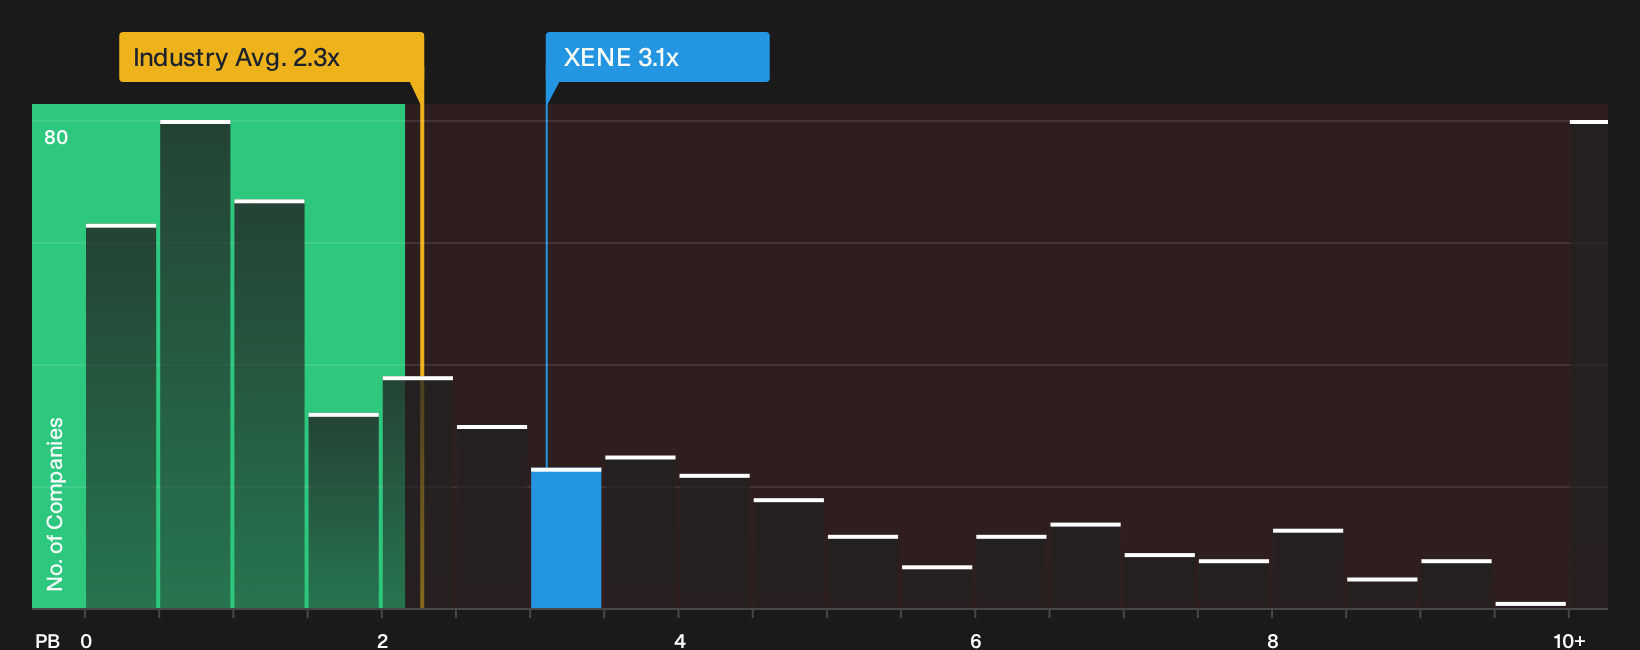
The SWS DCF model presents Xenon Pharmaceuticals as deeply undervalued, yet the simpler P/B check tells a different story. XENE trades at about 3.1x book value compared with 2.3x for the US biotech group and is flagged as expensive on this yardstick. If the fair ratio is lower than 3.1x, this raises the question of how much cushion remains if sentiment weakens again.
For a closer look at how the current valuation compares with what the numbers imply over time, walk through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If you are uncertain about the mixed signals on Xenon Pharmaceuticals, consider taking this opportunity to revisit the investment case while the reset is recent. Evaluate the thesis from both the risk and reward perspectives using 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Xenon Pharmaceuticals?
Before moving on, take a moment to broaden your watchlist. Fresh ideas often show up where pricing, balance sheets, and payouts line up in your favor.
- Target resilient returns by scanning a curated 30 resilient stocks with low risk scores that can help smooth your portfolio when single stock stories get bumpy.
- Hunt for mispriced potential using a focused 16 high quality undiscovered gems that highlights businesses with solid fundamentals but limited attention.
- Strengthen your income stream by reviewing a hand picked 7 dividend fortresses that combines higher yields with an emphasis on staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com