
Asian Value Stocks Trading Below Estimated Intrinsic Worth
As Asian markets navigate a landscape marked by fluctuating oil prices and evolving geopolitical tensions, investors are increasingly focused on the potential for value stocks to offer stability amid uncertainty. In this environment, identifying stocks trading below their intrinsic worth can be crucial for those seeking to capitalize on market inefficiencies.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Shizuki Electric (TSE:6994) | ¥1208.00 | ¥2300.70 | 47.5% |
| Rakus (TSE:3923) | ¥1082.00 | ¥2061.30 | 47.5% |
| PAL GROUP Holdings (TSE:2726) | ¥1486.00 | ¥2881.63 | 48.4% |
| Niterra (TSE:5334) | ¥7218.00 | ¥13817.91 | 47.8% |
| Monde Nissin (PSE:MONDE) | ₱6.41 | ₱12.68 | 49.5% |
| Ichikoh Industries (TSE:7244) | ¥565.00 | ¥1074.26 | 47.4% |
| Dongwon Industries (KOSE:A006040) | ₩35550.00 | ₩70464.35 | 49.5% |
| China Coal Energy (SEHK:1898) | HK$10.49 | HK$20.12 | 47.9% |
| Cheil Worldwide (KOSE:A030000) | ₩17300.00 | ₩34302.03 | 49.6% |
| AK Medical Holdings (SEHK:1789) | HK$4.865 | HK$9.57 | 49.2% |
Let's dive into some prime choices out of the screener.
Thai Vegetable Oil (SET:TVO)
Overview: Thai Vegetable Oil Public Company Limited, along with its subsidiary Prodigy Public Company Limited, is engaged in the manufacturing and distribution of soy meal and soybean oil both within Thailand and internationally, with a market capitalization of THB24.46 billion.
Operations: The company's revenue primarily comes from the manufacture and distribution of products from soybean, amounting to THB29.81 billion, with an additional contribution of THB649 million from the manufacture and distribution of packaging products.
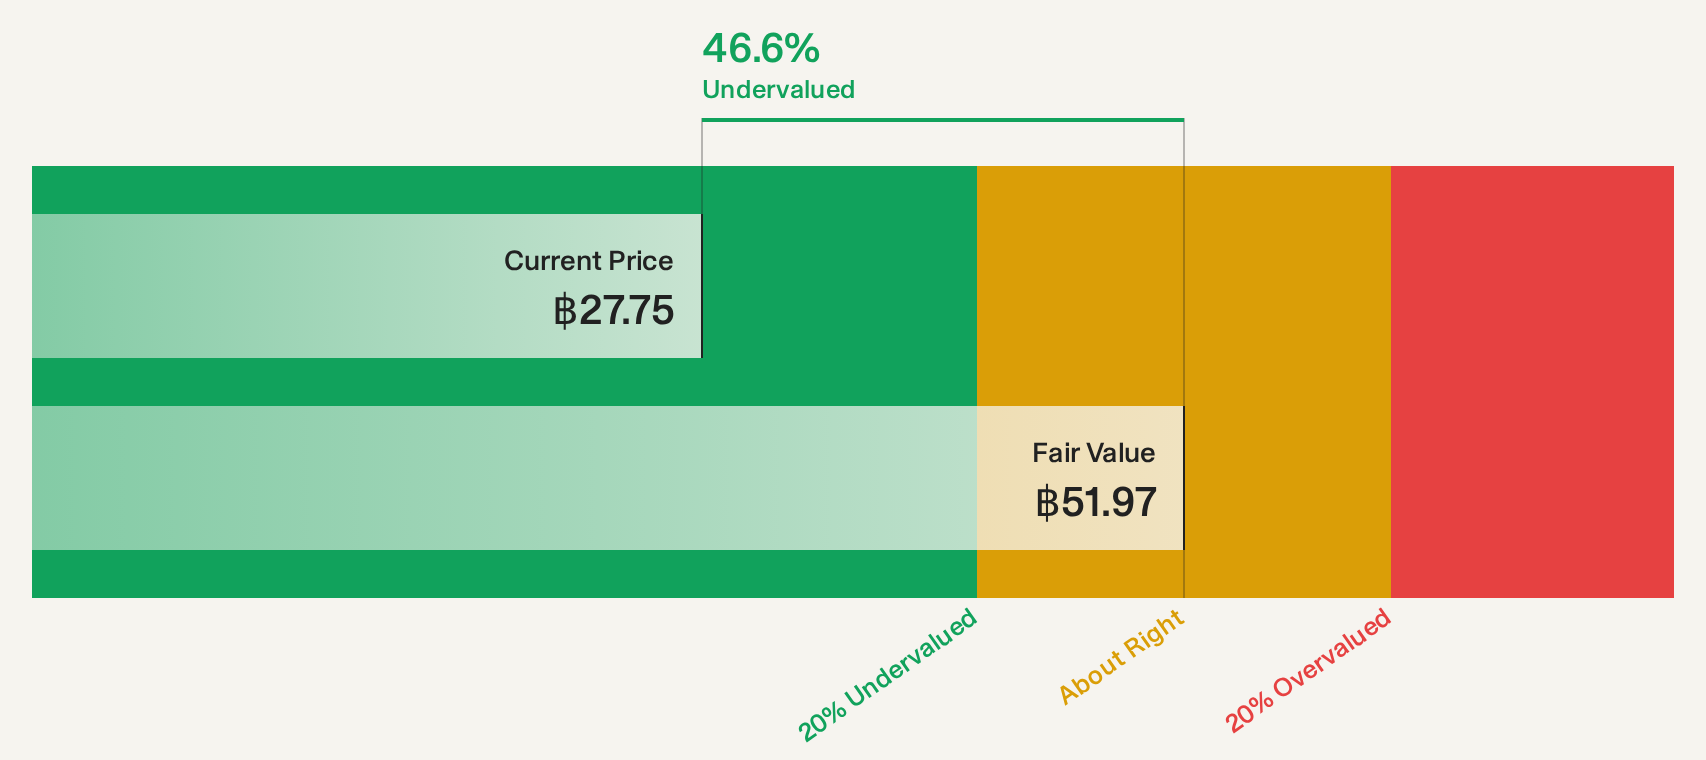
Estimated Discount To Fair Value: 47.1%
Thai Vegetable Oil is trading at THB 27.5, significantly below its estimated future cash flow value of THB 51.97, indicating it may be undervalued based on cash flows. Recent earnings showed strong growth with net income rising to THB 877.11 million in Q2 2026 from THB 647.62 million a year ago. However, its revenue growth forecast of 4.8% annually lags behind the Thai market average of 8.1%, and dividend sustainability is questionable due to limited free cash flow coverage.
- Insights from our recent growth report point to a promising forecast for Thai Vegetable Oil's business outlook.
- Take a closer look at Thai Vegetable Oil's balance sheet health here in our report.
PAL GROUP Holdings (TSE:2726)
Overview: PAL GROUP Holdings CO., LTD. operates in Japan, focusing on the sale of clothing, with a market capitalization of ¥257.16 billion.
Operations: The company's revenue is primarily derived from its Clothing Business, which generates ¥146.95 billion, and its Miscellaneous Goods Business, contributing ¥90.15 billion.
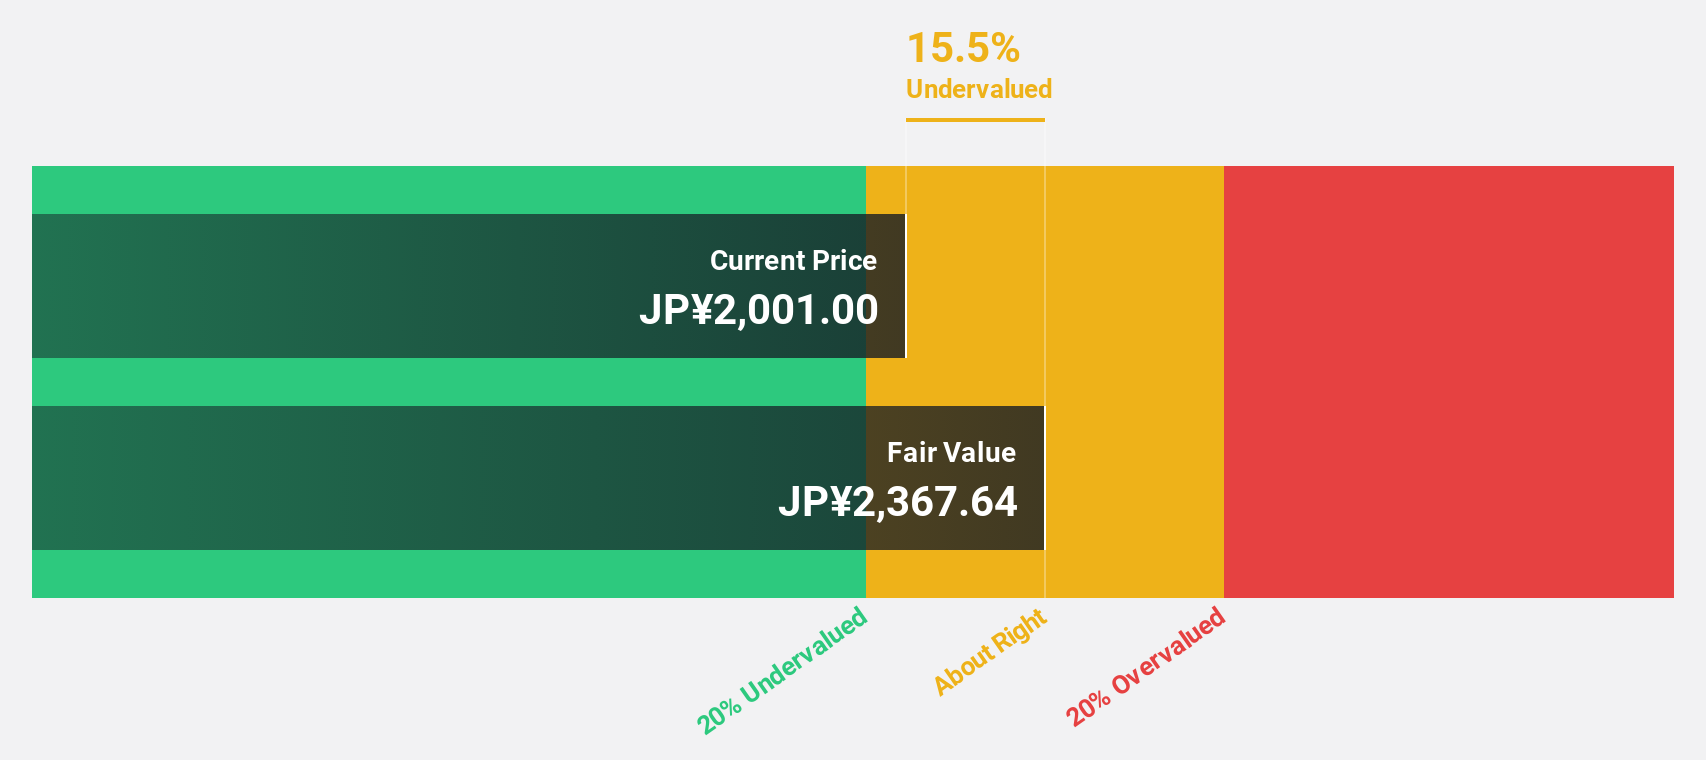
Estimated Discount To Fair Value: 48.4%
PAL GROUP Holdings is trading at ¥1,486, significantly below its estimated future cash flow value of ¥2,881.63, suggesting potential undervaluation. Despite projected earnings growth of 8.23% annually being slower than the market average, recent profits rose by 46.2%. A recent buyback completed in August 2026 for ¥848.95 million may enhance shareholder value. However, revenue growth forecasts remain modest at 6.5% per year compared to the broader market expectations.
- Our growth report here indicates PAL GROUP Holdings may be poised for an improving outlook.
- Delve into the full analysis health report here for a deeper understanding of PAL GROUP Holdings.
Sunonwealth Electric Machine Industry (TWSE:2421)
Overview: Sunonwealth Electric Machine Industry Co., Ltd. and its subsidiaries engage in the research, manufacturing, and sale of precision motors and cooling fans globally, with a market cap of NT$48.20 billion.
Operations: The company's revenue is primarily derived from Greater China, contributing NT$32.90 billion, followed by Europe and North America with NT$656.19 million.
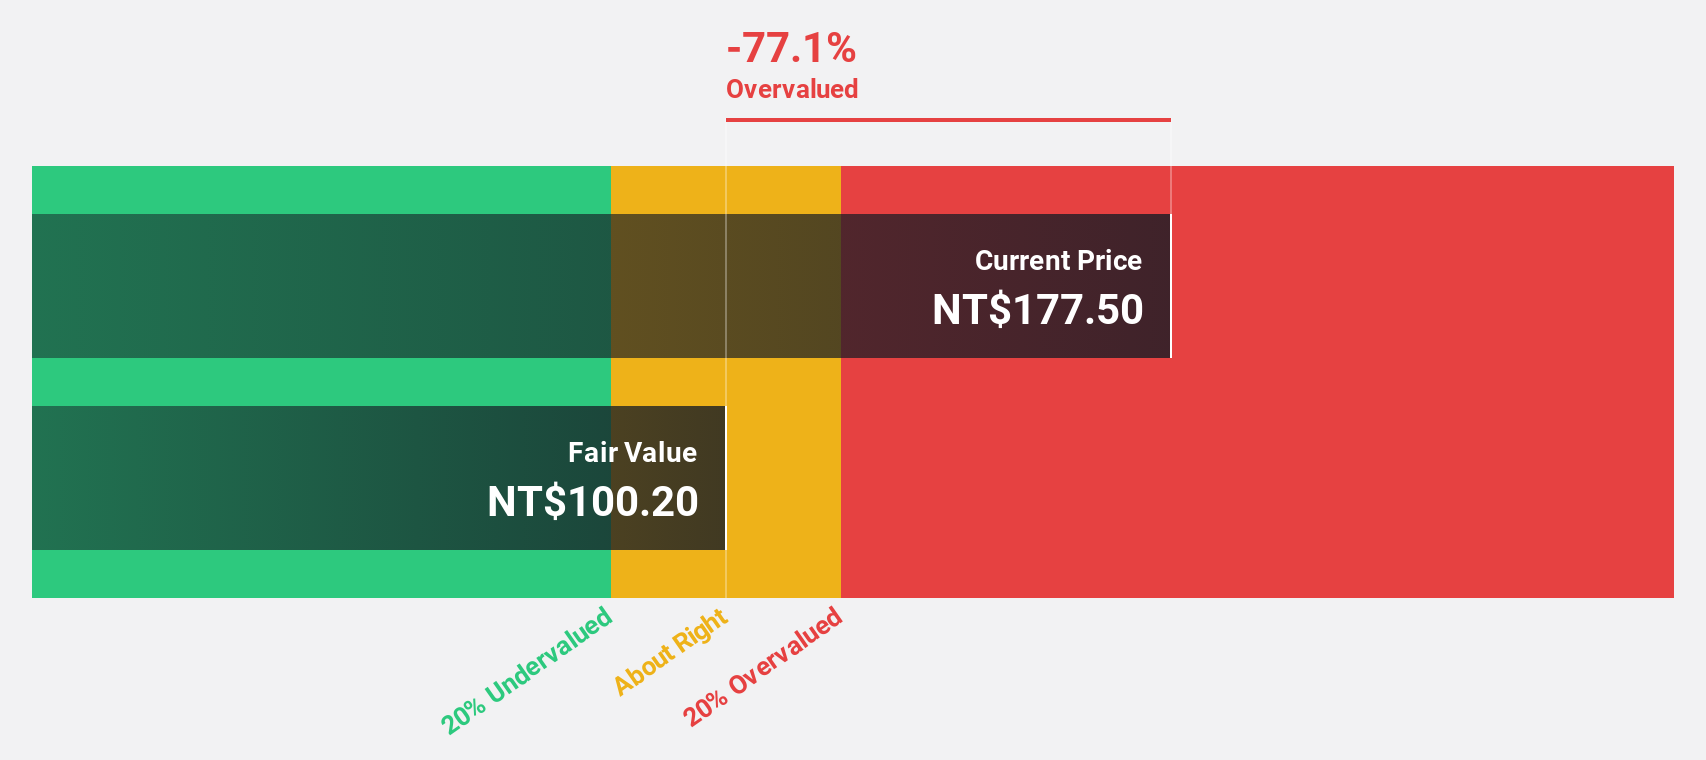
Estimated Discount To Fair Value: 40.1%
Sunonwealth Electric Machine Industry is trading at NT$168.5, substantially below its estimated future cash flow value of NT$281.08, highlighting potential undervaluation. Recent earnings grew by 62.8%, with forecasts predicting a 21.6% annual increase in profits, although slower than the Taiwan market average. Despite strong product innovations like the Green EC Fan Series and bionic HVLS ceiling fans, revenue growth is expected to lag behind market expectations at 17.1% annually.
- Our earnings growth report unveils the potential for significant increases in Sunonwealth Electric Machine Industry's future results.
- Click to explore a detailed breakdown of our findings in Sunonwealth Electric Machine Industry's balance sheet health report.
Summing It All Up
- Investigate our full lineup of 80 Undervalued Asian Stocks Based On Cash Flows right here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com