
Expeditors International Of Washington (EXPD) Could Trade At A 12% Premium Following Germany Hub Win
Client partnership in Europe puts Expeditors International of Washington in focus
L.B. Foster Company’s decision to appoint Expeditors International of Washington (EXPD) as its strategic distribution partner for mainland Europe, with a new German hub, gives investors a fresh operational milestone to assess.
The arrangement is built around a single goal: bring L.B. Foster’s products closer to European customers through a centralized distribution center in Germany that targets shorter delivery times and more predictable logistics.
For Expeditors International of Washington, the expanded mandate in Europe showcases its role as a logistics coordinator rather than an asset-heavy carrier. The firm relies on an asset light model that focuses on freight forwarding, customs brokerage, and related services across air, ocean, and ground transportation.
Germany’s transport network and central position in Europe provide the backdrop. L.B. Foster expects the hub to support distribution across key markets while Expeditors contributes its logistics network, local market knowledge, and customer support.
Management at L.B. Foster describes the partnership as an extension of an existing relationship. The intent is to create a scalable platform that can handle different product segments and industries while simplifying logistics processes for European customers.
For readers tracking the stock, the news does not change Expeditors International of Washington’s basic profile. It still operates as a global logistics services provider with US$12.0b in revenue, spread across regions that include the United States, Europe, North Asia, and South Asia.
The European piece of that revenue base currently stands at US$1.9b, with the United States at about US$4.0b. Investors watching this latest agreement may be most interested in whether the German hub helps the business deepen customer relationships in that European segment over time.
The partnership also arrives alongside solid long term share performance. Over the past year, Expeditors International of Washington has delivered a total return of 60.6%, with the past 3 months up 17.0% and year to date performance at 25.7%.
Shorter term readings are more muted. The stock was roughly flat over the past week, slipping 0.9%, and gained 1.7% over the past month, closing at US$190.94 on 16 September 2026.
Market value now sits near US$24.8b. That capitalisation reflects investor expectations for an asset light logistics group that produced US$918.8m in net income on US$12.0b in sales, according to the latest available figures.
Discounted cash flow work provided indicates something important for readers who focus on intrinsic worth. Current pricing is estimated to be about 12% above that cash flow based valuation, which places the stock at a modest premium under those assumptions.
That premium sits alongside a reported value score of 0, suggesting traditional value screens may not currently flag Expeditors International of Washington as inexpensive. For investors, the question becomes whether the business model and growth projects justify paying above an internally estimated fair value.
The L.B. Foster arrangement does not answer that question by itself. It does illustrate how Expeditors International of Washington is being used by industrial clients that want to firm up supply chain resilience while pushing product closer to end markets in Europe.
If the German hub delivers on its design goals, L.B. Foster expects faster availability and more reliable service for infrastructure customers across the continent. That outcome would reinforce the idea that Expeditors can translate its logistics expertise into long term client relationships rather than one off freight assignments.
Set against the new German hub and a leadership shift toward professional services, Expeditors International of Washington combines a strong 1 year total shareholder return of 60.6% with firm 3 year and 5 year gains. Recent share price momentum has cooled compared with the stronger 90 day move and year to date rise.
Capitalize on what Expeditors International of Washington is doing in logistics by scanning a curated set of list of solid balance sheet and fundamentals (23 results) that could benefit from similar supply chain tailwinds.Expeditors International of Washington now trades above both internal cash flow estimates and the average analyst target. The central question is whether that premium reflects lasting quality or instead signals a valuation gap that could narrow next.
Price-to-Earnings of 27x for Expeditors International of Washington: Is it justified?
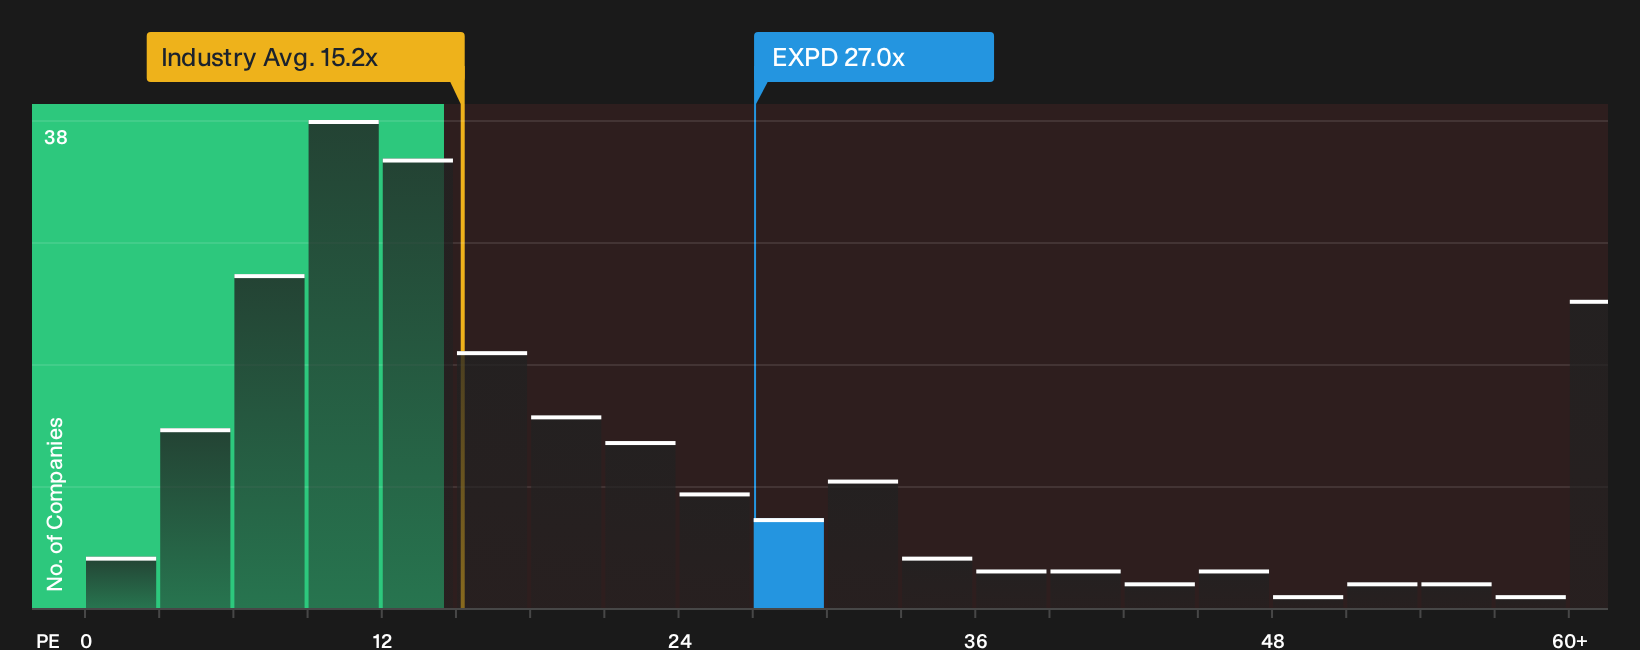
Expeditors International of Washington trades on a P/E of 27x, which is rich against both its own fair P/E estimate and logistics peers at the latest $190.94 close.
The P/E ratio compares the current share price with earnings per share, so at 27x investors are paying a premium for each dollar of profit. For a logistics services provider like Expeditors, that usually reflects what the market thinks about the durability of cash generation and the quality of its contracts rather than rapid expansion.
Available checks point to earnings expected to grow at 3.5% per year and revenue at 3.1% per year, which both sit below broader US market forecasts. That slower outlook sits next to an estimated fair P/E of 17.7x and a global logistics industry average of 15.2x. As a result, the current 27x multiple is materially higher than both where peers trade and where the SWS model suggests it could settle over time.
Explore the SWS fair ratio for Expeditors International of Washington.
Result: Price-to-Earnings of 27x (OVERVALUED)
Still, Expeditors International of Washington faces clear pressure points if freight volumes soften or if clients push aggressively for lower contract pricing.
Find out about the key risks to this Expeditors International of Washington narrative.
Another view on Expeditors International of Washington’s valuation
The P/E work already points to Expeditors International of Washington trading rich at 27x. The fair ratio of 17.7x, well below both the current multiple and the global logistics average of 15.2x, hints at valuation risk if sentiment cools or growth expectations reset. Which reference point matters most for you: the fair ratio, peers, or the current price?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Expeditors International of Washington for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Looking for more investment ideas beyond Expeditors International of Washington?
If Expeditors International of Washington has your attention, do not stop here. Fresh ideas in other corners of the market could shape your next move.
- Target overlooked value by scanning companies on solid footing through the 35 high quality undervalued stocks.
- Prioritise resilience and capital preservation by filtering for a pool of 30 resilient stocks with low risk scores.
- Hunt for early opportunities with robust fundamentals by reviewing a focused 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com