
Higher for Longer Rates Put These US Bank Stocks Under Pressure
Interest rates keep climbing, inflation sits at 3.4%, and the Federal Reserve is signalling it would rather err on the side of tighter policy than quick growth. That mix can punish some corners of the market while opening quieter opportunities elsewhere. If higher-for-longer rates reshape which stocks hold up best, you will want to know where the pressure and potential sit. This article walks through three US financial stocks from our screener that appear particularly exposed to this new rate reality.
The three stocks highlighted next are only a sample from this corner of the market, as the full screen surfaced 40 more U.S. financial companies with equally compelling rate and balance sheet stories that are not covered here. To go broader and identify your own higher conviction ideas, head straight into the US Financial Stocks (Banks and Diversified Financials) screener
CVB Financial (CVBF)
Overview: CVB Financial runs Citizens Business Bank, providing loans, deposits, and financial services to small and mid-sized U.S. businesses and households.
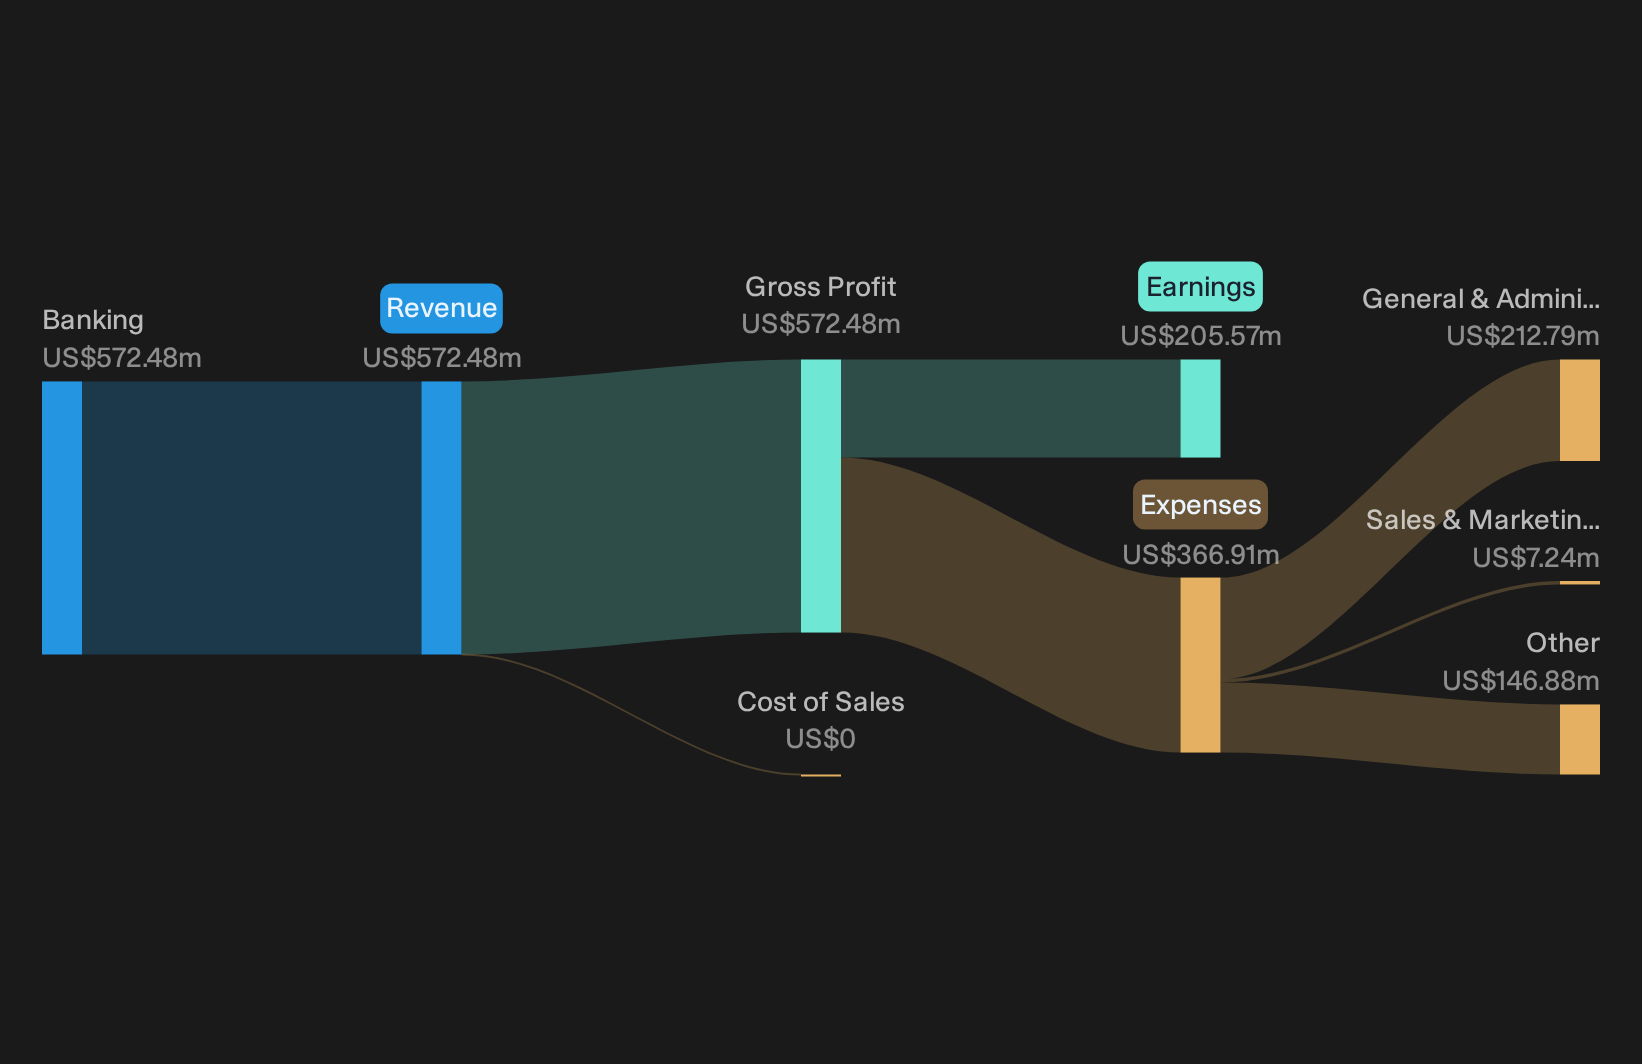
Operations: CVB Financial generates about US$572 million of revenue from its core banking activities in the United States, focused on traditional lending and deposits.
Market Cap: US$4.0b
CVB Financial sits in the middle of this screener as a U.S. commercial bank whose earnings lean heavily on the gap between what it earns on loans and what it pays on deposits. This makes its rate sensitivity central to the higher for longer story.
"Expansion and record performance of the Specialty Banking group, alongside increasing digital transaction activity among small and mid-sized businesses, creates opportunities for higher fee income and cross-selling of digital banking products, supporting top-line revenue growth."
What happens to margins if a single unseen pressure on funding costs or credit quality breaks the current earnings narrative?
If that unseen pressure worries you, read the full narrative for CVB Financial to see how CVB Financial’s fee engine, deposit mix and credit risks could be decoupling from the headline story.
Dime Commercial Bancshares (DCOM)
Overview: Dime Commercial Bancshares is a New York based bank holding company providing loans, deposits, and financial services to businesses, consumers, and municipalities.
Operations: The business generates about US$439 million in revenue from community banking activities concentrated in the United States.
Market Cap: US$1.8b
For the US Financial Stocks screener, Dime Commercial Bancshares presents a community banking franchise where earnings are closely linked to the spread between income on loans and interest paid on deposits.
"The upcoming repricing of nearly $2 billion in loans at substantially higher market rates by the end of 2026, plus another $1.7 billion in 2027, is expected to structurally expand net interest margin and boost earnings significantly in the medium to long term."
What happens to those ambitions if unresolved pressure on funding costs or credit quality interrupts the expected path higher for margins?
That risk cuts both ways. Read the full narrative for Dime Commercial Bancshares to see how Dime Commercial Bancshares could turn repricing, funding pressure, and credit trends into accelerating earnings power.

Banc of California (BANC)
Overview: Banc of California is a US bank holding company focused on traditional lending and treasury services for businesses and affluent clients.
Operations: Banc of California generates about US$690 million in revenue from commercial banking activities entirely within the United States.
Market Cap: US$2.9b
Banc of California fits this US financials screen as a balance sheet driven lender where higher policy rates can influence earnings through core deposits and loan pricing.
"The ongoing shift to digital financial services across all demographics is accelerating Banc of California's ability to attract new customers, reduce its customer acquisition and operating costs, and expand core deposit growth, driving improved efficiency, net interest margins, and sustained earnings growth."
The real test comes if one unresolved credit and capital swing changes how much of that extra interest income actually reaches the bottom line.
If that credit and capital swing is what you are weighing, read the full narrative for Banc of California to see whether Banc of California’s digital momentum is masking bigger earnings drivers.

Seeking Fresh Alternatives Before They Fly
Fresh ideas do not stay under the radar for long. Breakout momentum can be identified quickly, and attractive entry points may become scarce. Scan these curated picks now to review opportunities at an earlier stage.
- Review resilient balance sheets before momentum traders respond by running the list of solid balance sheet and fundamentals (23 results).
- Evaluate income streams that could help support portfolios while prices move by scanning the 7 dividend fortresses.
- Monitor potential early movers in a rapidly evolving field by tracking the 88 AI infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com