
BioNTech (BNTX) Could Be 19% Undervalued On Vaccine Approval And Phase 3 Data
BioNTech (BNTX) is back in focus after two clinical milestones. Health Canada authorized its Omicron XFG adapted COMIRNATY COVID-19 vaccine, and new Phase 3 data for gotistobart in squamous lung cancer attracted fresh investor attention.
Despite the clinical momentum, BioNTech’s share price tells a mixed story, with a 30 day share price return down 17.6% but a 90 day share price return up 6.5%, while the 1 year total shareholder return is roughly flat and the 5 year total shareholder return is down sharply.
Examine how BioNTech’s clinical news compares with other potential breakout biopharma opportunities by reviewing a curated set of 16 high quality undiscovered gems with similar R&D driven stories.
BioNTech’s chart now tells a different story from its clinical updates. Is the recent pullback signaling doubt in the underlying business, or simply a shift in sentiment that the current valuation no longer reflects?
Most Popular Narrative: 19% Undervalued
BioNTech closed at $96.06, while the most followed narrative puts fair value closer to $118.06, framing the recent pullback as a gap between pipeline expectations and current pricing rather than a verdict on the business.
Robust pipeline expansion in oncology, with multiple late-stage (Phase II/III) clinical trials for BNT327 and mRNA cancer immunotherapies across high-prevalence cancers (lung and breast), positions BioNTech to launch multiple new products. This is described as a potential driver of top-line revenue growth and as enhancing earnings visibility over the next several years. Strategic partnerships (notably with BMS, Genentech, and Regeneron) are cited as providing non-dilutive cash infusions, shared development costs, and accelerated global development of key assets, which is expected by this narrative to support stable R&D spend while improving profitability and EPS as milestone revenues materialize.
See why 71 investors see BioNTech as 19% undervalued.
Result: Fair Value of $118.06 (UNDERVALUED)
Still, the BioNTech story can quickly shift if Comirnaty demand erodes faster than expected or if key oncology trials deliver weaker outcomes than hoped.
Find out about the key risks to this BioNTech narrative.
Another View on BioNTech’s Valuation
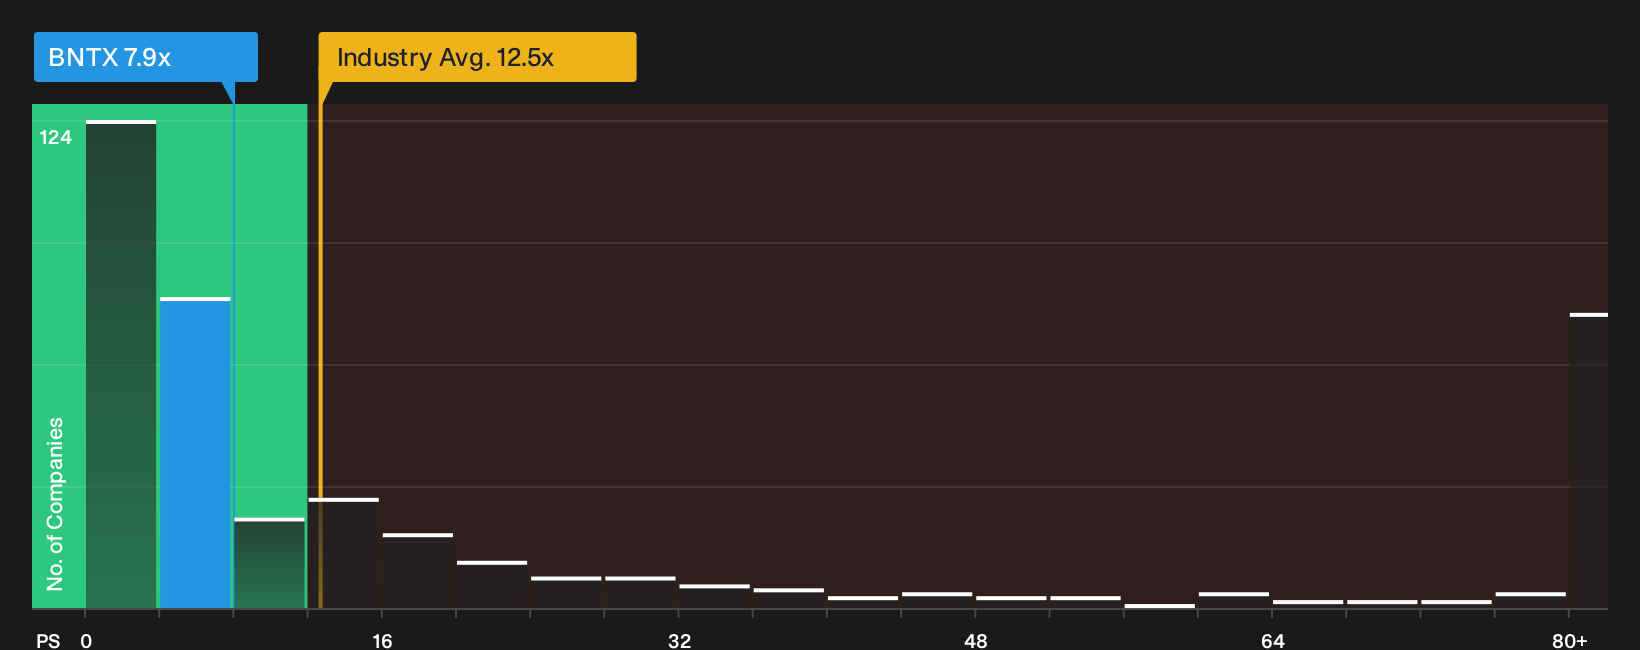
The first storyline paints BioNTech as roughly 19% undervalued against a fair value of $118.06, yet the simple P/S math sends a different message. The stock trades at 7.9x sales while the fair ratio sits closer to 6.6x, which implies investors are already paying a premium to where that ratio could migrate.
That gap looks even starker against the US Biotechs industry at 12.5x and peers at 10.5x P/S. BioNTech screens cheaper than the group but richer than its own fair ratio. The key question is whether you view that wedge as valuation risk that still needs to unwind or a pricing quirk you are comfortable owning.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Looking for more BioNTech investment ideas?
If BioNTech has your attention, do not stop with a single ticker. Broader context across sectors and styles can sharpen your judgement before committing fresh capital.
Use the Simply Wall Street Screener to pressure test your thinking against other opportunities and avoid leaving potential ideas on the table.
- Target potential mispricings by reviewing a curated pool of quality companies that screen as attractively valued through the 35 high quality undervalued stocks.
- Prioritise resilience by scanning financially robust businesses with clean balance sheets using the list of solid balance sheet and fundamentals (23 results).
- Hunt for opportunities the crowd may be overlooking by checking the market for 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com