
Ulta Beauty (ULTA) Could Be 14% Undervalued After Strong Q2 And Softer Outlook
Ulta Beauty (ULTA) is back in focus after management flagged a slower pace of comparable sales growth for the second half of 2026, even though Q2 results topped revenue and earnings expectations.
Recent price action reflects that tension between strong reported results and softer guidance. Ulta Beauty’s share price has climbed 16.3% over the past 90 days but remains down 12.8% year to date, while the 3-year total shareholder return of 35.7% points to longer term momentum that contrasts with this year’s more cautious sentiment.
Spot 35 high quality undervalued stocks that share some of Ulta Beauty’s quality traits but are still priced as if the recent caution around consumer demand will linger.Ulta Beauty now trades at US$540.98 against a mean analyst target of US$630.64 and an intrinsic value estimate that implies a premium. Which reference point best reflects fair value after the recent swing?
Most Popular Narrative: 13.8% Undervalued
On the most followed view, Ulta Beauty is worth $627.25 per share, which sits above the last close at $540.98 and frames the recent pullback as a valuation gap rather than a reset in the story.
The widening of Ulta's assortment, particularly through exclusive brand launches, key partnerships with in-demand emerging brands, and the rollout of a curated online marketplace, positions the company to attract Gen Z and Millennials, increase basket sizes, and capture higher-margin sales, benefiting both revenue and gross margins.
See why 74 investors see Ulta Beauty as 14% undervalued.
This fair value estimate of $627.25 uses a discount rate of 8.29% and builds in revenue growth assumptions of about 5.4% a year with profit margins near 9.5%. Analysts behind this narrative are effectively saying Ulta Beauty can keep compounding earnings at a moderate pace while sustaining a premium return profile, helped by loyalty depth, wellness expansion, and international add-ons rather than aggressive top line forecasts.
Relative to that framework, the current share price sits at a roughly 14% discount to the narrative fair value, while still implying a P/E that some investors may compare with the broader US Specialty Retail group. The narrative hinges less on multiple expansion and more on the idea that record loyalty membership, high quality earnings, and very strong forecast return on equity of 40.4% in three years justify paying above the internal fair P/E of 16.6x highlighted in separate valuation checks.
Result: Fair Value of $627.25 (UNDERVALUED)
Still, the Ulta Beauty narrative depends on higher margin wellness and digital growth helping to offset risks from rising store costs and the planned loss of the Target partnership.
Find out about the key risks to this Ulta Beauty narrative.
Another View: Ulta Beauty Looks Expensive On Earnings
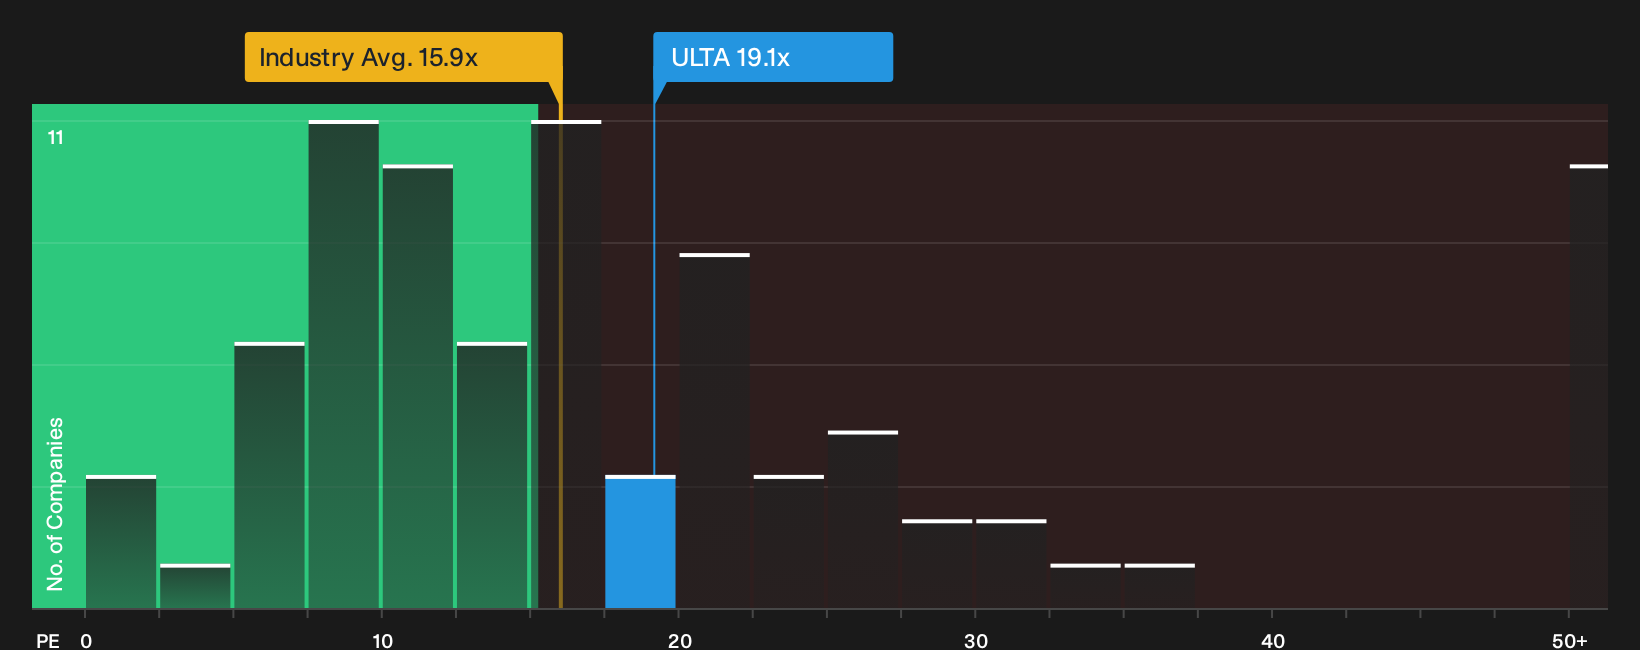
The narrative fair value paints Ulta Beauty as 13.8% undervalued. A simple P/E check tells a different story. The stock trades on 19.1x earnings, above both the US Specialty Retail average of 15.9x and its own fair ratio of 16.6x, which points to less margin for error if sentiment cools.
That gap suggests the share price already bakes in a quality premium, while the fair ratio is a level the multiple could drift toward if growth or returns disappoint. The question for investors is whether Ulta Beauty’s high returns and brand strength are enough to keep that premium in place.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Strong opinions run both ways in this Ulta Beauty debate, so move quickly through the numbers, charts, and narratives, then weigh the 2 key rewards
Looking for more investment ideas beyond Ulta Beauty?
Do not stop at Ulta Beauty. Fresh ideas matter, and the right watchlist today can shape the returns you look back on in a few years.
- Target resilience in rocky markets by scanning a 30 resilient stocks with low risk scores that screens for businesses aiming to combine steadier fundamentals with lower overall risk profiles.
- Hunt for quality at a discount through a 16 high quality undiscovered gems that surfaces under-followed companies with strong underlying numbers that many portfolios still ignore.
- Prioritize financial strength first and build a shortlist using a list of solid balance sheet and fundamentals (23 results) so you focus on companies where debt loads and cash positions look more robust.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com