
What Is Drawing Fresh Attention To Vita Coco Company (COCO)?
Vita Coco Company (COCO) has drawn fresh attention after recent trading left the stock down about 12% over the past month and roughly 33% lower over the past 3 months.
Despite that recent sell-off, Vita Coco Company's 1-year total shareholder return of 40.5% and 3-year total shareholder return of about 2.1x suggest long-term holders have still seen strong gains, even as the 90-day share price return has faded 32.7% and near-term momentum has cooled.
Scan how Vita Coco Company's pullback compares with other consumer stocks that our research team has already filtered for balance sheet strength and fundamentals in the list of solid balance sheet and fundamentals (23 results).
This pullback in Vita Coco Company could be read as a verdict on the coconut water business or as a sharp swing in sentiment. The valuation numbers now need to show which story fits.
Most Popular Narrative: 33% Undervalued
Vita Coco Company last closed at $55.82, while the most followed narrative framework points to a fair value near $83.56, using a 7.11% discount rate and detailed assumptions on revenue, margins, and capital allocation to bridge that gap.
Ongoing expansion into new product adjacencies (such as Vita Coco Treats and coconut milk-based beverages) is creating new consumption occasions and diversifying revenue streams, supporting topline growth and potentially enhancing gross margins with premium offerings. Heightened investment in international markets (notably Europe) is resulting in accelerating sales growth and market share gains, with management expecting international revenues to ultimately rival the Americas business, thus significantly impacting consolidated revenues and earnings power.
See why 24 investors see Vita Coco Company as 33% undervalued.
Result: Fair Value of $83.56 (UNDERVALUED)
Still, Vita Coco Company faces real pressure points, including tariff risk on coconut imports and volatility in freight costs that could squeeze margins if conditions turn less favorable.
Find out about the key risks to this Vita Coco Company narrative.
Another View: What Multiples Say About Vita Coco Company
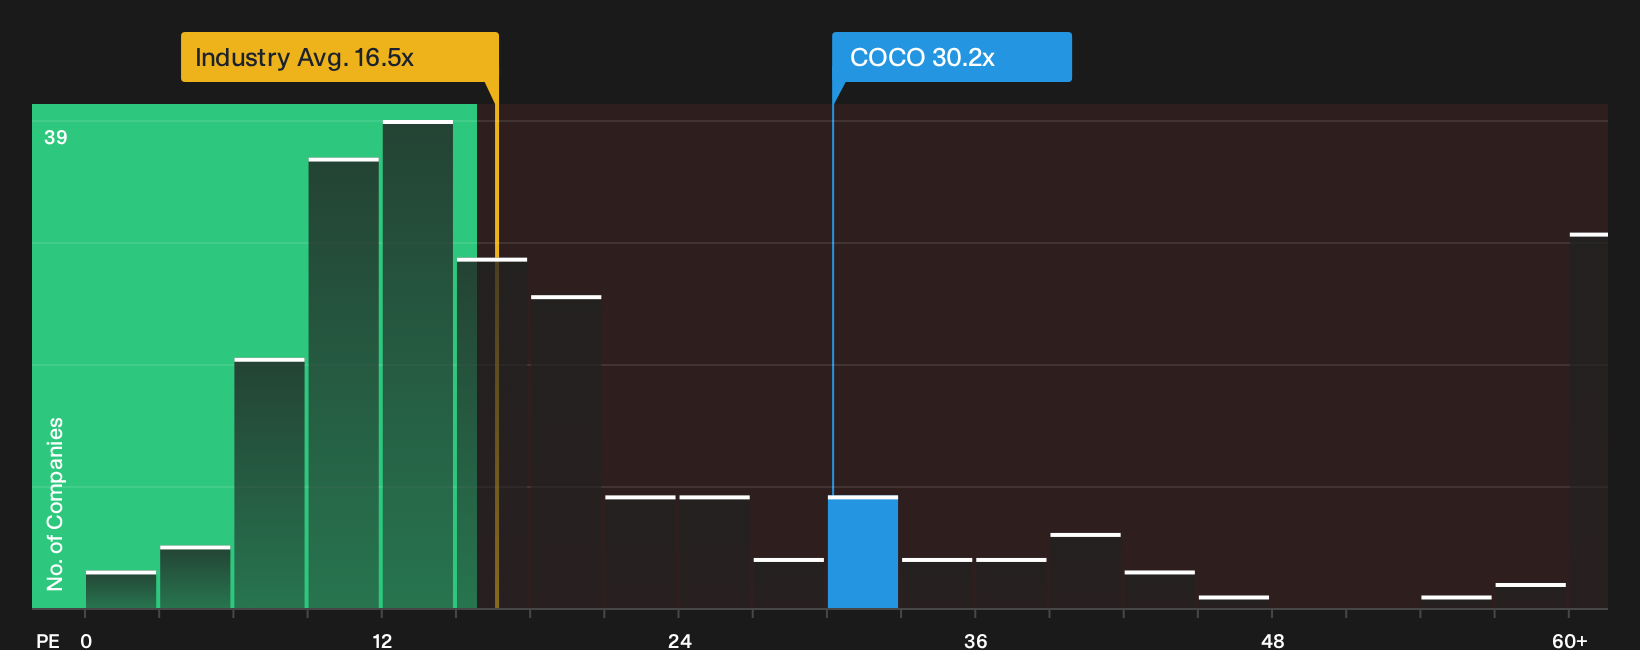
That 33% discount to the narrative fair value for Vita Coco Company leans heavily on forward cash flows and discount rates. The current P/E of 30.2x is almost double the global Beverage industry at 16.5x and sits well above the fair ratio of 19.3x, which suggests investors are already paying up for growth and quality. If the market shifted closer to that fair ratio or even toward the sector average, the share price would point to far less upside than the DCF style work implies. The key question is which story investors might lean on when sentiment swings next.
For a closer look at how this pricing gap could close, and what that might mean for risk and opportunity, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the tone so far feels split between caution and optimism, that is the point. It helps to move quickly and test the numbers yourself against the 4 key rewards
Looking for more investment ideas beyond Vita Coco Company?
Do not stop your research with Vita Coco Company. The screener can help you spot fresh setups and avoid opportunities slipping away while you wait.
- Target potential mispricing by scanning a focused set of companies through the 35 high quality undervalued stocks.
- Prioritise resilience by filtering candidates that pass strict balance sheet checks using the 30 resilient stocks with low risk scores.
- Hunt for early-stage opportunities by reviewing a curated group of smaller stocks in the 9 elite penny stocks with strong financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com