
Pilgrim's Pride (PPC) Expands In U.K. Ready Meals As Undervalued Narrative Holds
Pilgrim's Pride (PPC) is in focus after Pilgrim’s Europe agreed to produce Asian-inspired frozen ready meals for Associated British Foods’ Patak’s and Blue Dragon brands in a licensing partnership targeting the U.K. market.
Against this partnership backdrop, Pilgrim's Pride is trading at US$29.85, with the share price up 12.09% over the past 90 days but down 25.13% year to date. Long term total shareholder return over three and five years remains positive at 54.48% and 23.64% respectively, suggesting recent momentum has softened even as longer run holders are still ahead.
Scan beyond Pilgrim's Pride and see how other protein and food producers with resilient balance sheets are positioned using our hand picked list of solid balance sheet and fundamentals (23 results)
Recent losses this year sit awkwardly beside Pilgrim's Pride's stronger multi year returns. For anyone eyeing the recent pullback, it may be worth considering whether to step in now or wait for a clearer margin of safety.
Most Popular Narrative: 11% Undervalued
On the most followed view of Pilgrim's Pride, a fair value of $33.44 sits above the recent $29.85 close, pointing to a valuation gap that analysts justify using detailed revenue and margin forecasts discounted at 7.11%.
The company and the broader industry are benefiting from robust growth in global chicken demand, both due to expanding middle classes in emerging markets and the growing affordability gap between chicken and other proteins like beef and pork. If investors are overestimating the durability or pace of this demand, for instance by overlooking potential substitution pressure from alternative proteins or cyclical demand slowdowns, it could result in unrealistically high revenue growth expectations.
See why 16 investors see Pilgrim's Pride as 11% undervalued.
Result: Fair Value of $33.44 (UNDERVALUED)
Still, Pilgrim's Pride depends on chicken demand staying resilient and on grain and feed costs not moving against it in a way that current models might underplay.
Find out about the key risks to this Pilgrim's Pride narrative.
Another View on Pilgrim's Pride Valuation
The narrative around Pilgrim's Pride leans on a fair value of $33.44 based on future earnings, yet the SWS DCF model points to a future cash flow value of $25.85, which sits below the current $29.85 share price and suggests the stock screens as overvalued on this lens. Which story do you trust more: the earnings path or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
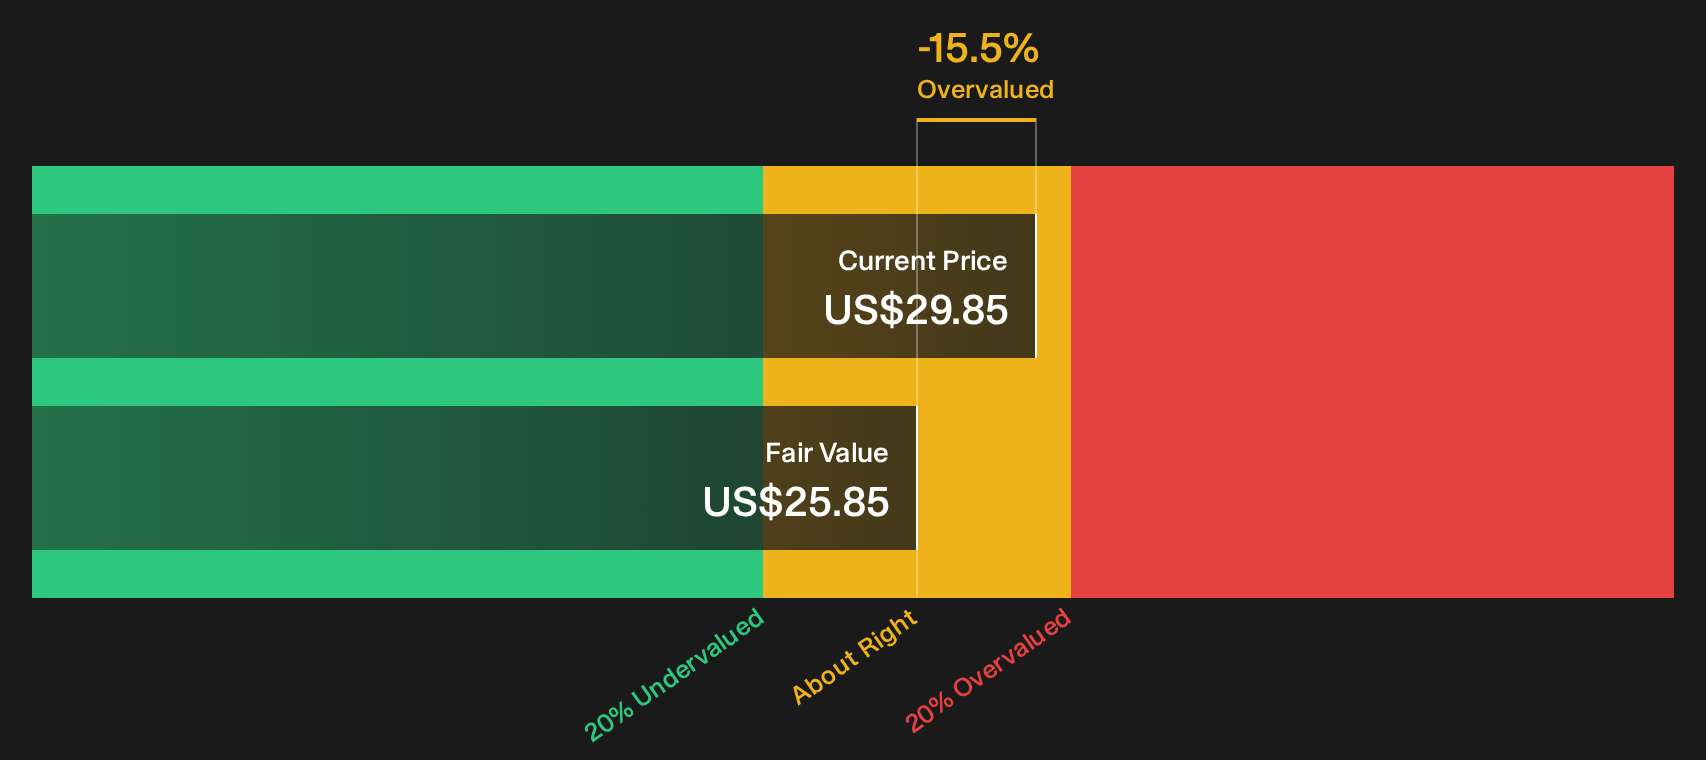
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Pilgrim's Pride for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Pilgrim's Pride valuation, sentiment and risks make this a moment to move quickly, review the evidence and test your own thesis. To weigh both sides in one place, start with the 3 key rewards and 3 important warning signs.
Looking for more Pilgrim's Pride sized investment ideas?
Set yourself up with a stronger watchlist by scanning for stocks that match your risk, income, and value preferences before the next move arrives.
- Target durable balance sheets and healthier fundamentals by running a focused screen through the list of solid balance sheet and fundamentals (23 results).
- Hunt for mispriced opportunities by filtering for quality businesses that trade below estimated worth using the 35 high quality undervalued stocks.
- Prioritise reliable income streams by zeroing in on companies offering stronger yields and stability via the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com