
3 Undervalued European Small Caps With Recent Insider Buying
The European market has recently experienced volatility, with the pan-European STOXX Europe 600 Index ending the week down amid escalating Middle East tensions and fluctuating energy prices. Despite these challenges, opportunities may arise in small-cap stocks that demonstrate strong fundamentals and potential resilience, particularly those with recent insider buying activity.
Top 10 Undervalued Small Caps With Insider Buying In Europe
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Genus | 4.9x | 2.1x | 40.51% | ★★★★★★ |
| Franchise Brands | 27.7x | 2.0x | 46.81% | ★★★★☆☆ |
| Trifast | NA | 0.5x | 15.60% | ★★★★☆☆ |
| Saniona | 7.5x | 3.3x | 29.82% | ★★★★☆☆ |
| Linc | 12.6x | 13.0x | 31.77% | ★★★★☆☆ |
| Vistry Group | 6.0x | 0.2x | -14.71% | ★★★☆☆☆ |
| Eurocell | 22.6x | 0.3x | 48.19% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.8x | 20.20% | ★★★☆☆☆ |
| KlaraBo Sverige | 6.8x | 2.6x | -161.03% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -215.84% | ★★★☆☆☆ |
Let's dive into some prime choices out of from the screener.
Genus (LSE:GNS)
Simply Wall St Value Rating: ★★★★★★
Overview: Genus is a global leader in animal genetics, focusing on the development and supply of breeding animals and products for livestock farmers, with a market cap of approximately £2.50 billion.
Operations: Genus derives its revenue primarily from Genus PIC and Genus ABS, with the latter contributing approximately £299.80 million. The company has experienced fluctuations in its gross profit margin, peaking at 69.75% in March 2026 before reaching 100% in June and September of the same year. Operating expenses have varied significantly, with a notable increase to £578.2 million in recent periods, impacting net income margins which reached up to 43.35%.
PE: 4.9x
Genus, a smaller European company, has demonstrated significant insider confidence with share purchases over the past year. Despite their reliance on external borrowing for funding, which poses higher risk compared to customer deposits, they reported impressive net income growth from £19.3 million to £285.3 million for the year ending June 2026. However, it's crucial to note that earnings are forecasted to decline by an average of 46.6% annually over the next three years.
- Get an in-depth perspective on Genus' performance by reading our valuation report here.
Understand Genus' track record by examining our Past report.
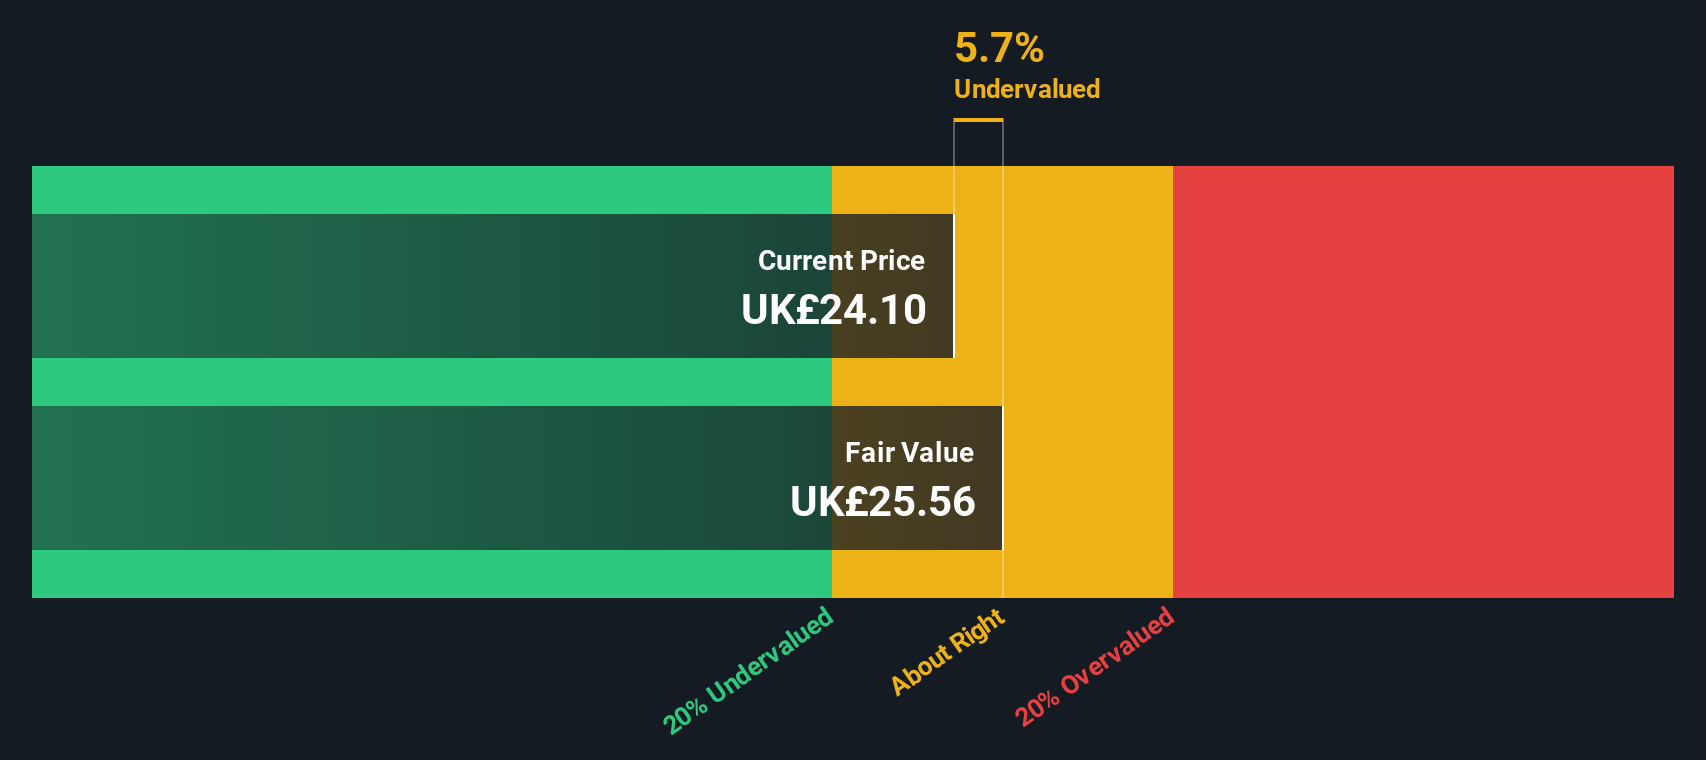
Supermarket Income REIT (LSE:SUPR)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Supermarket Income REIT is a real estate investment trust focusing on acquiring and managing supermarket properties across the UK, with a market capitalization of approximately £1.24 billion.
Operations: The company generates revenue primarily through its investments in supermarket property assets, with a recent revenue figure of £115.04 million. It consistently achieves a gross profit margin of 100%, indicating no direct costs associated with its revenue streams. Operating expenses, including general and administrative costs, have varied over time but recently stood at £7.66 million. The net income margin has shown fluctuations, reflecting changes in non-operating expenses and overall profitability dynamics over different periods.
PE: 13.3x
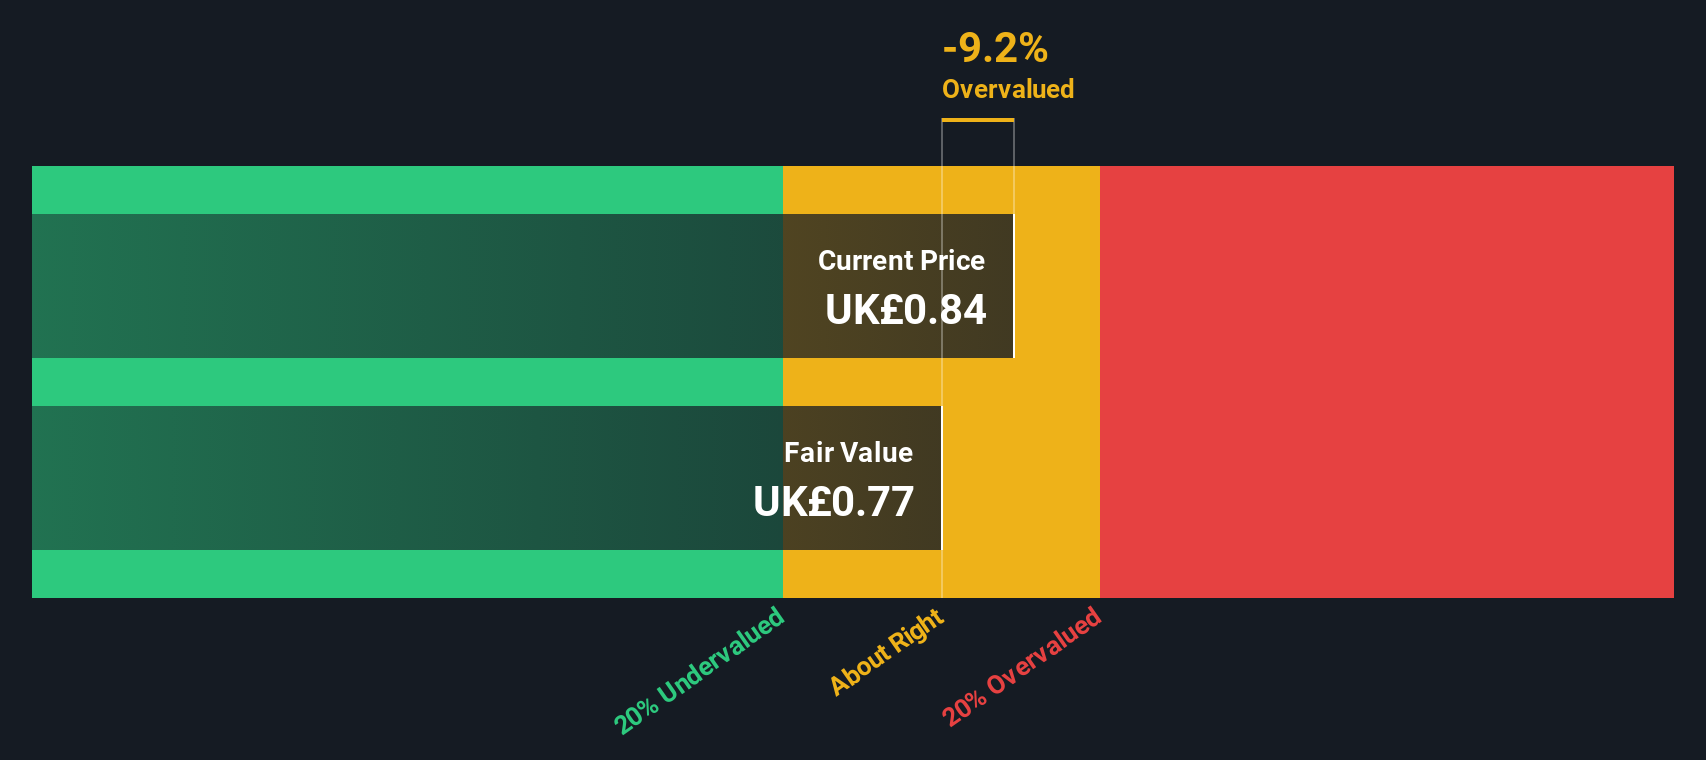
Supermarket Income REIT is navigating the European small-cap landscape with strategic acquisitions and financial maneuvers. They recently reported a net income of £85.93 million for the year ending June 30, 2026, up from £61.53 million previously, despite a drop in sales to £100.49 million from £113.23 million. Their acquisition of nine grocery assets for approximately £216 million highlights their growth ambitions, funded by a recent equity raise and debt refinancing totaling £445 million to lower borrowing costs and extend debt maturity until 2028. Insider confidence is evident as insiders have been purchasing shares over the past months, signaling potential optimism about future prospects in grocery real estate investment.
Invisio (OM:IVSO)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Invisio specializes in developing advanced communication and hearing protection systems primarily for the aerospace and defense sectors, with a market capitalization of approximately SEK 11.68 billion.
Operations: The company's revenue is primarily derived from the Aerospace & Defense sector, amounting to SEK 1.92 billion. The gross profit margin has shown fluctuations, with a recent figure of 56.35%. Operating expenses are significant, including substantial allocations for sales and marketing as well as research and development activities.
PE: 42.4x
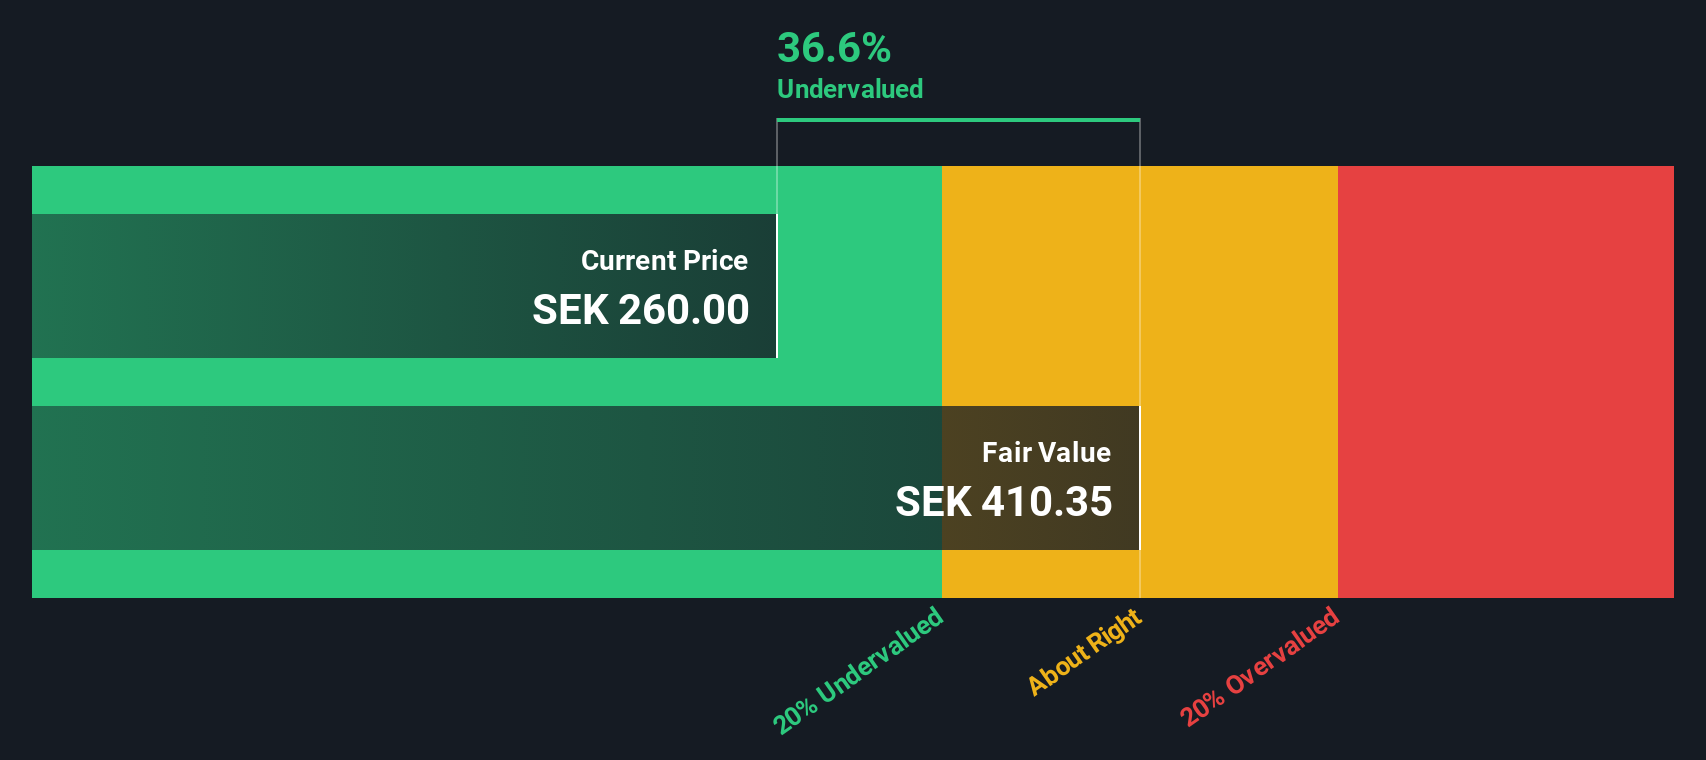
Invisio, a company known for its tactical communication solutions, has caught the eye with insider confidence as their President & CEO purchased 20,000 shares worth approximately SEK 4.9 million in August 2026. This move suggests belief in future growth prospects. The company's recent deal with the Canadian Armed Forces could potentially bring up to SEK 450 million over five years, enhancing revenue streams alongside a reported earnings growth of nearly 35% annually. However, reliance on external borrowing remains a risk factor to consider.
- Unlock comprehensive insights into our analysis of Invisio stock in this valuation report.
Assess Invisio's past performance with our detailed historical performance reports.
Next Steps
- Click through to start exploring the rest of the 34 Undervalued European Small Caps With Insider Buying now.
- Have you diversified into these companies? Leverage the power of Simply Wall St's portfolio to keep a close eye on market movements affecting your investments.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com