
Anterix (ATEX) Could Be 10% Undervalued After $250 Million Buyback Plan
Anterix (ATEX) has put a US$250 million share repurchase program in place, running through September 22, 2029, after its Board approved a new buyback plan earlier this month.
That repurchase decision comes after a sharp run in Anterix shares this year, with a year-to-date share price return of 246.33% and a 1-year total shareholder return of 232.28%. However, the 30-day share price return has fallen 17.44%, indicating strong longer-term momentum alongside shorter-term volatility.
Scan beyond Anterix and see how other companies are handling capital returns with our curated list of 35 high quality undervalued stocks, which could merit a closer look alongside this buyback story.
Anterix has soared over the past year, then slipped over the past month, while management now commits up to US$250 million to buybacks. Does that mix still tip the risk reward balance toward new buyers, or not?
Most Popular Narrative: 10% Undervalued
The most followed valuation narrative for Anterix puts fair value at $86.00, a little above the last close of $76.99, which frames the new $250 million repurchase capacity in the context of a stock seen as modestly undervalued on that view.
Although utilities are showing interest in private broadband networks as they modernize grids, Anterix still has roughly 85% of its spectrum yet to be monetized. Any delay in converting that interest into contracts could slow the realization of expected spectrum value and defer cash inflows and earnings.
See why 0 investors see Anterix as 10% undervalued.
Result: Fair Value of $86.00 (UNDERVALUED)
Still, the Anterix story could be knocked off course if utilities slow 900 MHz contract signings or if TowerX and CatalyX adoption lags current expectations.
Find out about the key risks to this Anterix narrative.
Another View On Anterix Valuation
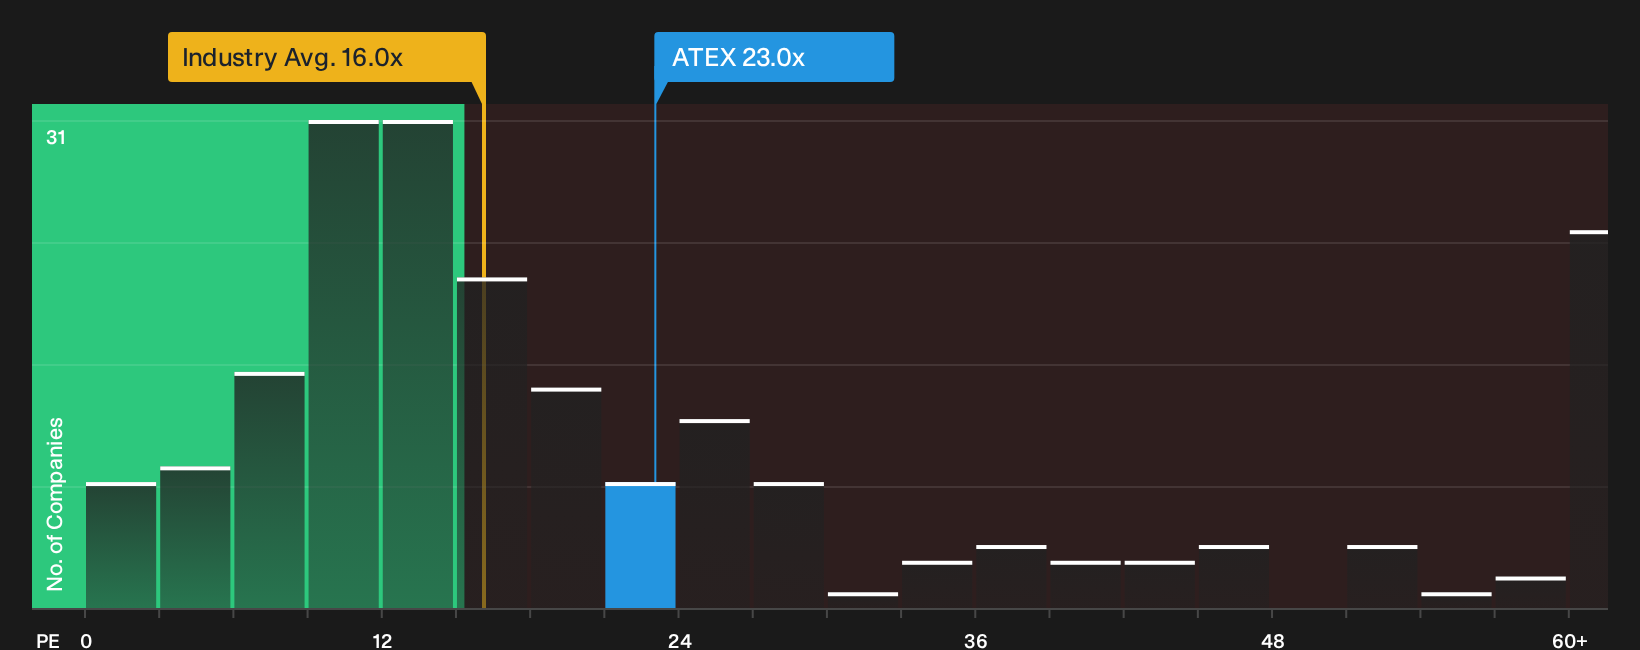
The fair value narrative around Anterix leans on analyst targets and long term earnings assumptions. A quick look at the current P/E tells a different story. The stock trades at about 23x earnings, while the internal fair ratio sits near 4.1x, which implies a far lower level the market could move toward if sentiment cools.
That gap is wide. It also compares awkwardly with the Global Telecom average of 16x, even though Anterix screens cheaper than a 39.7x peer group. For readers, the live question is whether the premium to the sector or the discount to peers matters more if earnings expectations shift again.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Anterix story so far feels finely balanced between promise and risk, move quickly, review the details, and weigh both sides for yourself using 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Anterix?
If you are weighing Anterix today, broaden your watchlist with fresh ideas surfaced by Simply Wall Street screeners that filter for quality, price and resilience.
- Target potential upside by scanning for under-followed value opportunities through the 16 high quality undiscovered gems that combine solid fundamentals with room for the story to develop.
- Guard your capital by focusing on resilient businesses using the 30 resilient stocks with low risk scores that filters for stocks with lower risk profiles and steadier fundamentals.
- Strengthen the core of your portfolio by reviewing companies with healthier finances via the list of solid balance sheet and fundamentals (23 results) that can better absorb shocks when conditions change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com