
3 British Undervalued Stocks To Own In September 2026
Calls to expand the UK’s national wealth fund into a major development bank have put fresh attention on where the next wave of domestic capital might flow. If more money starts chasing the same well known large caps, smaller British companies with solid balance sheets and overlooked track records could draw renewed interest. This piece highlights three such under the radar high quality UK stocks from our screener.
The three stocks below are a sample from our High Quality Undiscovered Gems idea, while the full screen surfaced three more UK companies with equally solid fundamentals and under followed stories that are not covered here.
If you want to identify and analyze those extra candidates for yourself, head straight to the High-Quality Undiscovered Gems screener.
Integrated Diagnostics Holdings (LSE:IDHC)
Integrated Diagnostics Holdings aligns with the High-Quality Undiscovered Gems theme through its specialist pathology and radiology platform, giving you direct exposure to a small cap healthcare operator that is building a wide test menu and imaging network across fast growing MENA markets.
Integrated Diagnostics Holdings runs a consumer-focused medical testing and imaging platform built around roughly 3,000 specialist pathology tests and radiology services across Egypt, Sudan, Nigeria and Saudi Arabia. The group earns about EGP 2,599 million from walk-in patients and EGP 5,258 million from contracts, and has a market value of about US$308 million.
"The decision to acquire the remaining 49% stake in the Saudi Arabian venture gives IDH full control over the entity, enabling more flexible execution of its growth strategy in a high-potential market, supporting revenue and possibly net margins as operations scale."
What happens if one unseen pressure on Integrated Diagnostics Holdings’ funding structure and capital costs shifts just as that growth plan accelerates?
If that funding pressure is what really shifts the story, read the full narrative for Integrated Diagnostics Holdings to see how Integrated Diagnostics Holdings could balance growth and risk.

Christie Group (AIM:CTG)
Christie Group is a £48 million small cap that advises, values and brokers hospitality, leisure and healthcare businesses through Christie & Co. It is a direct fit with the High-Quality Undiscovered Gems theme as it connects investors to under-the-radar hotels, pubs and care assets. Professional & Financial Services generate about £59.7 million, with Stock & Inventory Systems adding roughly £11 million.
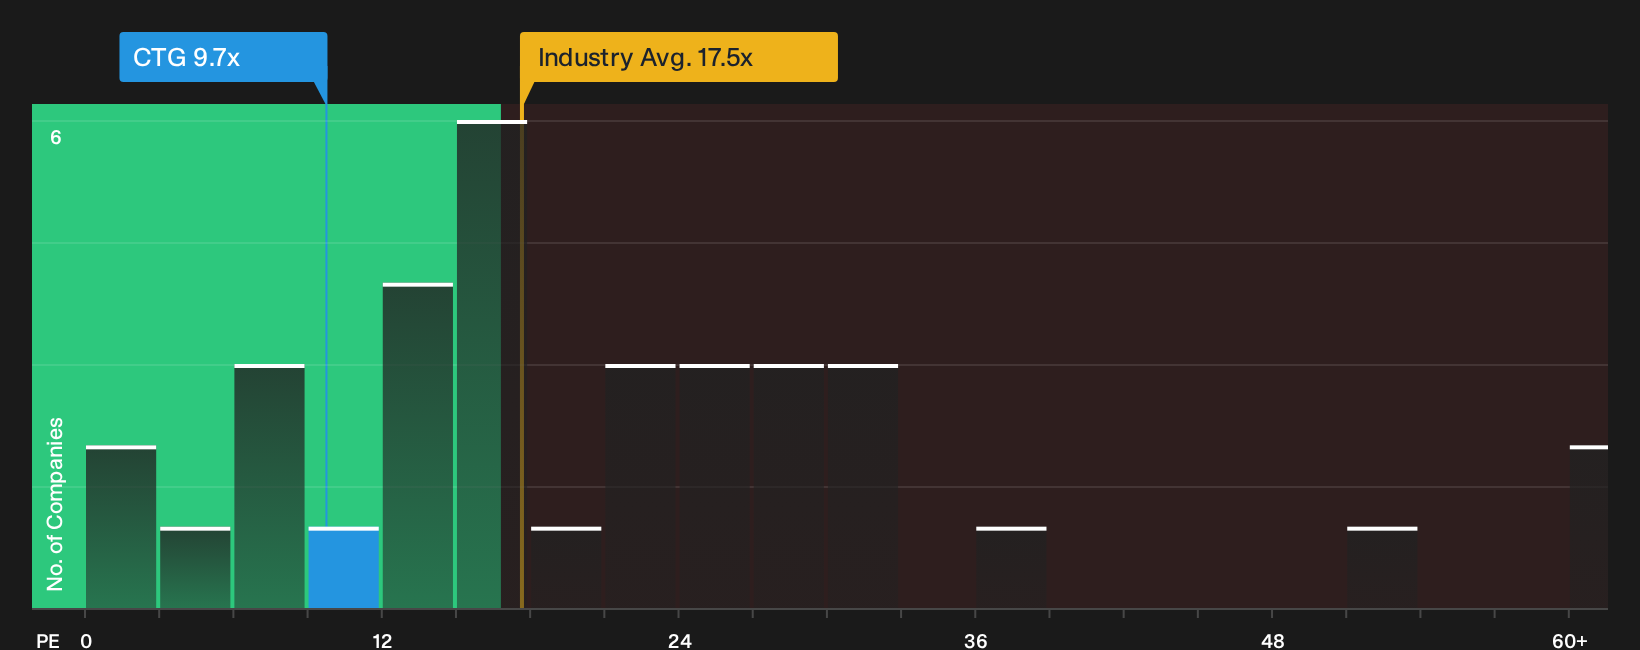
Christie Group taps into under followed hospitality and care assets through Christie & Co, backed by high quality earnings and a P/E below larger professional services peers. That mix of niche deal flow and modest valuation could matter a lot if one unseen pressure on how those transactions are funded starts to shift.
If that funding shift is what unlocks the next leg for Christie Group, review the analysis report for Christie Group to see how the pieces could reprice.
Serabi Gold (AIM:SRB)
Serabi Gold fits directly into the High-Quality Undiscovered Gems theme through its Palito complex and Coringa project, offering exposure to a small-cap producer with active gold output and exploration potential that many larger funds do not closely follow.
Serabi Gold focuses on gold mining and exploration in northern Brazil, generating about $179 million from this line and carrying a market cap near £206 million. Production and exploration are anchored by the Palito mining complex and Coringa project.
For investors who prefer underfollowed production stories rather than early stage prospects, Serabi Gold provides a live mine complex with room to grow, along with a development project that could change the scale of the business if operations progress as planned.
"The ramp-up of the Coringa mine from development to production is expected to increase Serabi Gold's overall production from 30,000-40,000 ounces to 60,000 ounces, enhancing revenue generation."
What may really move the needle from here could come down to how one less visible factor around future cost control and cash flow flexibility ultimately develops.
If that hidden cost tension is what really matters for Serabi Gold, read the full narrative for Serabi Gold to see how rising output could interact with cash flexibility.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first, and the best setups rarely stay under the radar for long. Before the next breakout gathers momentum and you are caught chasing, act now.
- Catch income workhorses before yields get compressed by latecomers by scanning the curated 1 dividend fortresses and spotting which payouts still look durable while it matters.
- Track the next wave of AI infrastructure momentum by combing through the hand picked 88 AI infrastructure stocks and seeing which enablers might move before headlines catch up.
- Position ahead of the next leg in precious metals by reviewing the filtered 36 elite gold producer stocks and shortlisting producers that still appear under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com