
SailPoint (SAIL) Links With Keeper Security, Is It Still 5% Overvalued?
The latest Keeper Security integration gives SailPoint (SAIL) a fresh hook for investors watching identity security platforms. Keeper’s SaaS Connector ties SailPoint’s governance tools directly into KeeperPAM’s privileged access management workflows.
Recent trading reflects that story. SailPoint’s share price return is up 53.96% over the past 90 days and 6.38% over 30 days, although the 1-year total shareholder return is down 14.19%. This suggests that short-term momentum is building while longer-term holders remain under water.
Scan how SailPoint compares with other identity and security platforms by checking hand picked opportunities across our 30 resilient stocks with low risk scores that aim to balance resilience with potential upside.
Bulls point to SailPoint’s recent rally, fresh integrations and double digit revenue growth. Bears focus on continued losses and a modest intrinsic discount. Which side does the current valuation actually support next?
Most Popular Narrative: 5% Overvalued
SailPoint last closed at $19.83 against a narrative fair value of $18.90. The story currently prices in a small premium while still leaning on a discounted cash flow framework with an 8.54% discount rate.
Ongoing migration of legacy IdentityIQ customers to Identity Security Cloud, supported by flex licensing, unlocks two to three times more ARR per customer and structurally increases the subscription mix and earnings power.
See why 7 investors see SailPoint as 5% overvalued.
Result: Fair Value of $18.90 (OVERVALUED)
Still, the SailPoint narrative can crack if larger security platforms close the feature gap in identity, or if cloud migrations drag and delay the expected ARR uplift.
Find out about the key risks to this SailPoint narrative.
Another View on SailPoint’s Valuation
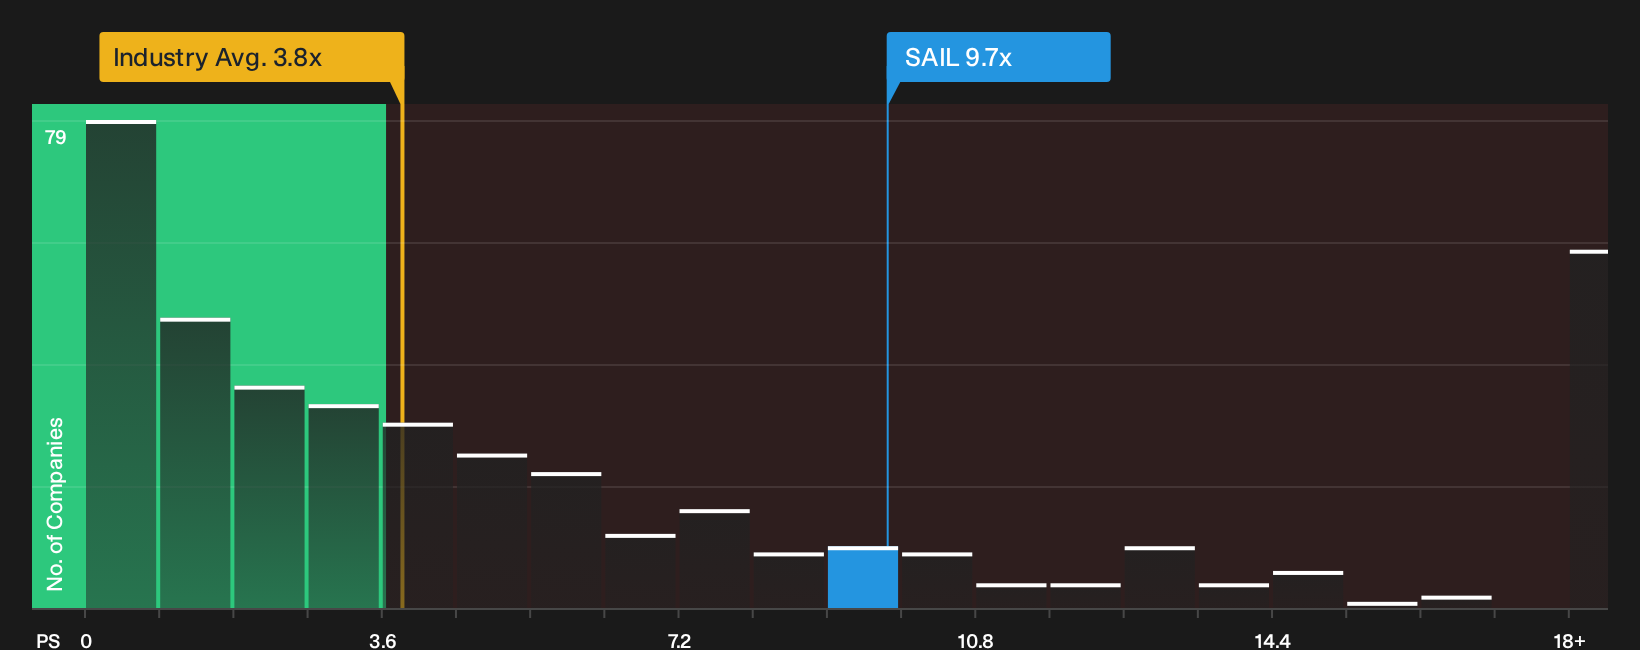
The earlier fair value of $18.90 leans on analyst earnings assumptions and future P/E. A second lens offers additional perspective. SailPoint currently trades on a P/S of 9.7x, versus a 3.8x industry average and a fair ratio of 6.6x that the market could move toward. That gap highlights valuation risk if sentiment cools.
For a closer look at how this pricing compares across peers and scenarios, check the See what the numbers say about this price — find out in our valuation breakdown..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SailPoint for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed on SailPoint after all this. If you want to move quickly from headline takeaways to your own verdict, start with the balance of 2 key rewards and 1 important warning sign.
Looking for more SailPoint investment ideas?
If SailPoint has your attention, broaden your watchlist now by scanning a few focused stock shortlists that surface different types of opportunities before other investors crowd in.
- Target value setups by reviewing the 35 high quality undervalued stocks that combine quality fundamentals with pricing that may not fully reflect them yet.
- Strengthen your core holdings by focusing on companies with robust finances using the list of solid balance sheet and fundamentals (23 results) tailored to resilient balance sheets and solid track records.
- Get ahead of the crowd by scanning the 16 high quality undiscovered gems that highlight high quality businesses still flying under most investors’ radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com