
3 Canadian AI Stocks With P S Under 1x
Big tech spending on AI infrastructure is helping keep US economic growth and inflation strong, and that ripple effect matters for Canadian artificial intelligence stocks that are still priced cheaply. Capital is flowing into AI hardware, software and cloud, yet many domestic players trade as if this surge is temporary. This article highlights three Canadian AI related stocks from our undervaluation screen that could merit a closer look.
The three undervalued AI stocks below are only a small sample from our wider screen, which surfaced 0 additional companies with equally compelling ChatGPT and artificial intelligence stories that are not covered here. To identify those extra opportunities and analyze them side by side, head straight to the Undervalued Artificial Intelligence/ AI Stocks screener.
Docebo (TSX:DCBO)
Docebo is a Toronto based educational software provider that builds cloud learning platforms for corporate training, with AI woven into its Harmony Search and analytics tools, and it generated about US$258.9 million from educational software on a market value of roughly CA$806 million.
Docebo matters for this AI focused screen because its learning platform uses machine intelligence not just as a bolt on feature but as a core part of how customers search, consume, and measure training content.
Rapid adoption of AI-driven features such as Harmony and Creati is positioning Docebo as an innovation leader, enabling enhanced personalization, automation, and productivity for customers; this supports long-term customer retention, upsell opportunities, and gross margin expansion.
What happens to that story hinges on how one quiet financial constraint shapes the next leg of its AI rollout and pricing power.
That quiet constraint is exactly what the full narrative for Docebo unpacks, showing how Docebo’s AI rollout, pricing power, and competitive position could be shifting under the surface.

Thinkific Labs (TSX:THNC)
Thinkific Labs runs a cloud learning commerce platform that blends online courses, communities and AI tools for creators and enterprises. It produces about $74 million from its core software offering and carries a market value near CA$82 million.
Thinkific Labs leans directly into the AI theme of this screen, because its learning commerce platform now embeds AI into course creation, content generation and personalised support in a way that shapes how instructors build and sell digital education.
Deep integration of artificial intelligence into both customer-facing features and internal operations is accelerating product development and enabling personalized, data-driven learning experiences, supporting product differentiation and enhancing customer retention, which is positive for recurring revenue and net margins.
A key issue from here is whether one pressure point in its shift toward larger customers helps margins or keeps them on hold.
Whether that shift tightens or stretches profitability is exactly what the full narrative for Thinkific Labs unpacks, including how AI driven upselling could reshape Thinkific Labs’ long term earnings mix.

NowVertical Group (TSXV:NOW)
NowVertical Group builds big data and analytics tools that plug directly into the AI and ChatGPT story through artificial intelligence, data science and MLOps services used for predictive recommendations and customer insights. It generates about $38 million from operations and has a market cap near CA$12 million.
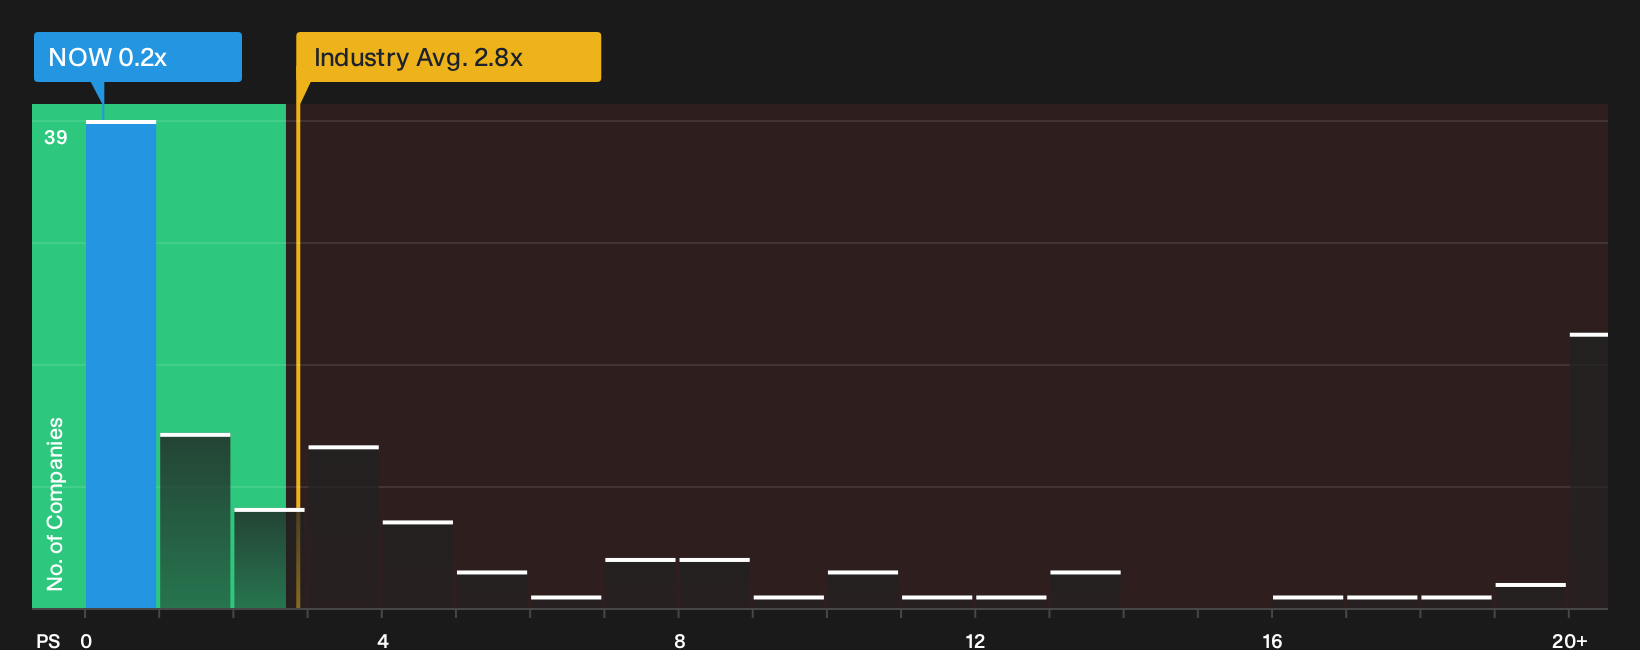
NowVertical Group gives you pure picks-and-shovels exposure to AI infrastructure, from MLOps pipelines to NOW SnowGraph customer insight tools, at a P/S near 0.2x, which is far below many Canadian software peers. The potential upside case depends on what happens to profitability once those AI workloads scale across its client base.
That profitability question is where the analysis report for NowVertical Group really earns a look, with the full NowVertical Group AI story laid out before the market catches up.
Curious About High Conviction Alternatives
Fresh ideas can move quickly. Some gain momentum before the crowd catches on, while others get caught dropping off radars. Scan these under the radar for now opportunities and consider them carefully.
- Target resilient compounding potential by scanning the 8 resilient stocks with low risk scores and see which businesses still fly under most radars while the risk spotlight sits elsewhere.
- Hunt for durable income that can keep portfolios steady when sentiment swings by reviewing the curated 1 dividend fortresses before others focus on the same yields.
- Track the picks and shovels of the AI build out through the hand picked 88 AI infrastructure stocks while the market focus remains on headline chatbot stories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com