
How Driverless Truck Production Plans Will Impact Aurora Innovation Stock (AUR)
- Aurora Innovation outlined plans to scale production to 20 driverless trucks per week in Q4 2026. This plan is supported by second generation hardware that management expects will cut unit costs by more than 50% and transition the fleet from transportation as a service toward a driver as a service model by the end of 2027.
- The move to a driver as a service approach, backed by trucking partners like PACCAR, Volvo and International, shifts Aurora Innovation toward a more platform like model in which hardware, software and manufacturing partners work together to spread fixed development costs over a larger installed base of autonomous trucks.
- We will now look at how Aurora Innovation's investment narrative could shift as it targets 20 driverless trucks per week using cheaper hardware.
Aurora Innovation Investment Narrative Recap
To own Aurora Innovation, you need to believe driverless freight can scale from pilots to a real network that supports meaningful revenue and a path toward better unit economics. The plan to reach 20 driverless trucks per week in Q4 2026 with cheaper second generation hardware directly targets that goal. It gives a clearer operational bridge between today’s small US$5 million revenue base and a larger deployed fleet.
The biggest short term swing factor remains whether Aurora can hit its deployment and cost milestones without stretching a cash runway that currently extends into the second half of 2027. High quarterly operating losses and no near term profitability forecast keep funding risk elevated. This production plan matters because any delay in reaching positive gross profit could make future dilution more likely.
The recent focus on second generation hardware and the shift toward a driver as a service model ties closely to earlier commentary about using new hardware to lower unit costs by roughly 50%. That operational theme runs through the current story. The Fort Worth to El Paso route and planned Phoenix extension sit in the background as demand channels that may eventually soak up the extra capacity if rollouts stay on track.
For you as an investor, the critical link is execution. Can Aurora Innovation take these hardware cost reductions, convert OEM partnerships into automotive scale production, and do it on the current balance sheet? That is what sits behind analyst expectations of very high revenue growth and an unprofitable profile for at least three years. The news around scaled driverless production puts a spotlight on that execution risk and the timing of when, or if, losses start to narrow.
How Aurora Innovation’s Long Term Assumptions Stack Up
Aurora Innovation's narrative projects US$1.2b revenue and US$136.3 million earnings by 2029. This implies very large yearly revenue growth of 514.8% and an earnings improvement of about US$1.04b from a loss of US$900.0 million today.
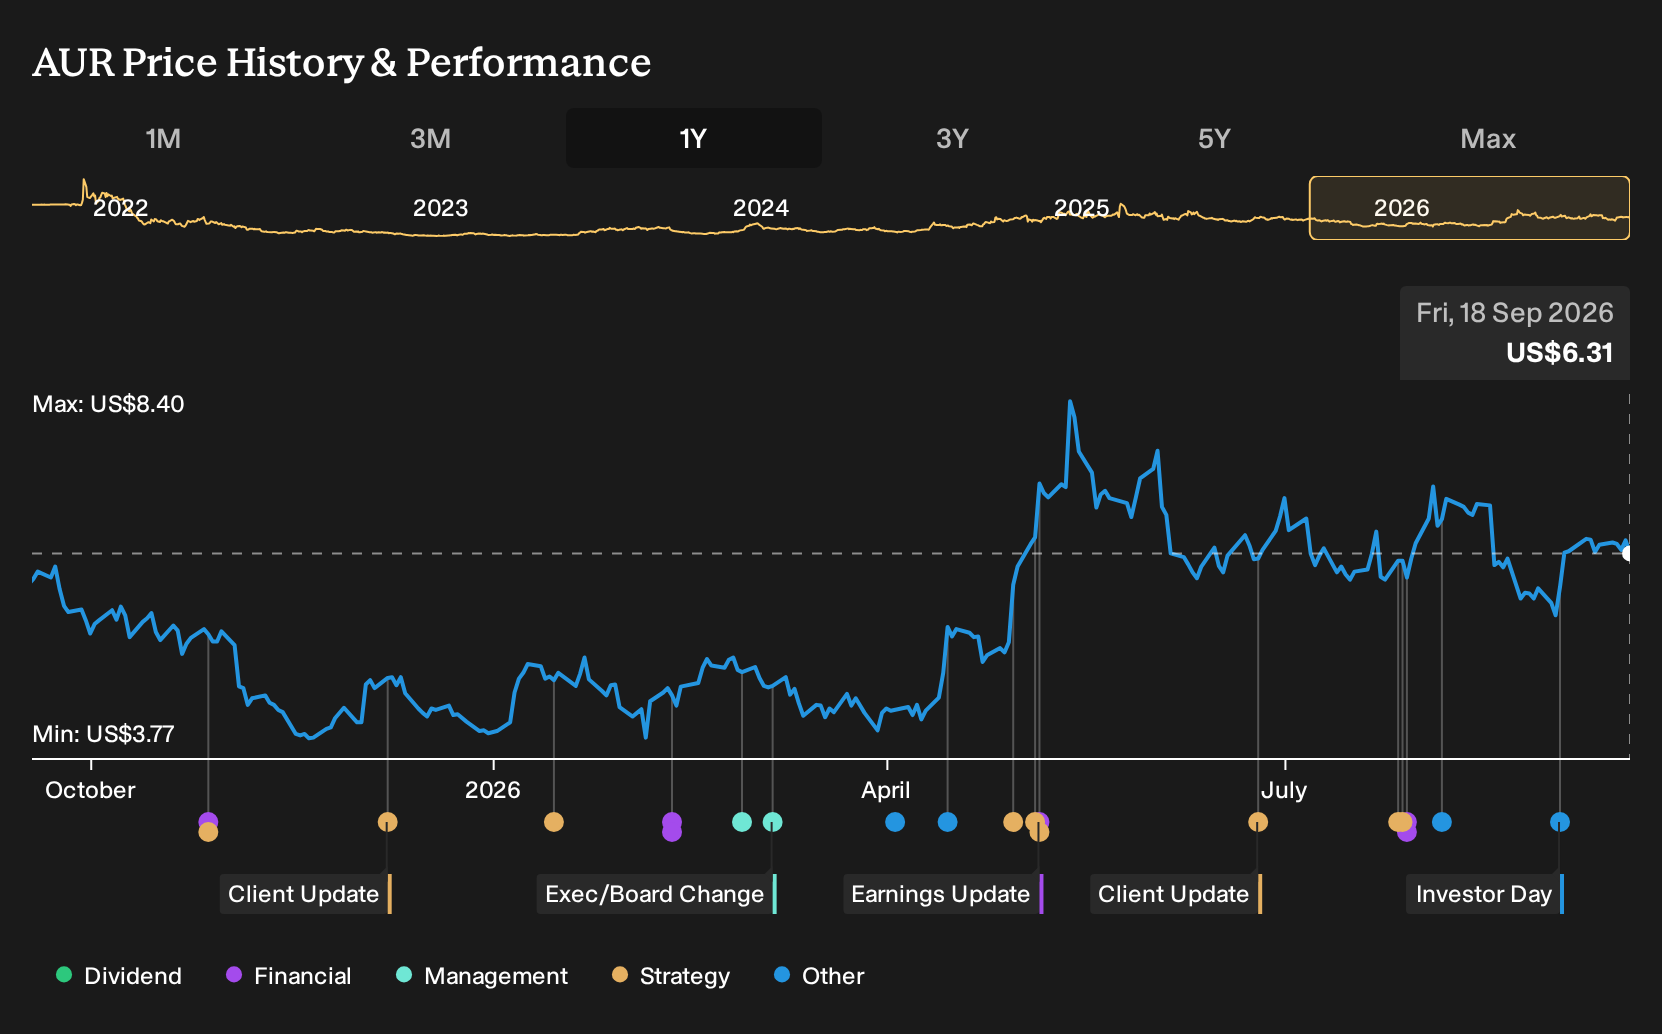
Uncover why Aurora Innovation's fair value indicates an 83% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Aurora Innovation leans into hardware as a major catalyst. The most optimistic analysts were already assuming revenue could reach about US$1.4b and earnings of roughly US$168.8 million by 2029, with a P/E above 300x. Those forecasts came before this production news, so you should expect opinions to shift and compare several scenarios yourself.
Explore 3 other Aurora Innovation fair value estimates, including one that suggests as much as 586% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Aurora Innovation research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Aurora Innovation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aurora Innovation's overall financial health at a glance.
Looking For More Investment Ideas Beyond Aurora Innovation?
If Aurora Innovation has sharpened your thinking about automation, it can help to line it up against other potential opportunities using the Simply Wall St Screener. You can quickly compare different themes, financial profiles and risk levels, then decide where you want to spend more research time.
- For investors hunting for strong balance sheets and resilient fundamentals, review the list of solid balance sheet and fundamentals (23 results) that may hold up better when conditions get tougher.
- If you are searching for quality businesses that the market might be overlooking, start with a curated pool of 16 high quality undiscovered gems that combine robust financials with less crowded tickers.
- For those who care most about capital preservation and smoother rides, filter for 30 resilient stocks with low risk scores and compare companies with lower risk scores to build a steadier watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com