
3 Oil And Gas Stocks Investors Are Watching As Sanctions Reshape Energy Supply
Sanctions on Russian energy have quietly redrawn the global oil and gas map, shifting trade routes, financing channels, and pricing power. That disruption can create pockets of opportunity for investors as capital and cargoes look for non-Russian suppliers. This article walks through three stocks from the Non-Russian Oil and Gas Producers screener that are closely exposed to the latest policy shock and explains how the same headlines could either help or hurt your portfolio.
The three stocks profiled below are just a first pass, and the full screen surfaced 12 more non Russian oil and gas producers with equally compelling narratives that do not fit into a single article. To go straight to the source, analyze, filter, and identify your highest conviction ideas directly inside the Non-Russian Oil and Gas Producers screener.
Ovintiv (OVV)
Ovintiv gives you pure-play exposure to North American oil and gas, in the middle of a world that is steadily leaning on non Russian producers for secure supply.
Ovintiv Inc. is a Denver based oil and gas producer focused on large shale plays in the U.S. Permian and Anadarko and Canada’s Montney, with USA Operations contributing about US$6.0b of revenue and Canadian Operations about US$3.6b, and the stock valued around US$17.2b.
"Ovintiv's diversified North American natural gas exposure, reinforced by new marketing agreements (e.g., JKM and Chicago-linked contracts) and positioning for LNG exports, supports volume stability and higher realized prices, positively impacting revenue consistency and margin resilience."
What really matters now is how one emerging pressure on Ovintiv’s cost base and pricing power shapes those future margins investors are watching.
That margin story is only the start, and the full narrative for Ovintiv outlines how Ovintiv’s contracts, capital choices, and LNG exposure could amplify or limit that pricing power shift.

Topaz Energy (TSX:TPZ)
Topaz Energy gives you a different angle on non Russian oil and gas, leaning on royalties and midstream assets that ride on Canadian production volumes rather than owning every barrel directly.
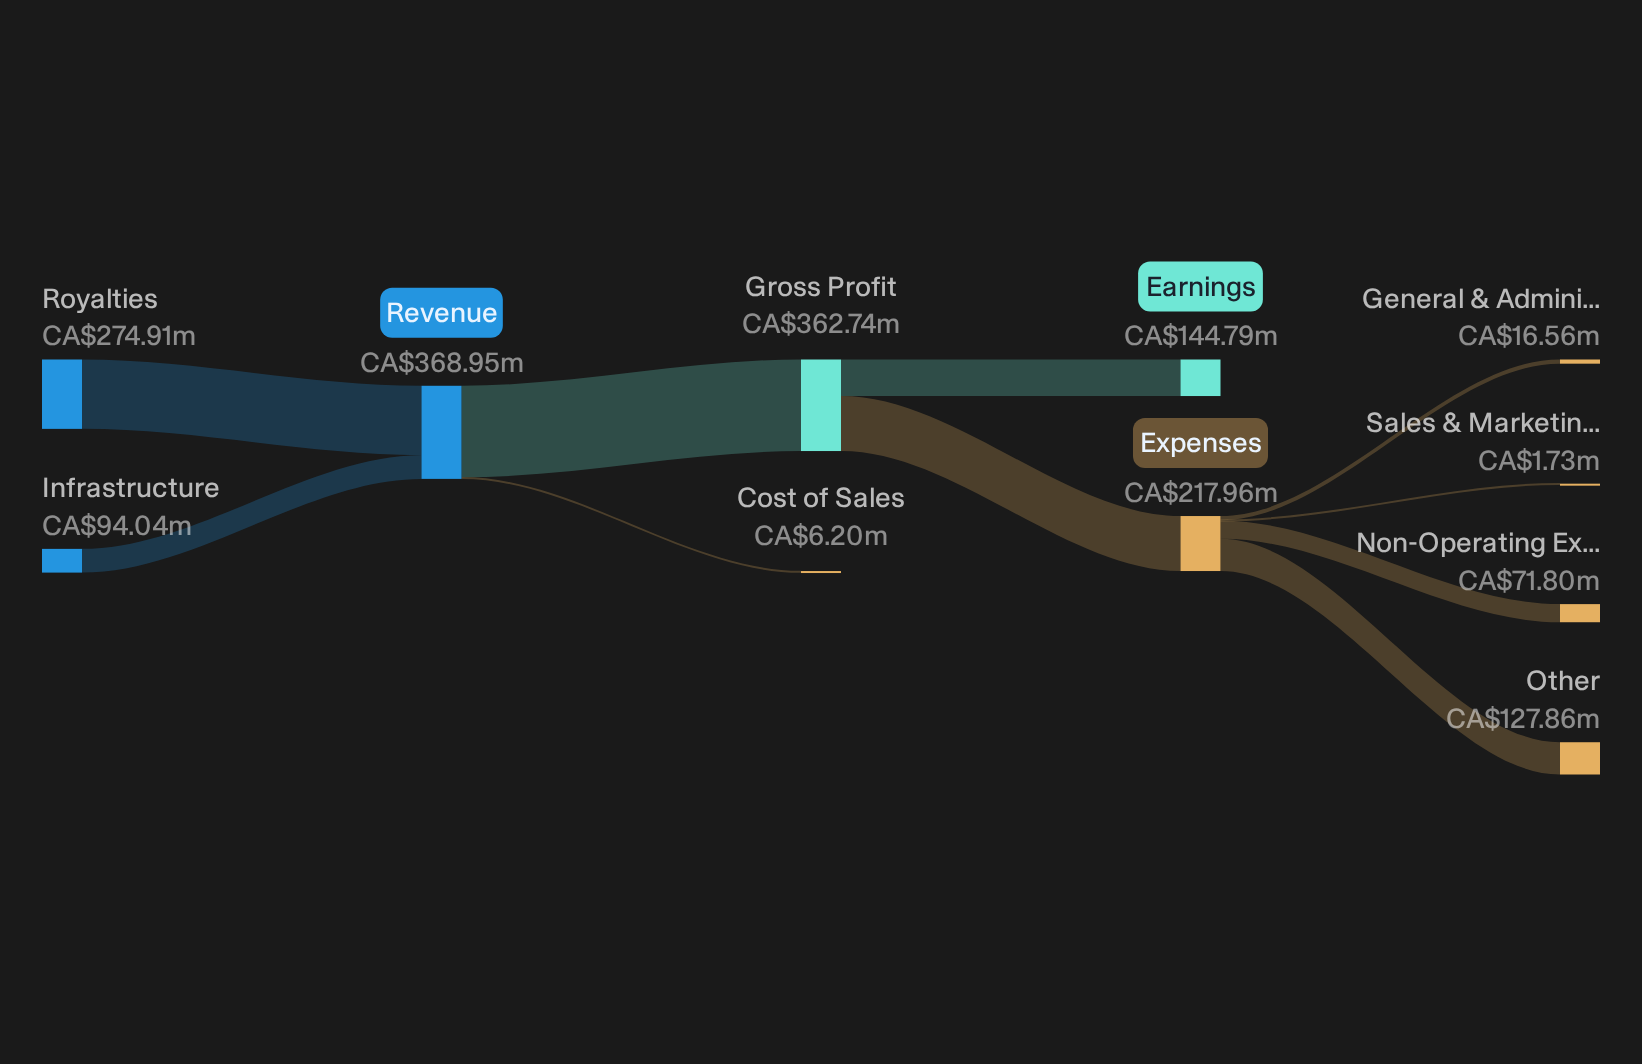
Topaz Energy is a Calgary based royalty and energy infrastructure owner linked to non Russian Canadian basins, earning about CA$274.9 million from royalties and CA$94 million from infrastructure, with all revenue sourced in Canada and an equity value of roughly CA$4.6 billion.
Instead of trying to predict every commodity move, Topaz Energy leans on an asset-light model that clips a share of upstream output and midstream throughput tied to non Russian production, which is exactly what many investors look for in this screener.
"The asset-light royalty model with high cash conversion (91% free cash flow margin) and low operating expenses positions Topaz to maintain strong net margins and resilient earnings as investors continue to seek reliable, high-yielding income sources in a moderate interest rate environment."
What really matters is how one quiet shift in where future drilling and throughput capital lands ultimately shapes the durability of those cash flows.
That quiet shift is exactly what full narrative for Topaz Energy unpacks, revealing how Topaz Energy’s royalty engine could accelerate or stall as capital reallocates across Canadian basins.
Magnolia Oil & Gas (MGY)
Magnolia Oil & Gas is a pure U.S. producer that fits the Non Russian Oil and Gas Producers theme, with operations tied directly to domestic pricing rather than sanction exposed flows.
Magnolia Oil & Gas is a Houston based independent producer focused on acquiring, developing, and producing oil and gas in South Texas, generating about US$1.5b in Oil & Gas Exploration & Production revenue and carrying a market value near US$6.0b.
Investors looking for non Russian exposure backed by onshore barrels increasingly watch Magnolia Oil & Gas, since its South Texas footprint links directly into U.S. pricing, pipeline infrastructure, and policy rather than seaborne Russian cargoes or sanction sensitive intermediaries.
"The WildFire deal is set to more than double Magnolia Oil & Gas acreage in the Giddings field to over 810,000 net acres across the Eagle Ford and Austin Chalk."
What really matters next is how shifting pressure on Magnolia’s cash generation and reinvestment choices shapes the value of that larger footprint.
To see how that capital allocation puzzle really fits together, read the full narrative for Magnolia Oil & Gas and see where Magnolia Oil & Gas growth could be accelerating or stalling next.

Curious About Alternative Opportunities?
Fresh ideas move first. Breakout stories can gain momentum while you watch, and quiet winners stay under the radar for now. Do not get caught dropping behind, consider reviewing potential opportunities.
- Review the list of solid balance sheet and fundamentals (23 results) to explore businesses that maintain resilient cash flows and continue funding growth while weaker peers face challenges.
- Use the 39 power grid technology and infrastructure stocks to look for companies involved in building infrastructure that supports electrification before that theme becomes more widely followed.
- Access the 7 dividend fortresses to track high-yield payers that focus on maintaining distributions as interest rates and sentiment change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com