
Aura Minerals (AUGO) Secures $200 Million Loan On An Undervalued Growth Narrative
Aura Minerals (NasdaqGS:AUGO) drew fresh attention after arranging a new US$200 million syndicated loan at the holding company level. The facility is aimed at funding supplier obligations and production related costs.
For Aura Minerals, the new US$200 million loan lands after a powerful share price run, with a 90 day share price return of 43.5% and a year to date share price gain of 76.5%. The 1 year total shareholder return of 167.45% and very large 3 and 5 year total shareholder returns hint that investors have been steadily pricing in both growth potential and higher operational risk as fresh financing and production plans come into focus.
Scan stocks that reflect Aura Minerals' combination of fresh funding and production focus by reviewing our hand picked list of 36 elite gold producer stocks in one place.
For Aura Minerals, that mix of fresh funding and a surging share price raises a simple tension. Are investors tracking business fundamentals, or has sentiment raced ahead of what the current valuation supports?
Most Popular Narrative: 12% Undervalued
Aura Minerals closed at $88.25 while the most followed narrative places fair value closer to $100. This frames the recent loan against already supportive cash flow expectations.
The planned development of Era Dorada and either Matupa or Guatemala, with relatively contained initial capital requirements, positions the portfolio for multi-year volume growth. This may improve earnings durability and return on invested capital.
See why 7 investors see Aura Minerals as 12% undervalued.
That narrative uses an 8.96% discount rate and ties its fair value of about $99.96 to expectations for revenue growth of roughly 21.04% and profit margins near 43.87% over time.
Analysts behind this framework also assume a lower future P/E multiple of about 10.84x. This implies that the investment case leans more on higher earnings and cash generation than on a richer valuation multiple.
Against the latest close, this set of assumptions implies Aura Minerals trades at an 11.7% discount to that fair value estimate. The recent US$200 million holding company facility becomes one more piece readers can weigh against the projected growth and capital returns story already reflected in the narrative.
Result: Fair Value of $99.96 (UNDERVALUED)
Still, parts of the Aura Minerals story could break this undervalued case, including weaker gold prices or setbacks at projects such as Borborema or MSG.
Find out about the key risks to this Aura Minerals narrative.
Another View: Aura Minerals Through The Earnings Multiple Lens
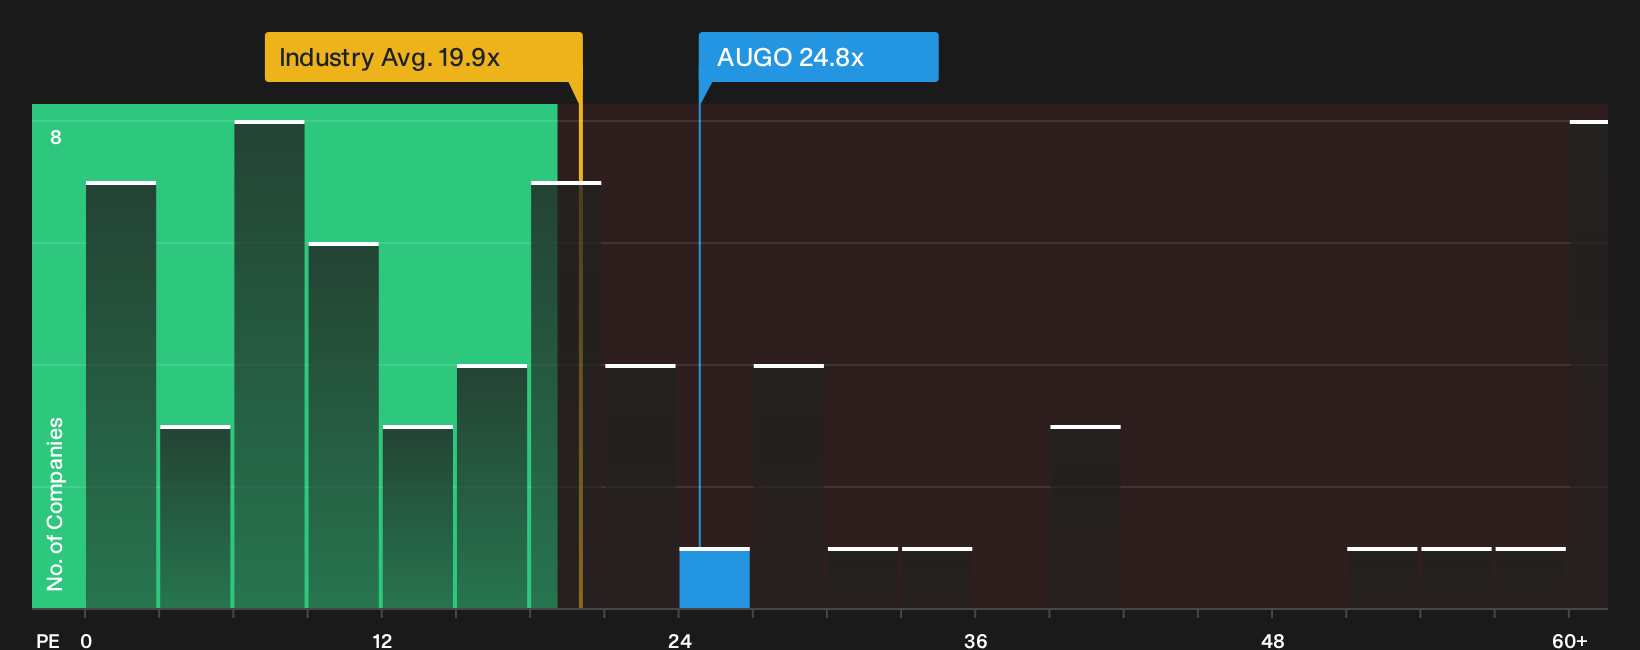
There is a very different picture once Aura Minerals is viewed through its P/E. The stock trades on roughly 24.8x earnings, compared with 19.9x for the wider US Metals and Mining group and 18.8x for peers, yet the fair ratio is estimated at 28.4x. That gap points to a premium tag today but also to room for the multiple to drift closer to the fair ratio. How comfortable are you paying up now for that possibility?
See what the numbers say about this price in our valuation breakdown, then weigh how much multiple risk you are willing to accept in return for the growth story already baked in. See what the numbers say about this price — find out in our valuation breakdown.
Use the valuation chart to see how Aura Minerals' current earnings multiple stacks up against its industry and that fair ratio estimate.
Next Steps
Sentiment around Aura Minerals is clearly mixed, with strong returns on one side and fresh financing risk on the other. Use the valuation tools, project assumptions, and risk disclosures to pressure test your own thesis quickly and on your own terms, then weigh both sides by reviewing 3 key rewards and 3 important warning signs.
Looking for more Aura Minerals style ideas?
If Aura Minerals has sharpened your focus on quality and risk, do not stop here. Use the Simply Wall Street Screener to uncover fresh, data driven opportunities before others get to them.
- Target resilient balance sheets and steady fundamentals by checking the list of solid balance sheet and fundamentals (23 results) that can support operations through different market conditions.
- Hunt for potential mispricings by scanning the 35 high quality undervalued stocks where business quality and valuation metrics line up more attractively.
- Spot future market favourites early by reviewing the 16 high quality undiscovered gems that combine solid fundamentals with limited current attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com