
Zuger Kantonalbank (SWX:ZUGER) Names A New CIO, Is The Premium Valuation Already Priced In?
Zuger Kantonalbank (SWX:ZUGER) has appointed Alexander Hunziker as Chief Investment Officer, promoting him from his previous role as deputy CIO. The leadership change may influence how the bank approaches investment processes and product design.
Investors have been pricing in a stronger story around Zuger Kantonalbank for some time. The share price is at CHF10,800 after a 20.81% year-to-date share price return and a 27.67% total shareholder return over the past year. The 50.14% three-year and 83.31% five-year total shareholder returns point to momentum that has been building rather than fading, as leadership changes such as the new CIO appointment shape expectations around future risk and opportunity.
Capitalize on the momentum around Zuger Kantonalbank by scanning a curated 183 high quality undervalued stocks that may offer similar quality profiles at different price points.Zuger Kantonalbank now combines a long history, a clear deposit and lending focus, and a strong recent share price run. The open question is whether the current CHF10,800 tag still reflects fair value.
Price-to-Earnings of 23.6x: Is it justified?
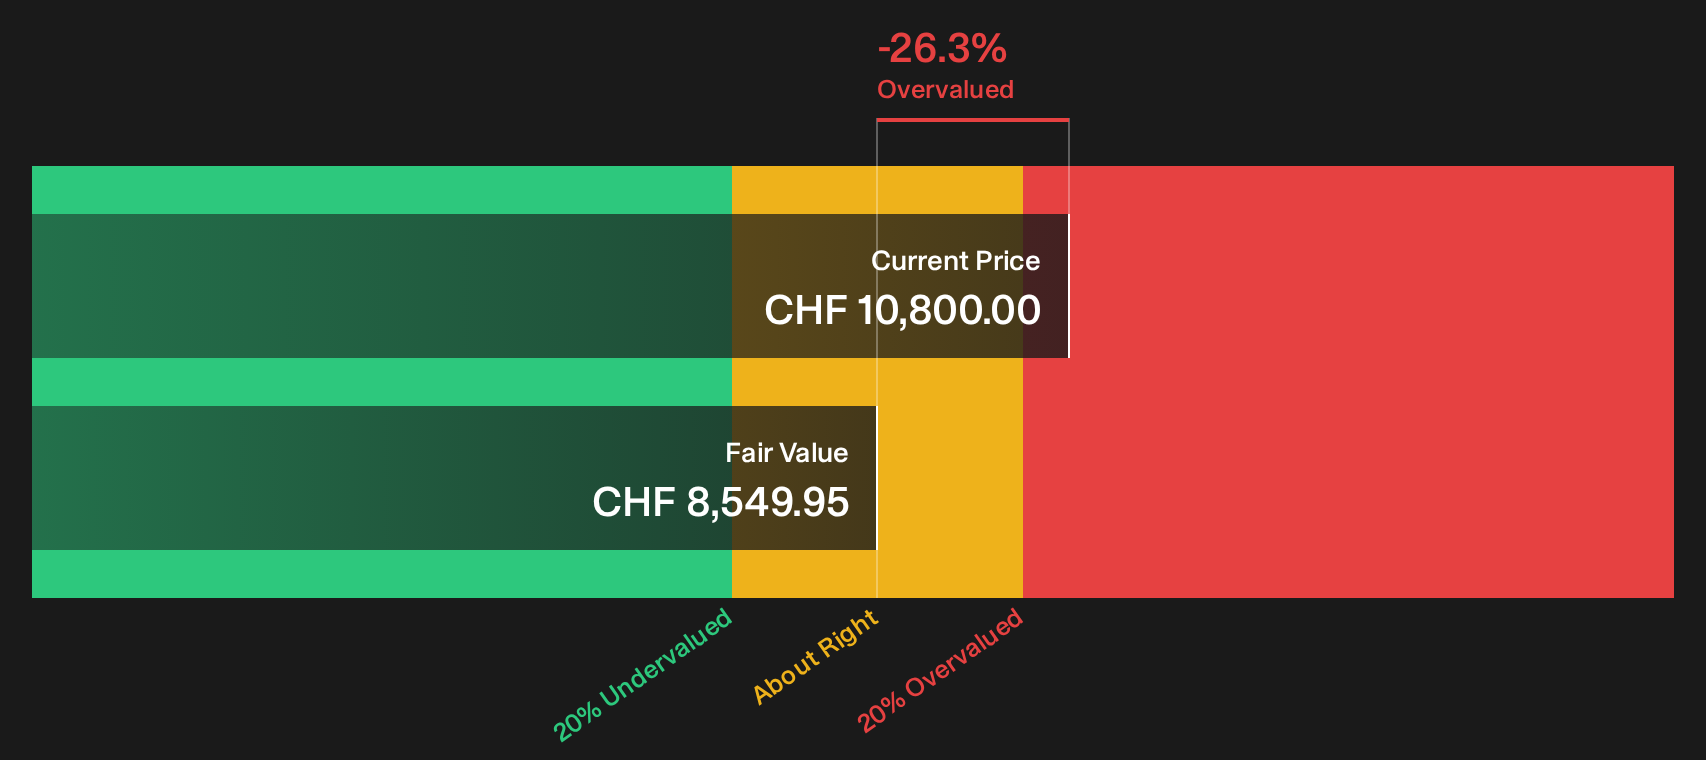
On simple metrics, Zuger Kantonalbank is not cheap. The shares trade on a P/E of 23.6x, while the stock is also above an internal SWS DCF fair value estimate of CHF8,549.95 based on future cash flows, compared with the current CHF10,800 price.
The P/E ratio compares the current share price with earnings per share and is a quick way to see how much investors are paying for each unit of profit. For a regulated lender such as Zuger Kantonalbank, it often reflects how the market weighs earnings quality, dividend profile, and perceived risk in the loan book.
Here, the 23.6x P/E is high relative to both the European banks group at 12.2x and a peer set at 18.7x. That signals investors are willing to pay a clear premium for Zuger Kantonalbank's CHF131.541m of net income, even though reported earnings fell 1.4% over the last year and the latest net profit margin of 39.9% is slightly below the previous 40.5% level.
Management quality and governance indicators add more context. The executive team has an average tenure of 4.3 years and the board sits at 7.3 years on average, with 86% of directors classed as independent. CEO compensation of about $1.29m is in line with Swiss peers of similar size and has moved broadly in step with recent performance.
Operationally, the bank reports high quality earnings and a reliable 2.13% dividend yield, but an 8.1% return on equity is still assessed as low against a 20% benchmark. The allowance for bad loans is described as low at 66%, which signals limited coverage of impaired exposures and is something careful investors may track alongside any change in credit conditions.
Past profit growth has been solid on a longer view, with earnings expanding at 11.6% per year over five years, even though the most recent year showed a 1.4% decline that breaks that trend. There is insufficient data on forward revenue and profit forecasts, as well as return on equity projections, so the market premium embedded in the 23.6x P/E is not easily cross-checked against published growth expectations.
On the return side, Zuger Kantonalbank has rewarded patient holders. The stock delivered a 27.67% total shareholder return over the past year and has compounded at 50.14% over three years and 83.31% over five years. That still lagged the Swiss banks sector over the last twelve months, which returned 34.3%, even as it comfortably exceeded the broader Swiss market gain of 12.2%.
Putting it together, investors today are paying a premium P/E multiple and a price above the SWS DCF estimate for a regional bank with experienced leadership, strong recent shareholder returns and high reported earnings quality, but also a low return on equity, a low loan loss allowance and a lack of clear forecast data. That mix leaves the current valuation firmly in premium territory rather than bargain territory.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 23.6x (OVERVALUED)
Still, the low 66% allowance for bad loans and limited forward estimates on Zuger Kantonalbank leave the premium P/E exposed if credit quality or sentiment weakens.
Find out about the key risks to this Zuger Kantonalbank narrative.
Another View on Zuger Kantonalbank’s CHF10,800 Price Tag
The SWS DCF model tells a different story for Zuger Kantonalbank. Based on those future cash flow estimates, fair value is CHF8,549.95, which is below the current CHF10,800 price. That gap suggests there may be limited margin for error if conditions or sentiment around the bank change.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Zuger Kantonalbank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 183 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Opinions differ on whether Zuger Kantonalbank's premium is justified or excessive. Review the underlying figures yourself promptly, then consider the 1 key reward and 1 important warning sign.
Looking for more Zuger Kantonalbank sized opportunities?
If Zuger Kantonalbank has sharpened your focus on quality and valuation, do not stop here. Broader idea hunting often uncovers opportunities you would otherwise miss.
- Target potential mispricings and compare them with Zuger Kantonalbank by scanning a focused list of 183 high quality undervalued stocks that meet disciplined fundamental checks.
- Build a steadier income stream alongside Zuger Kantonalbank by reviewing hand picked 159 dividend fortresses that combine yield with robust business profiles.
- Prioritise resilience by screening for a curated 227 resilient stocks with low risk scores that emphasises balance sheet strength and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com