
DIS Stock Alert: What to Know as Disney Creates First-Ever Chief Technology Officer Role
Disney (DIS) stock is in focus on Monday after the entertainment giant said it has appointed former Character.AI chief executive Karandeep Anand as its first-ever chief technology officer (CTO). Starting Oct. 2, Anand will oversee the conglomerate’s enterprise technology, infrastructure, engineering, data, and artificial intelligence (AI) platforms divisions to centralize its digital and streaming ecosystem.
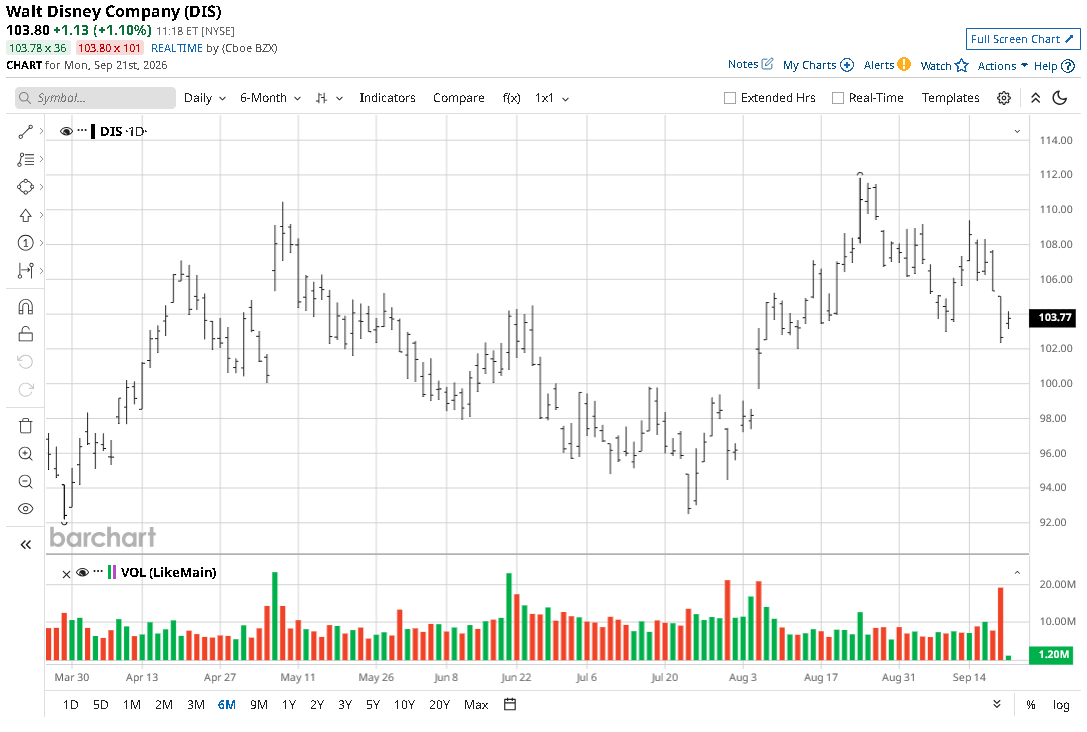
At the time of writing, Disney shares are down about 8% versus the start of this year.
Significance of the CTO Role for Disney Stock
Centralizing tech operations under a seasoned veteran with a background at Microsoft (MSFT), Meta (META), and generative AI signals Disney’s commitment to modernizing its tech stack.
Anand’s focus on unifying streaming platforms (like Disney+), theme park digital interfaces, and data infrastructure is designed to boost operational efficiency and monetization.
Investors view this strategic overhaul as a proactive step to maximize AI, improve user retention, and streamline enterprise expenses.
While top-level management additions rarely move a massive market cap instantly, this structural focus addresses long-standing calls for better digital integration, potentially improving margins over time.
Is It Worth Investing in DIS Shares Today?
Trading at a forward price-to-earnings (P/E) ratio of nearly 15x, Disney shares offer an intriguing risk-reward setup for long-term investors, especially since they currently pay a dividend yield of about 1.46% as well.
DIS has lagged the broader market in 2026 due to linear TV declines and theme park normalization.
But the creation of a dedicated CTO role, combined with steady streaming growth and consistent dividend payouts, lays the groundwork for sustained operational recovery.
That said, some near-term volatility is expected given Disney currently sits below its major moving averages (MAs), with an RSI in the early 40s indicating significant selling pressure.
What’s the Consensus Rating on Disney?
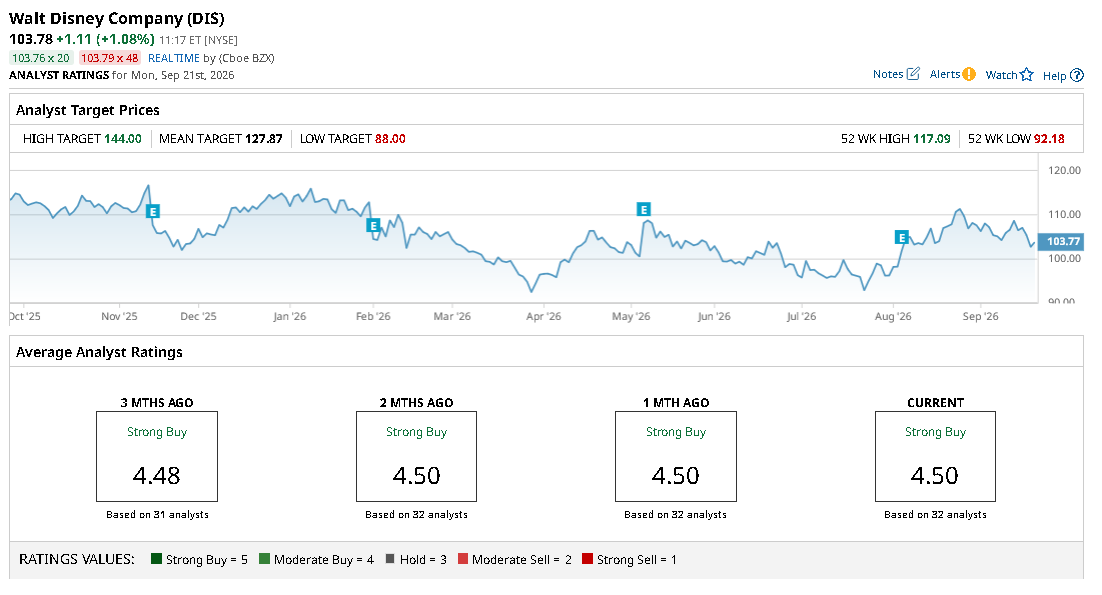
Despite muted year-to-date performance, Wall Street analysts remain convinced that DIS shares are currently undervalued and are worth owning for the longer term.
According to Barchart, the consensus rating on the mass media and entertainment behemoth sits at “Strong Buy” currently, with the mean price target of $128 indicating potential for a nearly 25% rally through the remainder of 2026.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.