
Biotest (XTRA:BIO3) Draws Fresh Attention As Valuation Signals Pull In Opposite Directions
Biotest (XTRA:BIO3) drew investor attention after its latest share price move, with the stock closing at €28.40. That shift has traders revisiting how the plasma specialist’s fundamentals line up.
Viewed against the past year, Biotest’s latest move comes after a 1-year total shareholder return of 4.94% and a 3-year total shareholder return that declined 18.97%, which suggests short term momentum has been steadier than the longer run record.
Compare Biotest’s recent move with peers by scanning a curated list of list of solid balance sheet and fundamentals (199 results) that may offer a different mix of resilience and return potential.
Biotest now trades at €28.40, yet its calculated intrinsic value points in a different direction. How wide is that gap, and what does the recent move say about where fair value really sits?
Preferred Price-to-Sales Multiple of 1.8x: Is it justified?
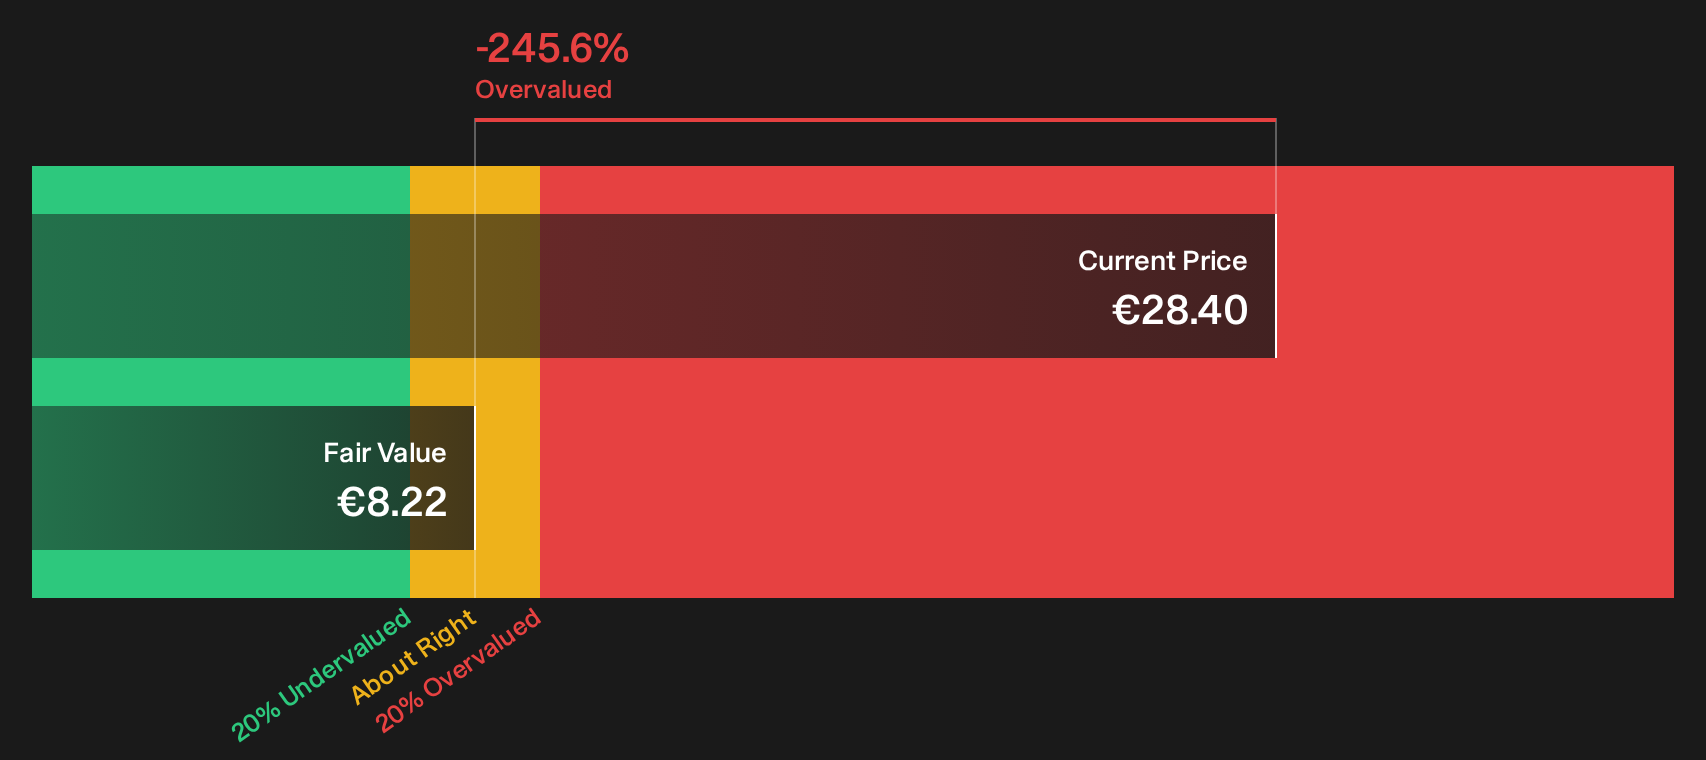
On a simple revenue lens, Biotest looks inexpensive. The stock trades on a P/S of 1.8x, while the SWS DCF model points to a fair value of €8.22 versus the current €28.40. Investors are weighing a low sales multiple against a much lower cash flow based estimate.
The P/S ratio compares the company’s market value with its annual revenue. For a plasma and biotech specialist like Biotest, where earnings are negative and net income can swing with R&D and clinical costs, sales based metrics often become a shorthand for how the market values the commercial engine rather than current profit.
Biotest’s P/S of 1.8x sits far below both its selected peer group at 23.8x and the broader European biotechs average of 8.9x. That gap is wide, and it suggests investors are applying a heavy discount to each euro of revenue even after accounting for the business reporting a loss of €24.5m and interest payments that are not well covered by earnings.
The contrast between the low P/S and the SWS DCF estimate is sharp. While the multiple indicates the shares are inexpensive relative to sector revenue norms, the DCF output of €8.22 per share, with the stock at €28.40, indicates Biotest is trading well above that model’s fair value and that cash flow expectations embedded in the price are demanding.
Result: Price-to-Sales of 1.8x (UNDERVALUED).
See what the numbers say about this price — find out in our valuation breakdown.
Still, Biotest carries clear risks, including ongoing losses of €24.5m and interest expenses that current earnings do not comfortably support.
Find out about the key risks to this Biotest narrative.
Another View On Biotest’s Value
The earlier revenue based lens made Biotest look inexpensive, yet the SWS DCF model tells a very different story. With a fair value estimate of €8.22 against a share price of €28.40, the stock screens as overvalued on cash flows. Which signal should matter more for you right now?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Biotest for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 183 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Unsure how Biotest’s combination of valuation signals and reported losses should affect your view right now? Consider reviewing the underlying numbers promptly and weighing the 2 important warning signs carefully.
Looking for more Biotest sized investment ideas?
Do not stop with Biotest. Broaden your opportunity set by using targeted stock lists that surface different combinations of value, quality and income potential.
- Target potential upside in quality businesses trading at compressed valuations by scanning a curated mix of 183 high quality undervalued stocks aligned with disciplined fundamentals.
- Lock in the possibility of steadier cash returns by reviewing a focused set of income opportunities through 159 dividend fortresses that emphasise higher yields.
- Limit unpleasant surprises by focusing on resilience first and filtering the market with 229 resilient stocks with low risk scores designed to highlight more robust balance sheets and risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com