
Dollarama (TSX:DOL) Could Be 25% Undervalued As It Lifts Sales Guidance
Dollarama (TSX:DOL) just delivered a busy September 16 update, pairing higher same store sales guidance for fiscal 2027 with fresh second quarter numbers and a modest uptick in planned store openings.
That guidance upgrade lands after a tougher stretch for the shares. Dollarama's 1-day share price return of 0.83% and 7-day gain of 3.46% follow a year to date decline of 15.52%. The 5-year total shareholder return of 210.57% shows the longer trend remains strong, suggesting that recent weakness may reflect a reset in expectations rather than a fundamental shift in how the market views the business.
Scan how Dollarama stacks up against other retailers riding similar earnings and guidance upgrades by checking our hand picked list of 5 high quality undervalued stocks.
Dollarama trades well below the average analyst target and also below one intrinsic value estimate, even after the latest bounce. Where does fair value actually line up in that spread?
Most Popular Narrative: 25% Undervalued
On the most followed narrative, Dollarama screens as undervalued, with a fair value of CA$232.00 against the last close at CA$174.18. This puts the spotlight on how growth, margins, and store expansion assumptions are being used to bridge that gap.
Analysts broadly agree Dollarama's store network can grow to 2,200 in Canada by 2034, but this may be a significant understatement. Record quarterly net new store openings and the ongoing migration of consumers toward value retail suggest the pace of store growth could exceed current expectations and drive even stronger revenue and market share gains.
See why 6 investors see Dollarama as 25% undervalued.
Result: Fair Value of CA$232.00 (UNDERVALUED)
Still, the bullish Dollarama narrative could be knocked off course if wage and compliance costs bite harder than expected, or if supply chain disruptions pressure margins.
Find out about the key risks to this Dollarama narrative.
Another View on Dollarama’s Valuation
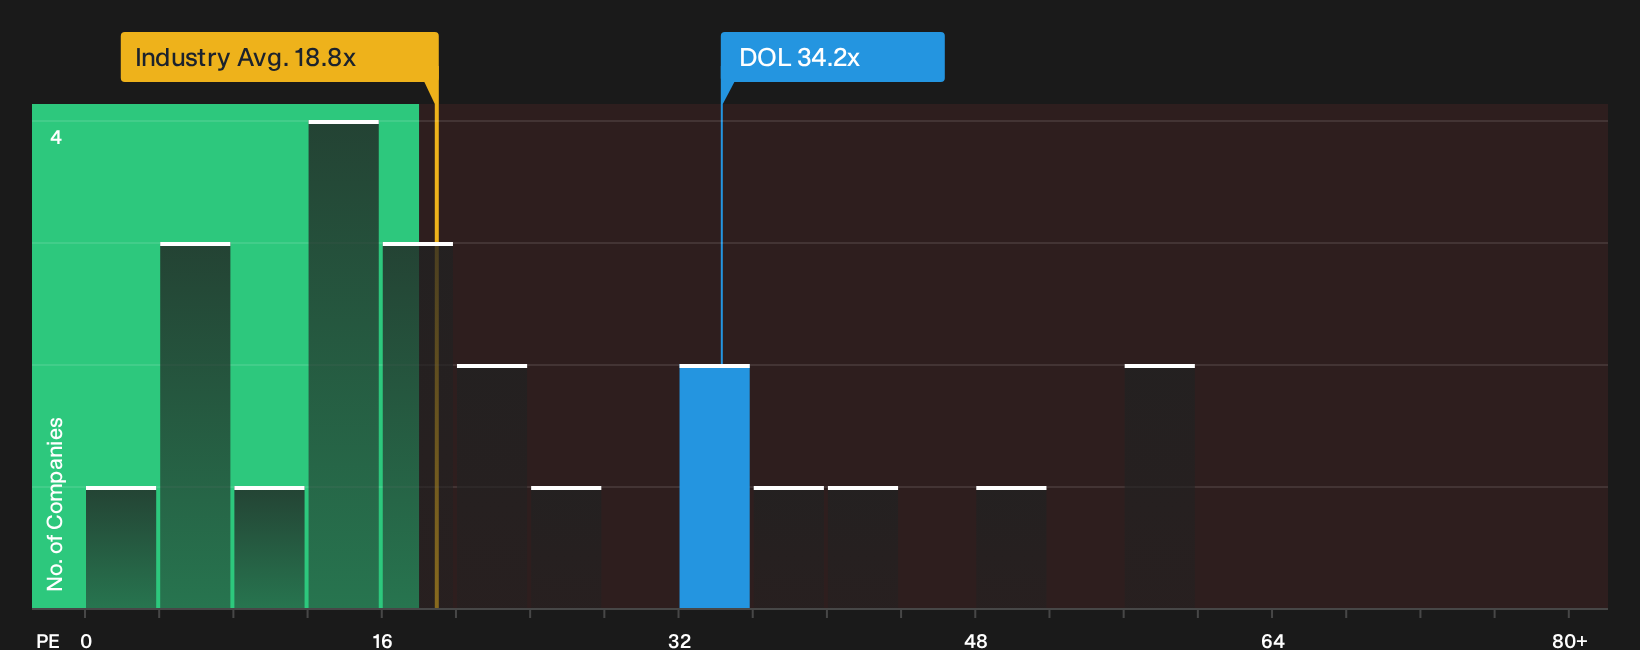
That 25% undervalued narrative runs into a very different signal once you look at simple pricing metrics. Dollarama trades on a P/E of 34.2x, while global multiline retail peers sit nearer 18.8x and its own fair ratio sits at 25x. This points to clear valuation risk rather than an obvious bargain.
If you prefer to anchor on comparative pricing instead of bullish forecasts, this gap raises a straightforward question. Is the current premium a temporary stretch that could compress toward that fair ratio, or is it the going rate investors are willing to keep paying for Dollarama's track record, even with debt and slower near term earnings forecasts in the mix?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With both bullish and cautious views on the table for Dollarama, this is a moment to move quickly and test the story against the numbers yourself. To see the balance of concerns and potential upsides in one place, review the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Dollarama?
If you stop at Dollarama, you miss a wider set of opportunities. Put a few minutes into scanning other stocks and you might spot your next winner early.
- Explore potential upside in smaller companies by checking the 21 elite penny stocks with strong financials that combine growth stories with stronger financial profiles.
- Prioritise quality at a reasonable price by reviewing a focused 5 high quality undervalued stocks that filters for both solid balance sheets and healthier cash flows.
- Reduce portfolio stress and smooth the ride by screening for 8 resilient stocks with low risk scores that score well on resilience and financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com