
Learn Why The Bull Case For Biogen Stock Could Change Following At Home LEQEMBI Approval
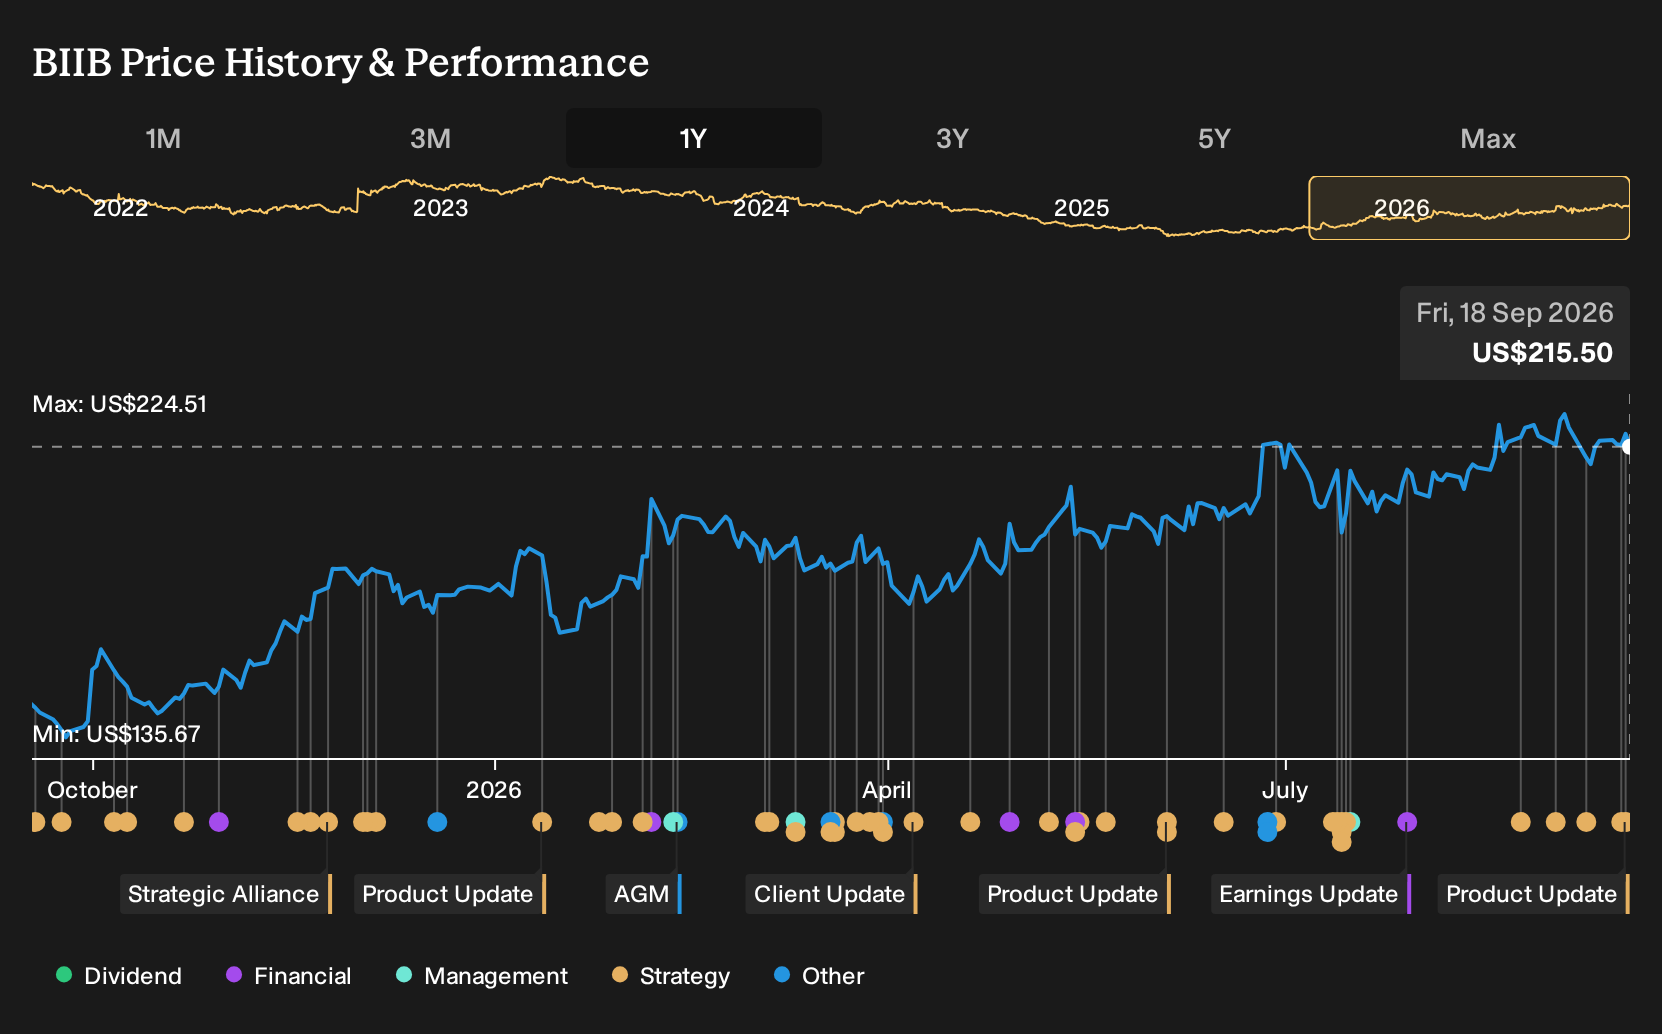
- Biogen and Eisai recently reported multiple product updates, including Japan and China approvals for at-home subcutaneous LEQEMBI and fresh adolescent EMPAVELI Phase 3 data showing clinically meaningful proteinuria reductions and kidney function stabilization in rare kidney disease.
- These moves concentrate Biogen’s efforts on therapies that can be administered at home or in younger high-need patients. This can reshape treatment logistics, operational demands, and long-term demand visibility for its neurology and nephrology portfolio.
- We will now look at how Biogen’s investment narrative could shift given new at-home LEQEMBI delivery options in key Asian markets.
Scan how Biogen’s push into at-home neurology and rare kidney disease care compares with other potential opportunities by reviewing 37 healthcare AI stocks, which are already repositioning treatment around patient convenience and specialised therapies.
Biogen Investment Narrative Recap
For Biogen, the core belief is that a concentrated group of neurology and rare disease launches can offset pressure in mature MS and biosimilar franchises. The big near term swing factor remains how efficiently LEQEMBI and newer franchises like SKYCLARYS and ZURZUVAE convert approvals into steady, reimbursed usage. The recent EMPAVELI and LEQEMBI updates support that story but do not fully change it.
The biggest risk still sits in execution. Any slowdown in uptake or pricing pressure across this tight cluster of therapies could hit margins that are already narrower than a year ago. Cost controls and fit for growth efforts help, yet they depend heavily on those launches doing the heavy lifting.
The adolescent VALIANT subgroup analysis for EMPAVELI looks most relevant here, because it aligns with Biogen’s push in specialty, high unmet need segments. There is now one of the larger randomized datasets in 12 to 17 year olds with C3G or primary IC MPGN, with clinically meaningful proteinuria reductions and kidney function stabilization versus placebo at 26 weeks.
For investors, that dataset matters less as a headline and more as a sign of operational follow through in a rare, complex indication. It supports the existing US label for patients 12 and older and gives Biogen another proof point as it builds out nephrology alongside neurology catalysts such as LEQEMBI. Execution on access, safety monitoring, and REMS requirements still sits between this evidence and any durable contribution to the broader story.
Biogen's current analyst narrative points to revenues of US$11.1b and earnings of US$2.3b by 2029, which implies 3.3% yearly revenue growth and an earnings increase of about US$1.5b from US$834.6m today.
Uncover why Biogen's fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses squarely on pricing and reimbursement risk for Biogen. The most cautious analysts, who were modeling roughly flat revenue at about US$10.2b and earnings of US$1.7b by 2029 before this EMPAVELI and LEQEMBI news, see tighter payer budgets sharply limiting uptake. That is a far more pessimistic setup. Consider it a prompt to compare several viewpoints before deciding how these new at-home and adolescent data might reshape expectations.
Explore 4 other Biogen fair value estimates, including one that suggests as much as 14% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Biogen research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Biogen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Biogen's overall financial health at a glance.
Looking for more Biogen sized investment ideas?
Once you have a view on Biogen, it can help to put it alongside a wider watchlist so you can weigh the trade offs across quality, risk, and income potential using the Simply Wall St Screener.
- If capital preservation and steadier businesses matter most to you, scan companies screened for resilience and financial strength through 30 resilient stocks with low risk scores.
- If you want to balance quality with a margin of safety, compare Biogen with candidates in the 35 high quality undervalued stocks that pair solid fundamentals with discounted pricing.
- If income is a priority, line Biogen up against companies screened for reliable cash payouts using the 7 dividend fortresses and see which yields and pay out profiles fit your goals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com