
Lincoln National (LNC) Stock Still Looks Cheap After A 100% Run
Lincoln National has delivered a very strong 3 year share price run, yet the question for you today is whether the current valuation is properly grounded in the insurer's earnings power. With the stock recently closing at US$42.20, the focus turns to what that price really asks you to pay for its profit stream.
- The share price has gained 100.3% over the past 3 years, which puts a lot of weight on whether Lincoln National's earnings profile can support that kind of re-rating.
- For a life insurance group like Lincoln National, the durability of underwriting profits, investment income and capital strength can shape how much investors are willing to pay for each dollar of earnings.
- Your read on Lincoln National is one view; the desks covering it have another. See what analysts think Lincoln National's shares could be worth.
The issue now is whether Lincoln National's current share price is justified by its earnings when set against the Fair Ratio benchmark.
If you want a second reference point while you assess whether Lincoln National’s earnings support its recent 3 year run, you can start a shortlist with a focused stock screen built from 35 high quality undervalued stocks.
Is Lincoln National Still Cheap on Earnings?
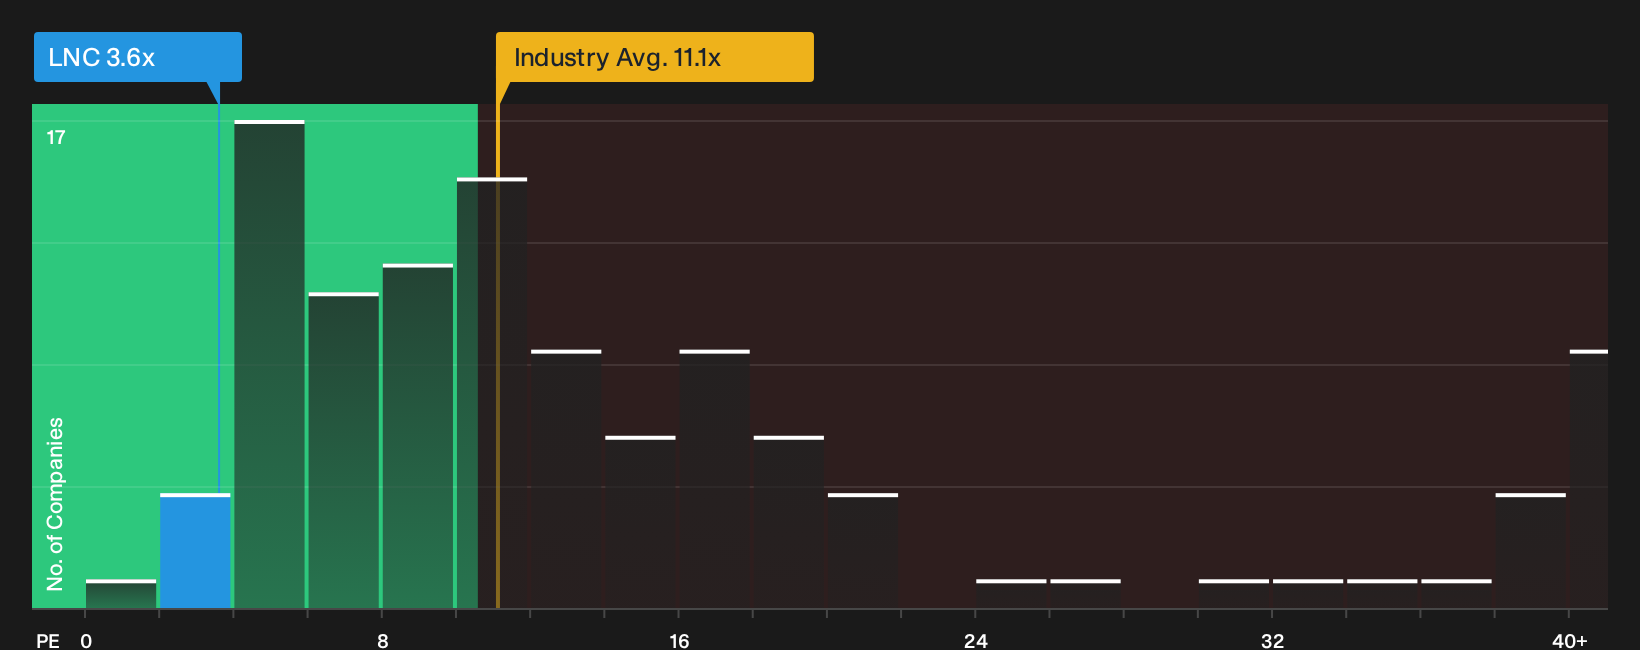
The P/E ratio works well for Lincoln National because earnings remain a core yardstick for how investors judge a life insurer's profitability. On this lens, the stock trades on a P/E of 3.6x, which is far below the Insurance sector average of 11.1x and well under the peer group level of 38.6x. That is a steep gap for a business where reported profits and regulatory capital often drive how the market thinks about value.
The Fair Ratio model, which adjusts the earnings multiple for Lincoln National's projected returns on equity, book value profile, size and risk, points to a higher P/E than the market is currently paying. Based on that framework, the share price screens as undervalued on earnings, with investors assigning a sizable discount to each dollar of profit relative to what this tailored benchmark implies. You would still want to weigh the quality and stability of those earnings, especially in the context of life insurance liabilities and investment portfolios, before leaning too heavily on the raw multiple. Explore the numbers behind Lincoln National's P/E valuation.
The Lincoln National Narrative: What Would Justify Today's Price?
Narratives for Lincoln National pick up where the P/E and Fair Ratio leave off, and set out the specific future paths for growth, margins and earnings that would make today’s price look either too low or too demanding. They turn a single valuation output into a set of concrete assumptions about Lincoln National's future that you can watch over time and compare with what is actually happening in the business.
Community views on Lincoln National are split between investors who see a discounted transformation story and those who think optimism already runs ahead of the cash flow and capital plan.
Bull case: 10% undervalued
"Lincoln National's transformation toward a more diversified and capital-efficient product mix, especially in higher-margin, less capital-intensive areas like supplemental health and spread-based annuities, positions them to benefit from rising demand as Americans focus more on retirement readiness and financial wellness..."
Discover why this Narrative puts Lincoln National at 10% undervalued.
Bear case: 18% overvalued
"Operational investments in technology and talent, while necessary, could lead to higher near-term expenses, thereby compressing net margins before they generate expected increases in free cash flow..."
Explore why this Narrative puts Lincoln National at 18% overvalued.
One more piece of the Lincoln National puzzle before you move on
Before you decide how to treat Lincoln National's current valuation, it is worth seeing how the professional forecasting community maps out the business a few years from now and whether those expectations line up with your own. Explore where analysts expect Lincoln National to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com