
Prediction: This Data Center Stock Will Be the AI Supercycle's Biggest Winner -- and It's Not a Household Name
Key Points
Lumentum stock has surged phenomenally over the past year, and the good news is that it can continue to soar.
Lumentum will benefit from strong demand for optical networking and a tight supply environment.
The company's terrific earnings growth potential indicates that it can make investors richer over the next three years.
Artificial intelligence (AI) data center demand isn't slowing down any time soon, as major hyperscalers and AI companies need to satisfy the huge contractual backlogs they're carrying.
Forbes reports that hyperscalers and AI companies have more than $3 trillion in purchase commitments and uncommenced leases. This explains why investments in AI data centers could surge from $800 billion annually in 2026 to a whopping $1.8 trillion a year in 2050, according to PwC. There are several ways investors can capitalize on this AI infrastructure supercycle.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
One can consider buying top chipmakers such as Nvidia and Broadcom, or investing in memory stocks, such as Micron Technology. However, I believe that Lumentum Holdings (NASDAQ: LITE) could be one of the biggest winners of the AI infrastructure boom. Let's look at the reasons why.
Image source: Getty Images.
Lumentum Holdings may not be a household name, but it has been delivering incredible returns
Lumentum Holdings stock has shot up by a stunning 452% over the past year. The stock's multibagger returns have been powered by a terrific increase in its revenue and earnings.
Lumentum manufactures optical networking and photonic products that enable high-speed networking in AI data centers and cloud networks. The demand for Lumentum's products has shot up remarkably. AI accelerators need to be quickly fed with huge data sets so that they can train large language models (LLMs), run inference applications, and AI agents.
As a result, the demand for optical networking and photonics components is outpacing supply, leading to a big jump in Lumentum's margins. The company's non-GAAP operating margin in the recently concluded fiscal 2026 (which ended on June 27) tripled year over year to 29.8%. This explains why Lumentum's non-GAAP earnings per share (EPS) increased by more than 4x in fiscal 2026 to $8.67.
The good news for investors is that it isn't too late to buy this AI stock yet. After all, Lumentum is poised to win big from the next big bottleneck in the AI infrastructure space. According to Goldman Sachs, optical networking is poised to become the next big megatrend in the AI infrastructure market. This isn't surprising, as fast networking is critical for the seamless operation of AI data centers.
The investment bank expects the optical networking total addressable market (TAM) to increase from $15 billion in 2026 to a whopping $154 billion in 2028. Goldman Sachs notes that a major jump in the dollar content of optical components in AI data center clusters will drive this massive increase.
Moreover, the average selling price (ASP) of optical components is poised to increase due to a tight supply chain, which isn't surprising, given the incredible ramp in demand over just two years. As a result, the stunning growth that Lumentum is enjoying is poised to continue.
Here's why this AI stock is going to soar higher
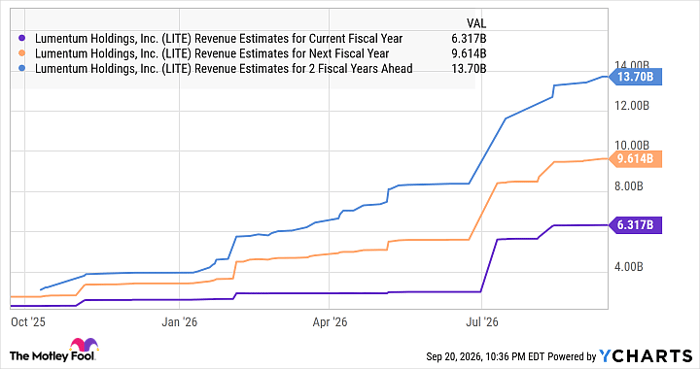
Analysts have become extremely bullish about Lumentum's growth prospects for the next three years.
Data by YCharts
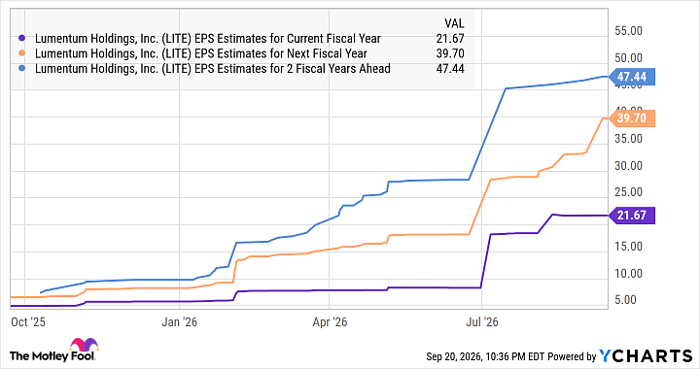
The company reported $3 billion in revenue in fiscal 2026. So, the company's top line will jump by more than 4x in just three years, as evident from the above chart. What's more, Lumentum's EPS growth will take off during this period, driven by a favorable pricing environment.
Data by YCharts
So, Lumentum's earnings are on track to jump nearly 5.5x in just three years, though the scale of demand for optical networking suggests it may do better. However, even if Lumentum's EPS increases in line with consensus expectations and reaches $47.44 in fiscal 2029, its stock price could hit $1,613 (assuming it trades in line with the tech-focused Nasdaq-100 index's earnings multiple of 34).
That suggests a potential jump of 73% in this tech stock. However, Lumentum could command a premium valuation due to its terrific growth, which could lead to bigger upside over the next three years. So, investors looking to benefit from the massive investments in AI data centers can consider buying Lumentum, as it is poised to benefit big time from the next leg of the AI infrastructure build-out.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Broadcom, Goldman Sachs Group, Lumentum, Micron Technology, and Nvidia. The Motley Fool has a disclosure policy.