
Do Higher Earnings And Dividend Raise Change The Bull Case For SHKP (SEHK:16)?
- Sun Hung Kai Properties reported full year 2026 sales of HK$94,194 million and net income of HK$21,426 million, alongside a proposed final dividend of HK$2.93 per share for approval at the November 2026 AGM.
- The proposed dividend, slightly above the prior year’s HK$2.80 per share, reflects management’s stated confidence in cash generation and long term capital return discipline.
- We will examine how Sun Hung Kai Properties' investment narrative is influenced by reported earnings and the higher proposed cash dividend.
Compare Sun Hung Kai Properties' dividend move with other cash generative opportunities by scanning our hand picked list of 159 dividend fortresses in today's market.
Sun Hung Kai Properties Investment Narrative Recap
To own Sun Hung Kai Properties, you need to be comfortable with a diversified real estate group that leans on Hong Kong housing launches, recurring rental income and side businesses like telecoms and data centres. The latest full year figures, with HK$94,194 million of sales and HK$21,426 million of net profit, suggest execution against that mix remains central.
The earnings call on 10 September 2026 sharpened the near term focus on Hong Kong residential sell through and rental resilience against soft spots in office and Mainland China. Ratings agency pressure and higher financing costs still look like the biggest swing factor, even with reported EPS of HK$7.39 and a relatively low gearing profile.
The recommended final dividend of HK$2.93 a share, up from HK$2.80, is the announcement that ties most directly into this catalyst and risk debate. A higher cash payout rests on the same cash flow that must support project spending, refinancing and new developments in Hong Kong and Mainland China.
For you as a shareholder, the dividend proposal highlights a trade off. On one side you have current income and management’s confidence in distributable profit. On the other, there is an unstable dividend track record, pressures on rental margins, a negative outlook from S&P and Moody’s, and the need to keep funding upcoming projects without stretching the balance sheet.
Sun Hung Kai Properties' current analyst narrative points to forecast revenue of HK$92.9b and projected earnings of HK$30.5b by 2029, with earnings today at HK$22.0b. That implies flat yearly revenue growth and an earnings increase of HK$8.5b from current levels.
Uncover why Sun Hung Kai Properties' fair value indicates a 27% potential upside to its current price, which could narrow quickly.
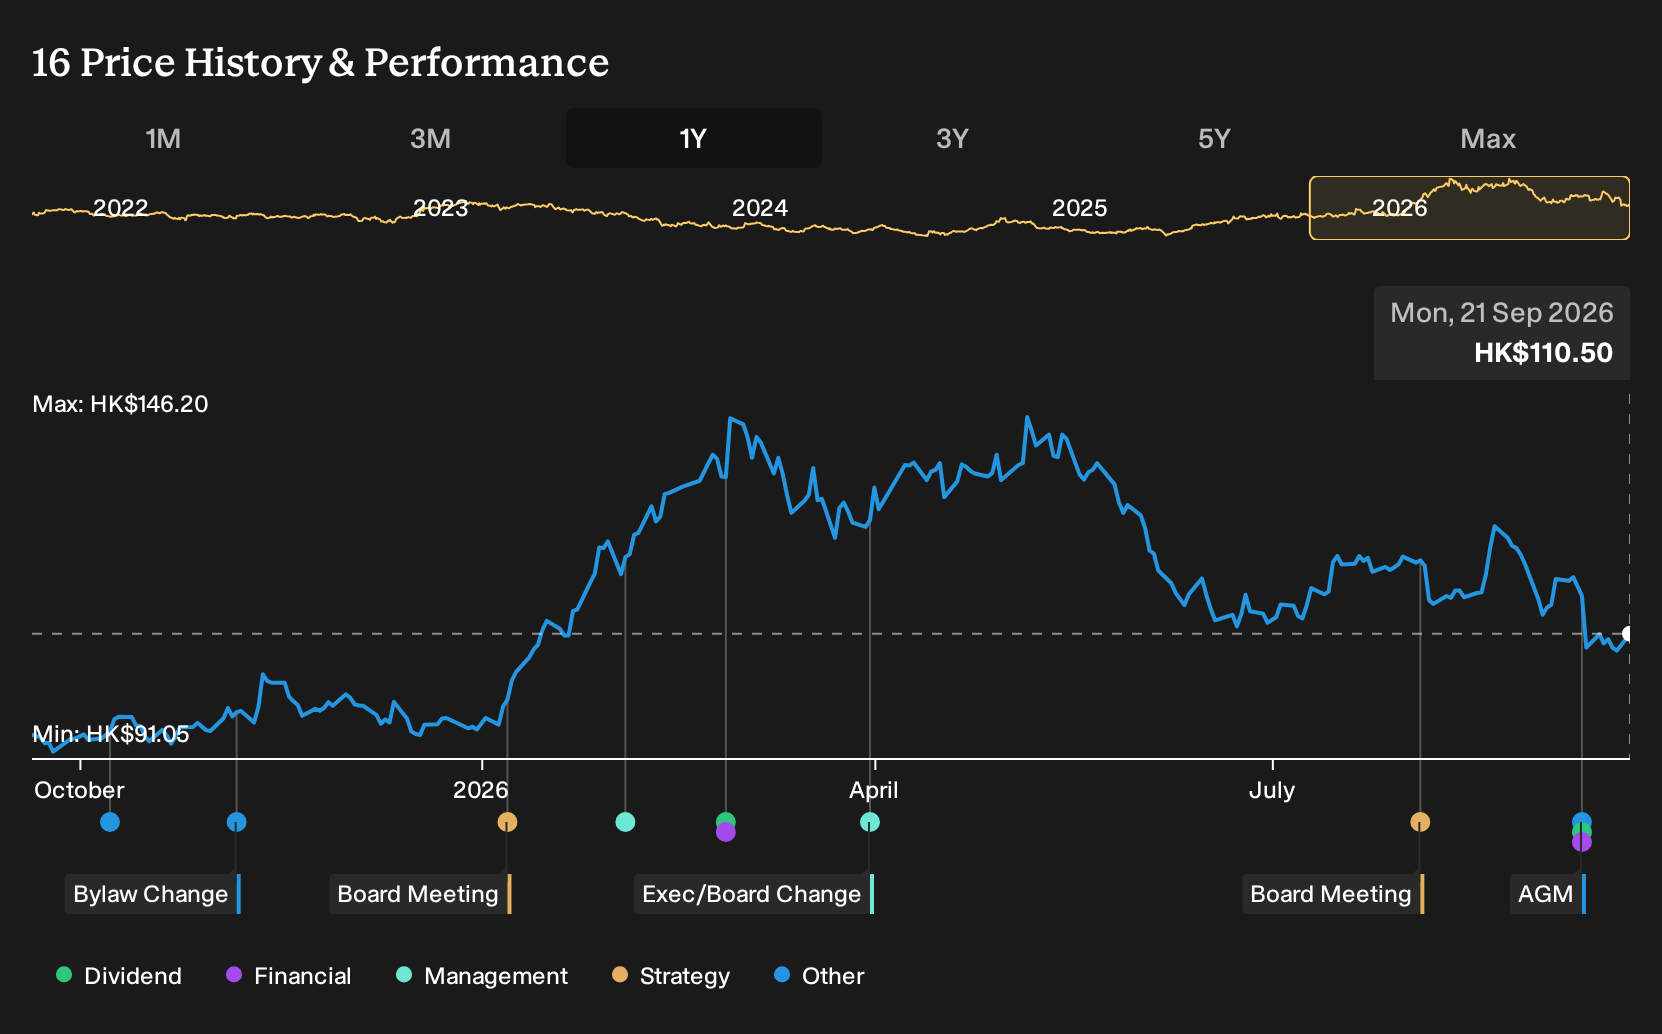
Exploring Other Perspectives
One alternate view on Sun Hung Kai Properties leans heavily on future margin expansion. The most optimistic analysts were pencilling in earnings of HK$34.3b on revenue of HK$98.6b by 2029, using a higher 18.8x P/E. Those forecasts were set before this dividend increase and earnings call, so opinions may evolve.
Explore another Sun Hung Kai Properties fair value estimate, including one that suggests potential upside of up to 27% from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Sun Hung Kai Properties research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sun Hung Kai Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sun Hung Kai Properties' overall financial health at a glance.
Looking for more investment ideas beyond Sun Hung Kai Properties?
If the Sun Hung Kai Properties story has sharpened your view on income, risk and balance sheet strength, it can be useful to line it up against other listed businesses that share some of the same traits, or lean in different directions entirely.
- For investors who care most about resilient income streams, consider screening for higher yielding companies with robust payout profiles using the 159 dividend fortresses.
- If capital preservation and steadier price swings are a priority, you may want to narrow the universe to businesses flagged for lower overall risk by running the 229 resilient stocks with low risk scores.
- For those hunting for underfollowed opportunities with solid fundamentals, take a look at the 615 high quality undiscovered gems to see which stocks currently fit that profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com