
Netflix Stock And 2 Smaller Streaming Plays In A Changed US Video Market
The Paramount and Warner Bros Discovery merger story is no longer just deal gossip. With a US$110b tie-up clearing a key hurdle and new commitments on film output, the streaming and AVOD video sector suddenly has clearer rules of the game and fresh pressure on rivals. That mix of reduced uncertainty and shifting competitive muscle can reshape where capital flows. This article walks through three stocks directly exposed to that news.
The three stocks below are only a starter pack, as the full screen surfaced 15 more U.S. listed streaming and AVOD video companies with equally compelling narratives that are not covered here.
If you want to move beyond a short list and actually identify, compare, and analyze the highest conviction streaming and AVOD opportunities, head straight to the U.S.-Listed Streaming and AVOD Video Platforms screener.
AMC Global Media (AMCX)
AMC Global Media is firmly tied to the streaming and AVOD theme through its mix of subscription apps, genre-focused channels and content licensing, giving investors exposure to both direct-to-consumer platforms and traditional TV networks in one compact media group.
AMC Global Media runs cable networks like AMC and We TV and a suite of niche streaming services such as AMC+, Acorn TV and Shudder, with Domestic Operations generating about US$1.94b and International contributing roughly US$309 million. The business has a market cap of about US$475 million.
"The ongoing acceleration of cord-cutting and migration away from traditional linear TV is likely to continue eroding AMC Networks' pay-TV subscriber base, resulting in persistent top-line revenue declines that streaming growth and price increases have so far been unable to fully offset."
This raises the question of what happens if a less visible pressure on AMC Global Media’s streaming economics starts to reshape how much of that content actually pays for itself.
If that pressure matters to your thesis on AMC Global Media, read the full narrative for AMC Global Media to see how cord-cutting trends and streaming economics could be decoupling.

CuriosityStream (CURI)
CuriosityStream is a pure-play streaming platform focused on factual video. It provides a relatively direct way to gain exposure to the screener theme of subscription and ad-supported online viewing, particularly as bigger studios recalibrate their own output and licensing appetite.
CuriosityStream generates about US$76 million from its Curiosity Stream segment, with the United States contributing roughly US$61 million of that total, and the business carries a market cap of about US$165 million.
"Surging demand for high-quality, rights-cleared video for AI training is driving a transformative new licensing revenue stream for CuriosityStream. Management cited recurring and growing partnerships with large-scale AI companies, establishing a durable, high-margin revenue base that is expected to fuel both top-line and earnings growth."
What really matters for investors is how a single shift in where that content is most valuable might change the long run economics.
That shift is exactly what the full narrative for CuriosityStream unpacks in detail, showing how CuriosityStream’s AI licensing story could accelerate or stall the whole business model.

Netflix (NFLX)
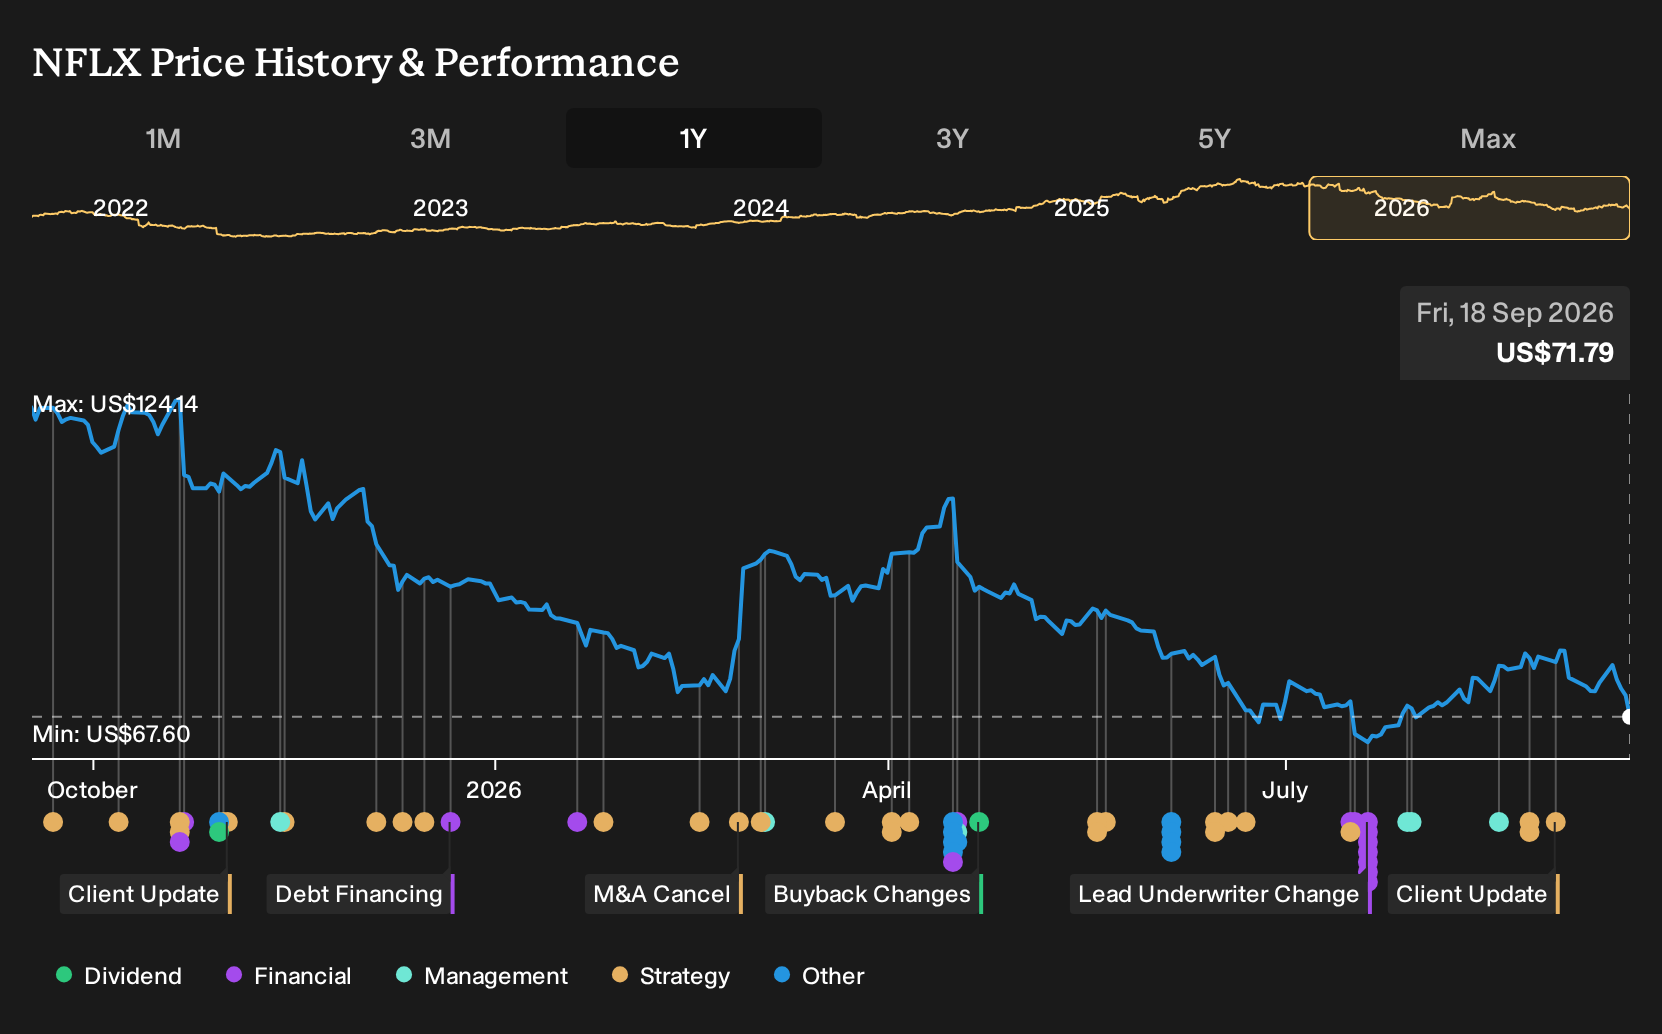
Netflix is the purest expression of this screener’s theme, a global subscription streamer built on premium TV, films, games and live events. It now generates almost all of its US$48.4b in revenue from a single streaming entertainment service line and commands roughly US$298.9b in market value.
"The bull case increasingly leans on pricing, advertising, margin expansion and buybacks rather than pure subscriber momentum."
The real swing factor for Netflix now is what happens if one quiet shift in how viewers engage with its newer formats changes the profit equation.
That inflection point is exactly where the full narrative for Netflix picks up. It maps how engagement, pricing and ads could accelerate Netflix’s next leg without ignoring the risk side.
Seeking Alternatives Before They Fly
Fresh ideas move first. By the time every chart shows a breakout, early momentum has often gone. Scan these under the radar lists before the crowd catches on and act now.
- Spot cash rich compounding potential by scanning a curated list of solid balance sheet and fundamentals (23 results) that helps you focus on businesses built to handle shocks while others are still scrambling.
- Ride structural demand shifts with a focused 39 power grid technology and infrastructure stocks that zeroes in on companies tied to the next phase of energy and infrastructure upgrades while it still feels early.
- Target real earnings engines using the curated 38 profitable AI stocks that aren't just burning cash. It filters for AI exposure with actual profit streams instead of stories running purely on hype.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com